Location: Liwan, Dubai – Ideally positioned between Dubai Silicon Oasis and Academic City, with direct access to Sheikh Mohammed Bin Zayed Road and Emirates Road. A fast-growing residential district surrounded by innovation hubs, leading schools, hospitals, and shopping malls.
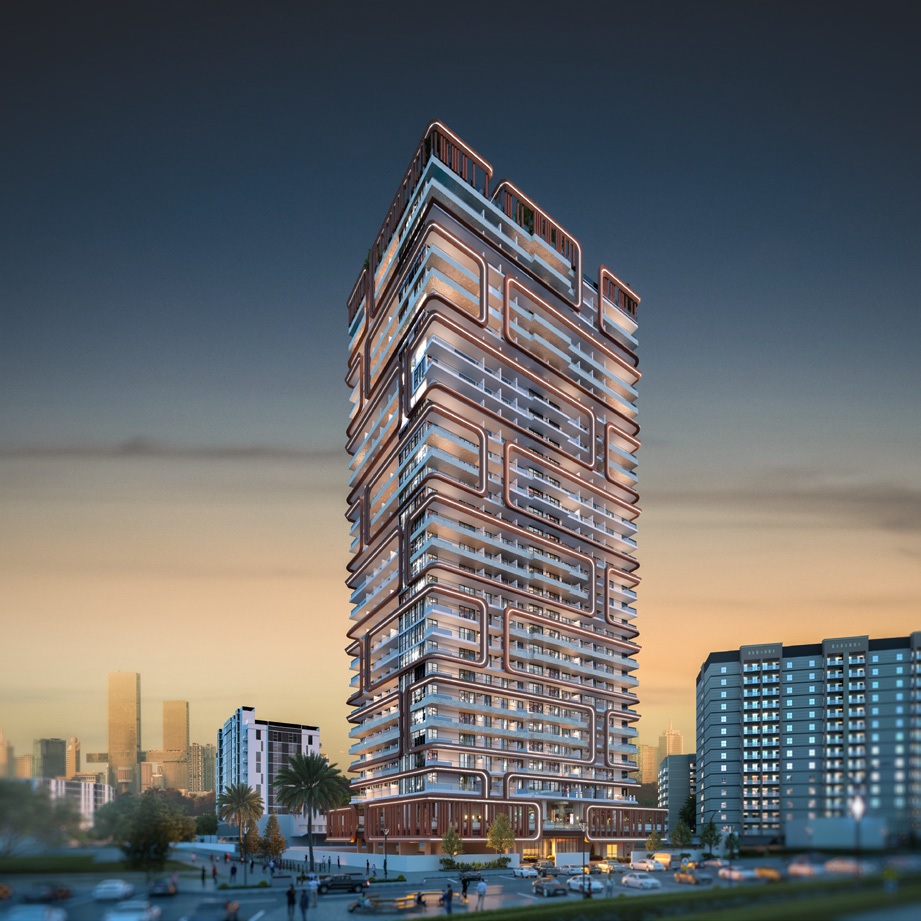
Empire Lakeviews Retail
Pricing and termsConnect for special pricing and payment terms.
Payment plan56/44
- Sizes
- 1,107 to 1,822 sq ft
Property
Empire Lakeviews by Empire Developments
Project Overview
- Mixed-Use Residential Tower with Ground-Level Retail
- 604 Apartments + 3 Street-Facing Retail Units
- Tranquil lake-facing views with landscaped surroundings
- Developed by Empire Developments (6th project in Dubai)
Building Configuration
G + 29 Floors
Retail Units: 3 (Sizes from 1,107 – 1,822 sq. ft.)
Total Residential Units: 604
Unit Mix: Studios, 1-Bedroom, 2-Bedroom, 3-Bedroom Duplex with Pool
Residential Units Overview
- Studios – From 407 sq. ft. | Starting AED 500,000
- 1-Bedroom – From 754 sq. ft. | Starting AED 700,000
- 2-Bedroom – From 1,320 sq. ft. | Starting AED 1.35M
- 3-Bedroom Duplex with Pool – From 2,634 sq. ft. | Starting AED 2.4M
Retail Overview
- 3 Ground Floor Retail Units
- Sizes: From 1,107 sq. ft. to 1,822 sq. ft.
- Starting Price: From AED 3,200 PSF
- Payment Plan: 56/44
- Completion Date: Q4 2027
- Handover: Q2 2028
Amenities (Resort-Style Leisure Deck + Sky Facilities)
- Infinity-edge pool, panoramic outdoor gym, and jogging track
- Amphitheatre, children’s play areas, mini golf course
- Basketball court, tennis court, paddle court, and co-working lounge
- Zen garden, pet park, reflection pond, and relaxation zones
- Concierge services and bicycle parking
Views
- Lake-facing units with serene landscaped outlooks
- Panoramic views across Liwan, Silicon Oasis, and Academic City
- Elevated open-air perspectives from upper floors
Illustrative model
Scenario modeller
Set your own assumptions and see how Empire Lakeviews Retail behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Nothing to calculate yet
Enter the asking price to run the model.
Every figure recalculates as you type. Use the price you are considering.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.