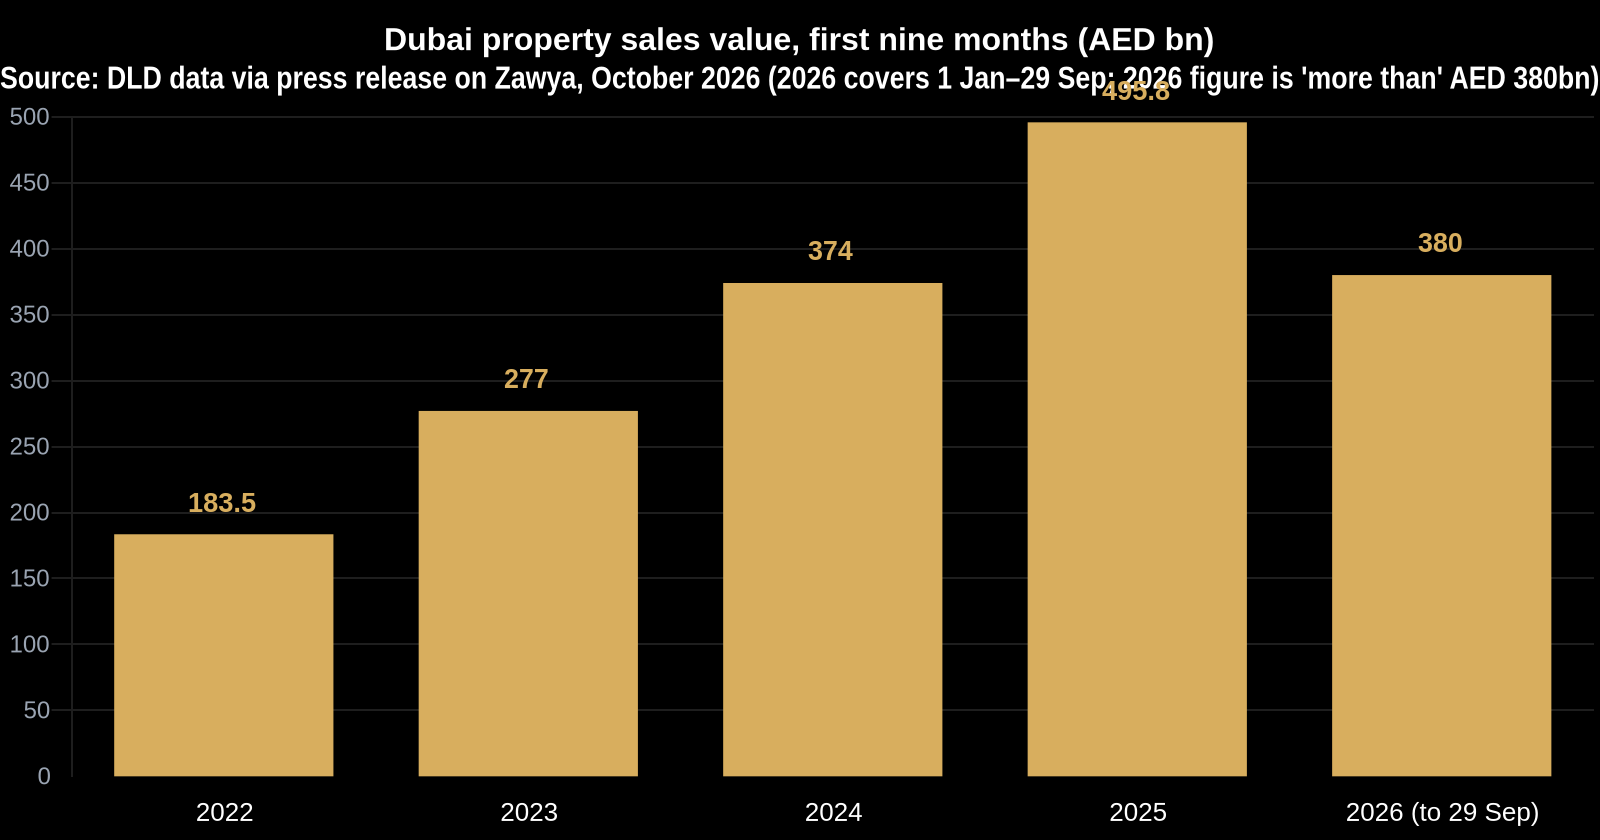
Dubai's property market recorded more than AED 380 billion of sales across over 123,000 transactions between 1 January and 29 September, according to Dubai Land Department data carried in a press release on Zawya. That is the second-highest total for the period on record. On my arithmetic, it is also about 23% below the AED 495.8 billion recorded in the same period of 2025. The third quarter alone came to roughly AED 92.3 billion, against AED 169 billion a year earlier. "Second-highest on record" and "down by close to half in the quarter" both describe the same dataset.
The regional backdrop explains much of the gap. An editor's note to a Khaleej Times report this week refers to US-Iran hostilities since a 14-point MoU expired on 17 August. The IMF now expects the overall GCC economy to contract in 2026 and recover strongly in 2027, provided shipping normalises gradually. Shipping did improve in September: on Kpler's count, 21 LNG cargoes left the Strait of Hormuz, the most in any month since the disruption began. But Kpler also puts LNG transit 80% below February levels.
That is this week's tension. The UAE's economy minister is calling 2027 a "counter-attack year", and Dubai property has held up better than the regional economy. But the recovery case depends on energy flows returning to normal, and the transaction data shows buyers have already slowed down to wait for that. Borrowed money is filling more of the gap: mortgage value rose while sales value fell.
If you're weighing entry points while this market reprices, I can show you where the risk-adjusted opportunities are emerging. Click here to speak with me directly.
Section 01
Dubai Sales Passed AED 380 Billion in Nine Months, About 23% Below 2025, and Most of the Slowdown Came in Q3
Dubai real estate transactions, 1 January–29 September 2026 (DLD data, via press release on Zawya, October 2026)
| Figure | |
|---|---|
| Sales value | AED 380bn+ (2025: AED 495.8bn) |
| Sales transactions | 123,000+ (2025: 157,306) |
| Mortgages | AED 150.6bn, +14% (2025: AED 132.21bn) |
| Gifts | AED 43.5bn, +9% |
| Total (sales, mortgages, gifts) | AED 575bn+ across 159,908 (2025: AED 668bn across 202,111) |
| Q3 sales | ~AED 92.3bn across 37,124 (Q3 2025: AED 169bn across 59,044) |
| September sales | AED 28.7bn across 11,063 |
These are DLD figures, but they reach me through a press release issued by a brokerage, not through the DLD's own dataset. I am using only the numbers and none of the release's forward-looking commentary. The data also runs to 29 September, so it is a day short of a full nine months.
The detail matters more than the headline. Subtracting Q3 from the nine-month totals gives first-half sales of roughly AED 287.7 billion in 2026 against roughly AED 326.8 billion in 2025. That puts the first half about 12% behind last year, followed by a third quarter about 45% behind. Q3 transaction numbers fell by about 37%, from 59,044 to 37,124. Measured over a longer run, 2026 is still slightly above 2024's nine-month total of AED 374 billion and roughly double 2022's AED 183.5 billion.
The monthly picture points the same way. As I noted in the September 19 edition, a separate brokerage analysis of DLD figures put May sales at 9,536, a three-year low, with volumes recovering to 13,116 in July and easing back to 11,087 in August. This week's September figure of 11,063 transactions is almost exactly August's level. The two analyses come from different sources, so I would not join them into one series. Taken together, though, they suggest the rebound from May has levelled off rather than continued.
On my arithmetic, the average Q3 sale was about AED 2.49 million, against about AED 2.86 million a year earlier. That is mostly a change in the mix of what sold, not evidence of falling prices, so I would not read it as a price index. If your exit plan assumes 2025's resale pace, rebase it: a third quarter roughly 45% lower by value tells you how much longer it may take to sell at your price.
Section 03
Dubai Office Sales Reached AED 20.16 Billion, With Off-Plan 80% of Value and Business Bay Nearly Half
Dubai office sales, January–September 2026 (Al Masdar Al Akari analysis of DLD data, via Arabian Business)
| Figure | |
|---|---|
| Total | AED 20.16bn ($5.49bn), 3,695 transactions |
| Off-plan | AED 16.13bn, 2,363 transactions (~80% of value, ~64% of volume) |
| Ready | AED 4.03bn, 1,332 transactions |
| September | AED 1.85bn, 419 transactions (August: AED 1.14bn, 326) |
| September vs September 2025 | Volume +7.4%, value ~+54% |
| Business Bay | 1,100 transactions, AED 9.9bn+ (~29.8% of volume, ~49% of value) |
Dubai recorded AED 20.16 billion of office sales across 3,695 transactions in the first nine months. The analysis comes from Al Masdar Al Akari, a property media and data outlet working from DLD records, not from one of the international advisory firms. September value rose about 62% on August and about 54% on September 2025.
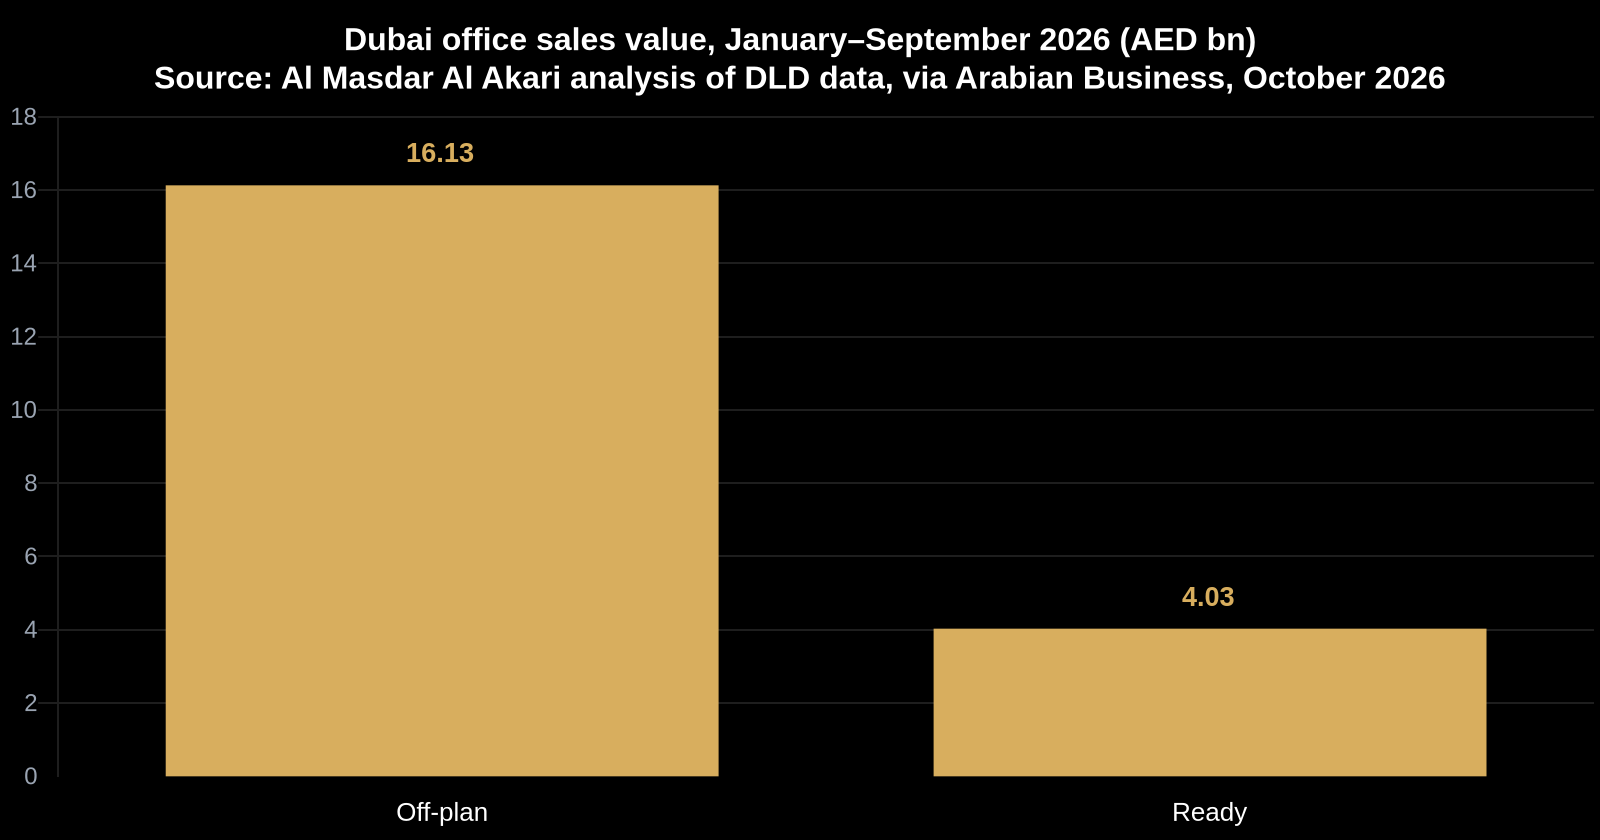
Two things stand out. First, the scale of off-plan. Off-plan office sales in the first half alone came to about AED 13.1 billion, more than the AED 5.48 billion recorded across 1,821 deals from 2019 to 2025 combined. A product that barely existed three years ago is now most of the market. Second, the third quarter cooled here too. Subtracting the first-half figure from the nine-month off-plan total leaves roughly AED 3 billion for Q3, so September's strength followed two quieter months.
On my arithmetic, the average off-plan office deal was about AED 6.8 million and the average ready deal about AED 3.0 million. Business Bay alone took about 49% of value. That means one district, mostly unbuilt, will be competing for tenants in the same handover window. Ready offices made up only AED 4.03 billion of this year's sales, and that is the only part of the market where an investor can check the rent and the tenant before paying.
Explore curated office and retail opportunities at Mitchell's Commercial Real Estate.
Section 04
Hormuz Flows Had Their Best Month Since February, but LNG Transit Was Still Far Below Pre-War Levels
Gulf energy indicators, September–October 2026 (Economy Middle East; The National)
| Figure | |
|---|---|
| LNG cargoes exiting Hormuz, September (Kpler) | 21 (June: 15) |
| LNG cargoes exiting Hormuz, September (S&P Global Energy) | 19 (13 Qatar, 6 UAE) |
| Middle East crude exports, September (Kpler) | 16.328m bpd, highest since February |
| Saudi shipments through Hormuz (preliminary Kpler) | 2.9m bpd in September vs ~1m bpd in August |
| LNG transit vs February (Kpler) | 80% below |
| Brent / WTI | $102.25 / $91.11 |
The two vessel-tracking counts disagree, and I am reporting both. Kpler counted 21 LNG cargoes leaving the Strait in September. S&P Global Energy counted 19. The difference comes from method, and ships that switch off their transponders mean both may undercount. Both show September as the strongest month since the conflict began on 28 February. S&P estimates that October traffic could recover to around 25% of pre-disruption levels if the late-September pace holds. Kpler's separate finding that transit remains 80% below February levels uses a different measure, so I would not combine the two.
The head of Japan's Jera, the world's largest LNG buyer, told Bloomberg TV he expects the disruption to persist. Qatar has extended force majeure (a contractual suspension of delivery obligations) for long-term Asian customers to November and for European customers to December. Spot LNG prices are double their level of a year ago.
Brent settled nearly flat at $102.25 a barrel after briefly falling below $100, and was down nearly 2% on the week. WTI fell 1.9% to $91.11. Some reports described an EU agreement to release stocks. The body of the report says EU countries discussed a French proposal, citing sources, to release 50 million barrels of diesel, with IEA members releasing 50 million barrels of crude. That is not a finalised release. Saudi Arabia's East-West pipeline was shut after Houthi drone attacks on 10 September and only partially reopened on 22 September.
The regional risk premium (the extra return investors demand for holding Gulf assets) has eased, but it has not gone. Treat monthly Hormuz traffic as a leading indicator for Dubai sentiment, and keep in mind that even the optimistic October estimate is only about 25% of pre-disruption traffic.
Section 05
The IMF Expects a GCC Contraction This Year, While the UAE Calls 2027 a "Counter-Attack Year"
GCC finance ministers and central bank governors met IMF Managing Director Kristalina Georgieva in Manama this week, with CBUAE Governor Khaled Mohamed Balama taking part. They called for closer fiscal and monetary coordination and stronger macroprudential frameworks, meaning rules designed to protect the financial system as a whole. Georgieva said exchange-rate pegs had continued to support stability and confidence.
The buffers are substantial. GCC commercial bank assets were above $4 trillion at end-June, up 3.9% from end-2025. Deposits were about $2.45 trillion, up 6%. Central bank net foreign assets of about $829 billion cover about 11 months of imports, and regional inflation was around 2.1% in May. The IMF gave no size for the expected 2026 contraction.
At the Future Hospitality Summit, the UAE's Minister of Economy and Tourism said the country would see a "counter-attack year" in 2027 after slow growth this year. The report cites an IMF forecast of 3.1% UAE real GDP growth but does not say which year it refers to, so I am not attaching one. The UAE has 216,000 hotel keys, of which 10,000 are out of operation for refurbishment, and targets 40 million hotel guests by 2031.
The official view is a deferred recovery, not a cancelled one. If you are buying on the 2027 rebound, make sure your cash reserves can carry you through the rest of a year the IMF expects to be a contraction, rather than relying on the 3.1% figure arriving on schedule.
On Monday, 24-carat gold in Dubai fell to Dh499.75 per gram from Dh516.50 over the weekend, according to Dubai Jewellery Group data. That was a seven-month low. Spot gold dropped 3% to $4,149 an ounce, and analysts pointed to higher Treasury yields, a stronger dollar and oil prices. By Friday, spot gold was at $4,140.80, down more than 3% on the week, and the Federal Reserve was expected to hold rates at its next meeting.
For property investors, the gold price matters less than the reasons behind it. Because the dirham is pegged to the dollar, higher US yields and a firmer dollar feed into UAE funding costs. A Fed expected to hold is not a Fed expected to cut. When even gold is selling off on rising yields, assume the cost of borrowing stays elevated through your next refinancing. Do not count on relief at the next Fed meeting, which is expected to hold rates.
Still reading
Need expert help on this subject?
Section 07
Knight Frank Counts 175 Branded Residence Schemes in Dubai, More Than Twice Miami, With 107 Still in the Pipeline
Knight Frank's Residence Report 2026/27, published on 28 September, names Dubai the world's largest city market for branded residences, with 175 live and pipeline schemes: 68 live and 107 in the pipeline. Miami has 73, New York 38, Phuket 35 and London 30. Abu Dhabi ranks eighth with 24 schemes and Al Marjan Island ninth with 23, all of them in the pipeline. Across the three UAE locations, 149 schemes are in the pipeline, and UAE projects make up 19% of the global branded residence pipeline.
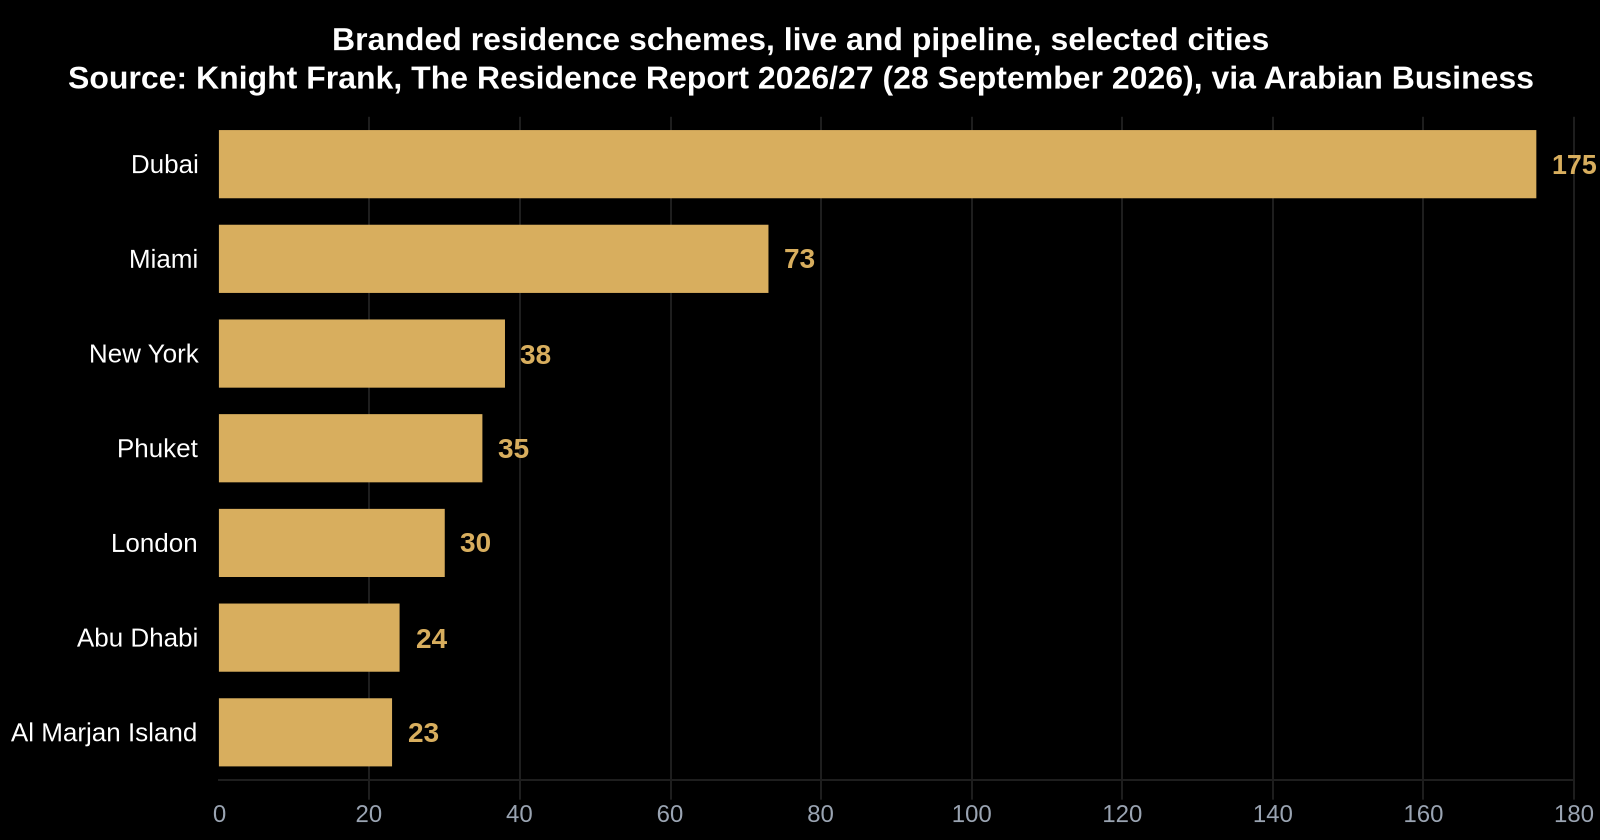
Two figures need care. On my arithmetic, about 61% of Dubai's schemes are still in the pipeline, not yet delivered. And 42% of Dubai's schemes carry non-hospitality brands, such as fashion, automotive or design names, rather than hotel operators. Knight Frank expects the global total to rise from 903 schemes at end-2025 to about 1,088 during 2026.
The premium for a brand rests partly on scarcity, and Dubai now has more schemes than any other city. Before you pay that premium, look at the operator behind the brand and at how many of the 107 pipeline schemes will hand over in your area in the same window.
Section 08
Regional Sovereign Dealmaking Hit a Three-Year Low, While One Developer Raised Cash for Distressed Assets
Global SWF's Mena Playbook, reported by AGBI, says regional sovereign investors deployed more than $100 billion across nearly 250 transactions in the first nine months, about 40% of global sovereign dealmaking. That is a three-year low for the region, both in dollars and as a share of the global total. The full-year forecast of $136 billion is an extrapolation of the current pace, against $176 billion last year. Only 20% went to domestic economies, while the US took nearly half. Withdrawals from funds such as KIA and QIA could produce the first year-on-year fall in combined assets under management in more than a decade. The region in this report includes North Africa, Iran and Iraq, not only the Gulf.
Separately, Dar Global drew $151 million from a shareholder loan in the six months to June, up from $36 million a year earlier, and its debt to Dar Al Arkan rose by half to $428 million. With roughly $230 million of free cash, the company says it could pursue "opportunistic initiatives" including distressed assets, land and refurbishment. Nearly three-quarters of its $850 million cash pile sits in escrow, meaning it is ring-fenced for construction and cannot be spent freely. This is the company's own account, and its stated interests are in London and Saudi Arabia rather than Dubai.
Patient regional capital is investing abroad, and well-funded developers are preparing to buy assets from forced sellers. Neither trend is yet visible in Dubai's data. But if well-capitalised buyers are setting aside about $230 million at a time for distressed opportunities, private investors with cash and patience should be ready too.
Abu Dhabi's Department of Municipalities and Transport approved 43.6 million sq m of gross floor area in the first half, up 40% year on year, an increase of 12.46 million sq m. That is approved capacity, not built or delivered space. New building permits rose only 0.9% to 4,730, which suggests the pipeline is being approved faster than construction is starting.
Etihad Rail's Dubai–Abu Dhabi passenger service started on 30 September. After what Etihad Rail called "exceptional early demand", it added six weekend services and more than 2,000 tickets on top of the initial 10 trains. Al Yalayis Station, linked to the Metro Red Line by a 400-metre elevated walkway, will become an interchange with the Gold Line when that opens in 2032. Any effect on prices has not yet shown up in the data. The rail link makes the two emirates one commuting market, while the 0.9% growth in permits suggests the 43.6 million sq m of approvals will reach the market slowly. Investors comparing locations along the line should price them as competitors over the long term, not as separate markets.
In closing
Final View for Dubai Property Investors
This week's data tells me Dubai is in a slower but orderly market, not a broken one. Sales are still above every year except 2025, but the third quarter was roughly 45% below last year's by value, and September matched August rather than improving on it. Mortgages, not cash, are taking a larger share of activity, and US yields give no sign of easing.
Here is what I would do differently. Use 2024, not 2025, as your baseline for how quickly you can sell. Run your debt service on the assumption that rates stay where they are. In commercial property, favour ready offices whose rent and tenant you can check over off-plan stock concentrated in Business Bay. In branded residences, check the handover pipeline before paying a brand premium. Track monthly Hormuz traffic alongside DLD data, because the official recovery case for 2027 rests on it. And keep cash in reserve: the IMF expects a contraction this year, and better-funded buyers are already preparing for distressed sales. This is a period for careful selection and patience.
Next step
Let’s Talk
If you’d like to unpack where the most resilient opportunities are emerging — in stabilised residential areas or income-generating commercial zones — I’d be happy to share a focused, data-driven shortlist based on your investment goals.
📞 No pressure, no sales pitch—just a focused, informed conversation about your investment goals.
Published 3 October 2026 by Stephen James Mitchell MBA. Market figures quoted reflect the data available at that date.