Dubai closed 2025 with one of the strongest transactional years on record, yet the December Property Monitor data signals a market that is transitioning from rapid expansion to more measured, fundamentals-driven behaviour.
Pricing has moderated slightly, off-plan continues to dominate activity, and supply growth has reached unprecedented levels.
For investors, these shifts do not indicate a reversal in the long-term trend, but rather a recalibration that defines the next phase of the cycle.
Let’s take a closer look at the December numbers and the trends shaping the market right now.
If you’re assessing where to allocate capital within Dubai/UAE real estate, I can share a targeted shortlist of high-performing options.Click here to speak with me directly.
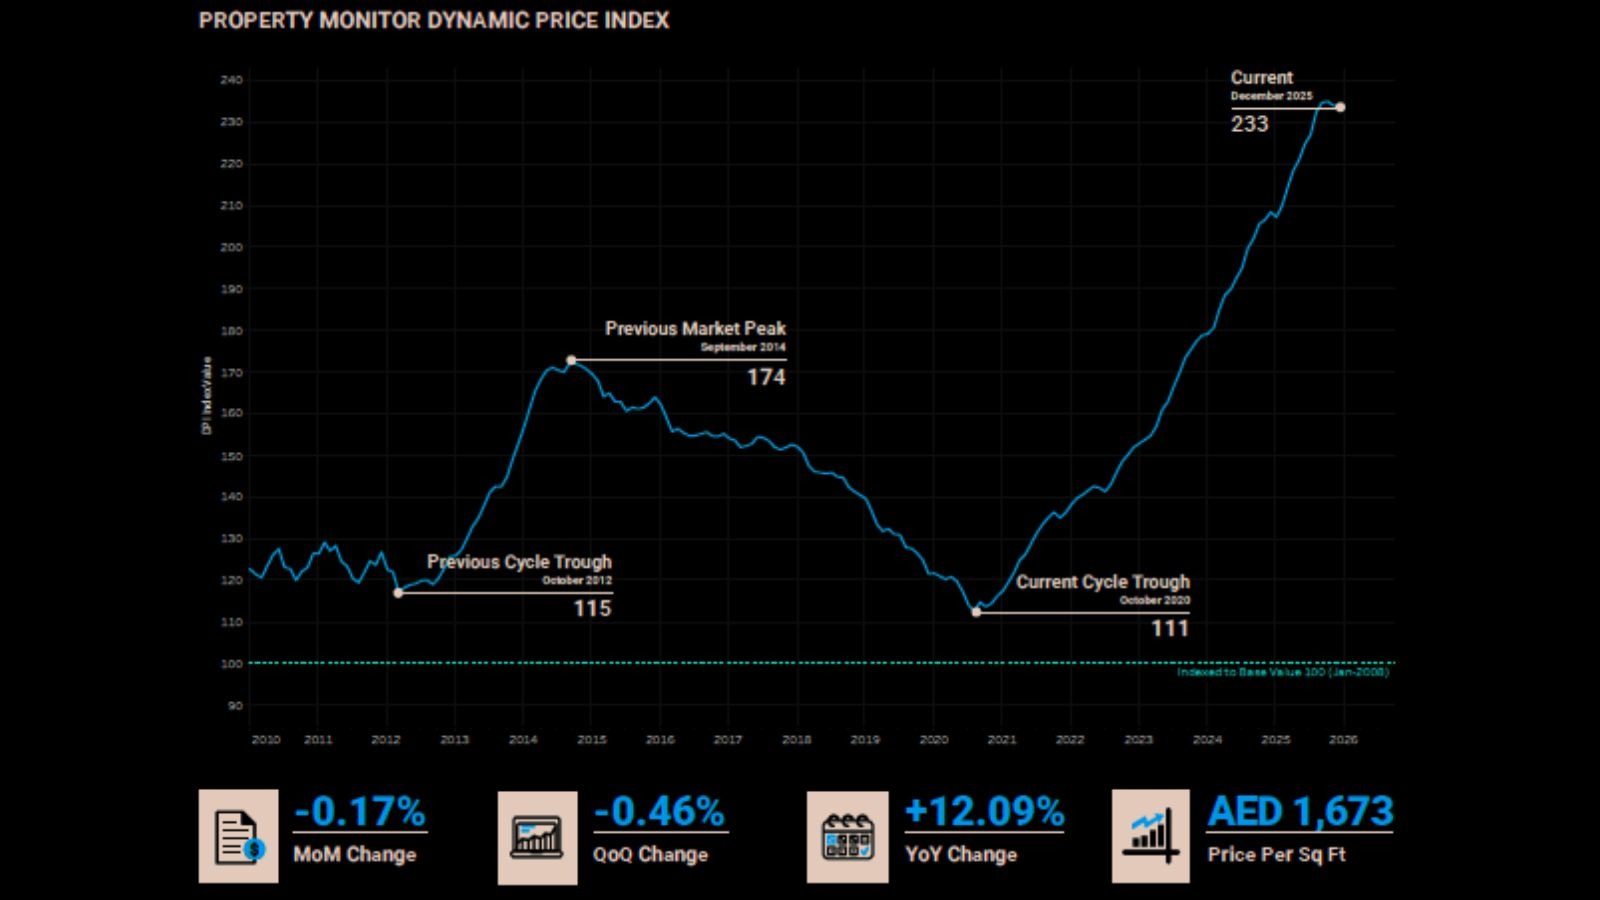
The Property Monitor Dynamic Price Index (DPI) slipped 0.17% in December, following a 0.42% decrease in November.
These are marginal adjustments relative to the broader historical trend.
Imgae Credit: Property Monitor
Prices now sit:
- 105.4% above the October 2020 trough
- 35.7% above the 2014 peak
- At AED 1,673 per sq ft, still one of the highest levels on record
- Up 12.1% year-on-year, marking 62 consecutive months of annual growth
This pattern points to consolidation rather than deterioration. Monthly pricing is responding to increased sensitivity as transactional volumes stabilise at historically high levels.
The market is no longer in a rapid upswing; it is normalising around a higher base.
Consideration for investors:Moderate month-on-month dips suggest opportunities for disciplined buyers without signalling distress. Price discovery is becoming sharper, and well-priced assets in quality communities are still clearing efficiently.
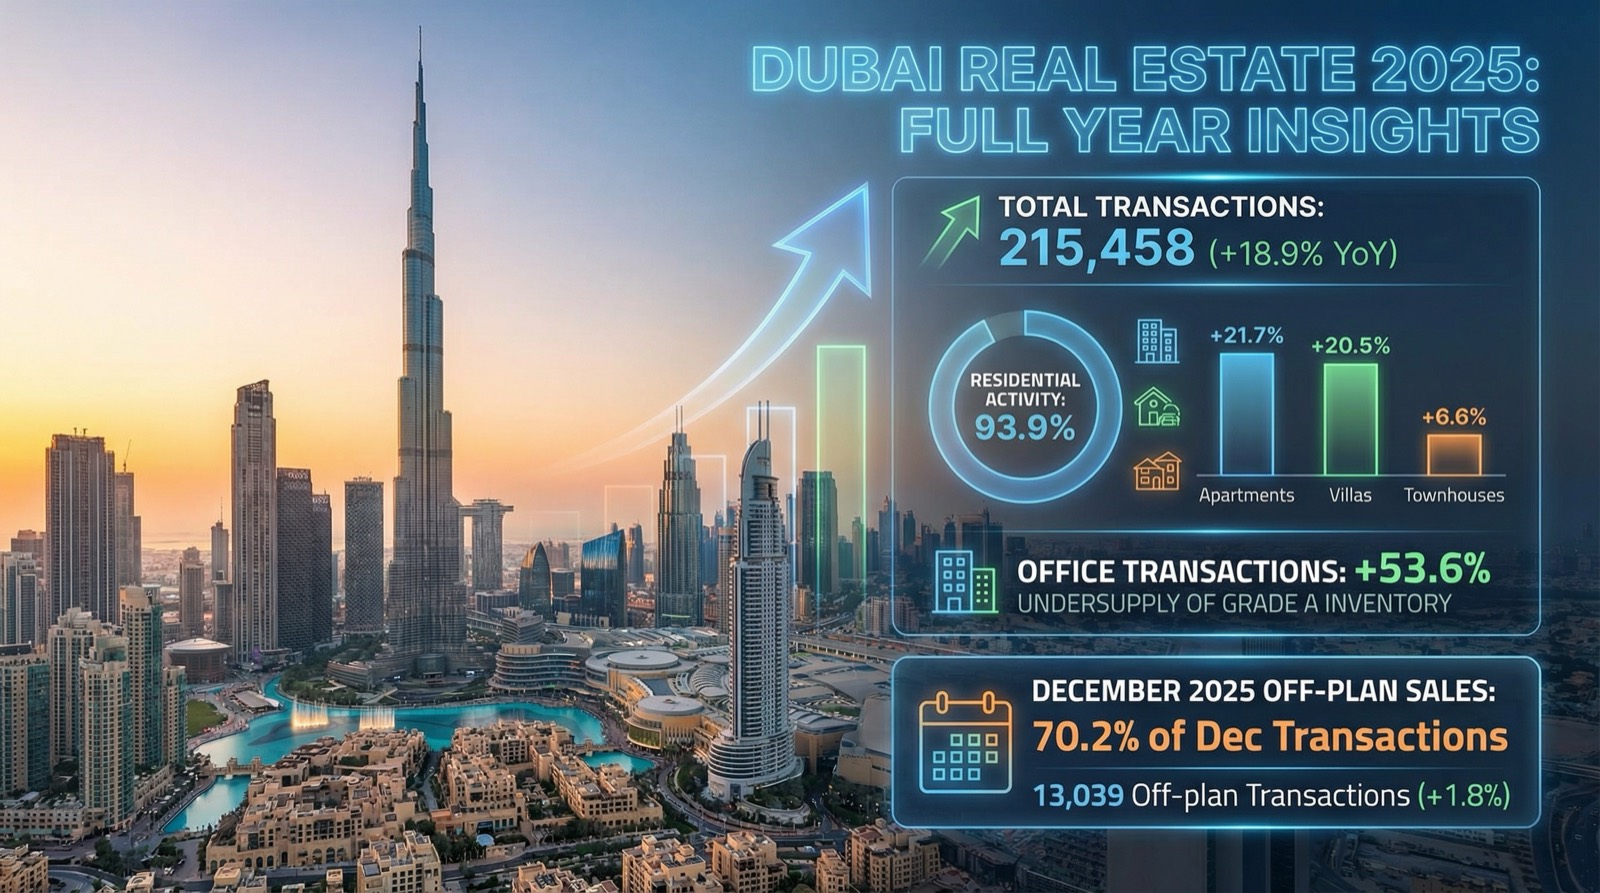
Dubai recorded 18,575 transactions, down only 2.1% from November. Even with this slight pullback, December 2025 closed as the most active December ever recorded.
For the full year:
- 215,458 transactions (+18.9% YoY)
- 93.9% of activity from residential assets
- Apartment transactions +21.7%, villas +20.5%, townhouses +6.6%
- Office transactions rose 53.6%, underscoring continued undersupply of Grade A inventory
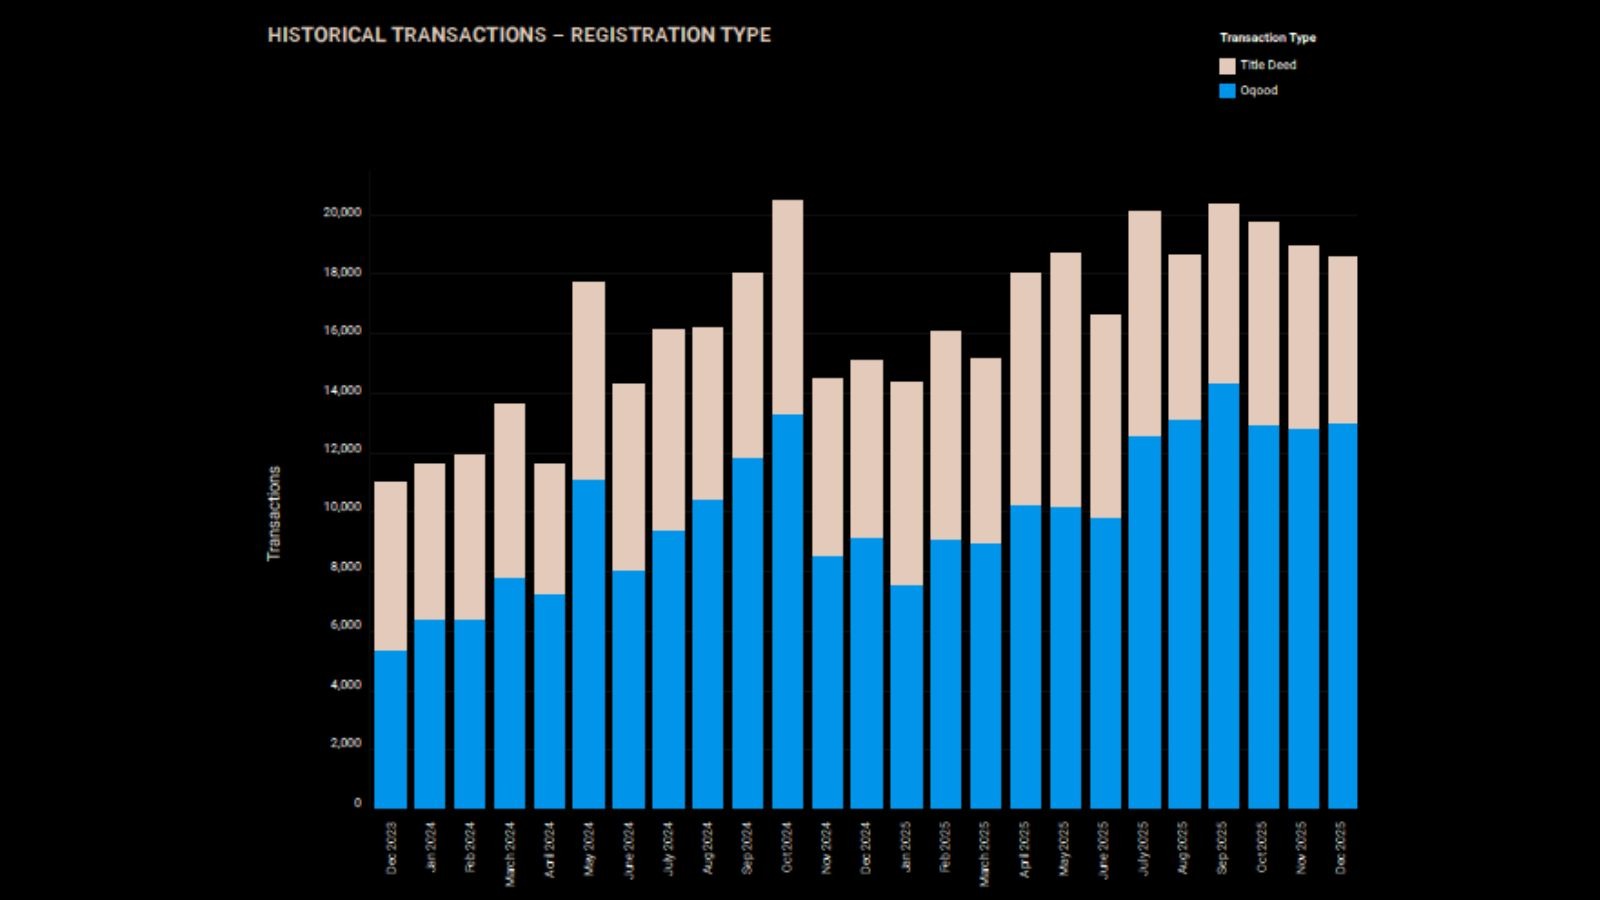
Imgae Credit: Property Monitor
The only month in 2025 that did not break its historical monthly record was October.
Strategic note for investors: Demand remains broad-based, resilient, and supported by long-term fundamentals. Despite higher prices, transaction velocity demonstrates confidence in Dubai’s economic outlook and sustained investor appetite.
Explore curated office and retail opportunities at Mitchell’s Commercial Realty.
December saw 37 new project launches introducing 10,029 units worth AED 30.2 billion.
The annual figures for 2025 highlight the scale of activity:
- 648 launches (+40% vs 2024)
- 167,000+ units added to the pipeline
- AED 463 billion in total launch value
- Equivalent to one new project every 13.5 hours
Apartments represented 88.8% of all new supply, though villas and townhouses carried a disproportionately higher share of value due to price positioning and continued demand for low-density formats.
Investor takeaway: The scale of supply is significant. The next phase of the cycle will depend less on launch velocity and more on absorption. Not all submarkets will absorb equally; projects with strong differentiation, competitive pricing, and credible developers will outperform.
December mortgage activity fell 19.8%, following a decline in November.
Key details include:
- 3,612 new mortgages
- Average mortgage size: AED 1.83M
- Average LTV: 73.4%
- Purchase mortgages: 51.7% share
- Refinancing/equity release: 40.4%
- Bulk mortgages: 7.9%, clustered in two developments
Importantly, mortgage demand for villas and townhouses remained stable, while most of the decline came from softer apartment volumes.
Strategic note for investors: The lending environment is steady. The dip in mortgage issuance does not indicate sentiment deterioration; it reflects transaction composition shifting toward off-plan, which is typically not mortgage-driven until completion.
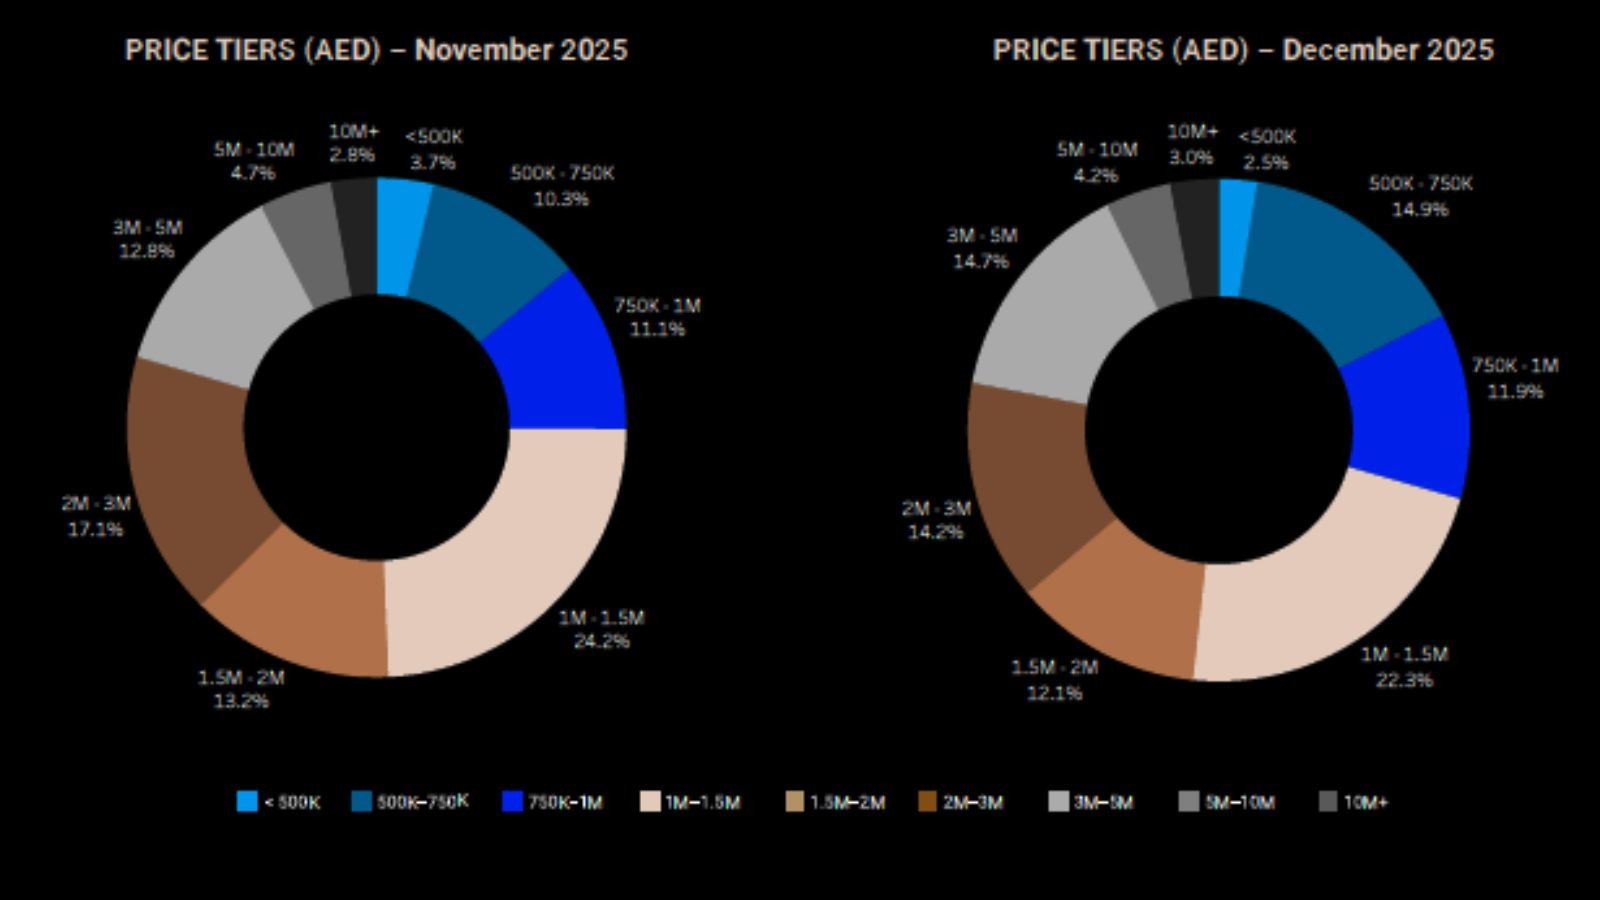
Imgae Credit: Property Monitor
The AED 500K–750K segment grew the fastest in December (+4.7%).
This movement was driven by mid-market launches in:
- Majan (Binghatti Titania, Binghatti Vintage)
- Liwan (Empire Lakeviews)
The AED 3M–5M tier also grew (+1.9%), supported by:
- Ultra-luxury townhouse launches at Equiterra 1, Equiterra 2, and Equestra
- High-category units at Ellington Sands in Dubai Islands
Meanwhile, the AED 2M–3M segment saw the sharpest contraction (−2.9%).
Market composition for December:
- Under AED 1M: 29.5% (up 4.4%)
- AED 1M–3M: 48.6% (down 5.9%)
- Above AED 3M: 21.9% (up 1.5%)
What this means for investors: Demand is polarising into two bands:
- Entry-level and mid-market apartments, driven by affordability and launch volumes
- Upper-mid and luxury segments, where end-user demand and differentiated product offerings remain strong
The traditional mid-market is experiencing adjustments due to rising supply and competition from developer stock.
Initial Off-Plan Sales (Top 3):
Majan:
- 11.6% of initial sales
- Driven by Binghatti Vintage (883) and Titania (447)
Jumeirah Village Circle (JVC):
- 8.4% market share
- Binghatti Amberhall led with 240 sales
Grand Polo Club & Resort:
- 7.2% market share
- Equiterra 1 (405), Equiterra 2 (285), Equestra (221)
Resale Activity (Top 3):
- JVC: 8.2%
- Business Bay: 6.7%
- Dubai Marina: 4.7%
Strategic note for investors:Majan, JVC, Dubai Islands, and Grand Polo Club & Resort continue to consolidate their positions as growth corridors, supported by active launches, improved infrastructure, and value-driven pricing.
Still reading
Need expert help on this subject?
The recurring theme across the December data is consolidation, not contraction:
- Price movements are modest
- Transaction volumes remain historically elevated
- Buyers are more selective
- Resale activity is shrinking as investors extend holding horizons
- Developer launches are increasing the breadth of supply
The market is now defined by two distinct structures:
A. Off-Plan Market
Driven by developer launch strategies, payment plans, and marketing intensity. This segment has become the dominant engine of transaction volume.
B. Completed Market
Defined by tight inventory, price sensitivity, and more rational buyer assessment. Villas and townhouses remain supply constrained, while apartment resale stock competes more directly with aggressively priced off-plan inventory.
Strategic note for investors:Understanding which side of the market you want exposure to — and why — is critical for 2026 positioning.
Source: Property Monitor
The December report provides several practical insights that can guide investment decisions in 2026. Below are structured recommendations.
1. Align Strategy With the Market's Two-Track Structure
Off-Plan Strategy
Best suited for:
- Investors seeking payment plan-driven leverage
- Long-term appreciation in emerging corridors
- Developer-backed liquidity and strong future resale demand
Focus on:
- Developers with consistent delivery
- Projects in growth zones (Majan, JVC, Dubai Islands, Dubai South)
- Early-phase launches with competitive pricing
Completed Market Strategy
Best suited for:
- Yield-driven investors
- Buyers seeking stable occupation or ready rental income
- Investors looking for constrained villa/townhouse supply
Focus on:
- Established communities
- Quality-built inventory
- Assets priced below recent transactional benchmarks
2. Treat Supply Growth as a Selectivity Filter
The unprecedented pipeline means investors should assess:
- Submarket saturation
- Delivery timelines
- Competing stock within a 1–3 km radius
- Developer track record for retention and resale support
Areas with rapid launch frequency will require careful monitoring of absorption rates.
3. Use Price Tier Movements to Identify Opportunity Bands
Growth in lower and upper-mid segments suggests two opportunities:
- Affordable and mid-market apartments in high-density master plans where entry pricing is competitive.
- Premium townhouses and high-spec apartments in branded or low-density communities supported by end-user demand.
Mid-market AED 1M–3M properties require sharper price discipline due to rising competition.
4. Factor Mortgage Dynamics Into Timing Decisions
As mortgage activity slowed due to mix, not sentiment, buyers relying on financing may benefit from:
- Structuring approvals early
- Taking advantage of stable LTVs
- Targeting completed stock where valuations remain firm
End-users especially should consider the timing of their purchase relative to off-plan handover cycles.
5. Prioritise Master Plans With Consistent Transaction Depth
Majan, JVC, Business Bay, Dubai Islands, and Grand Polo Club & Resort demonstrate strong absorption.
These areas benefit from:
- Active developer engagement
- Continual infrastructure improvements
- A balance of affordability and product diversity
Sustained liquidity enhances exit optionality.
6. Avoid Short-Term Speculative Assumptions
Given lower flipping activity and longer holding periods:
- Base projections on rental yield sustainability
- Focus on long-term demographic momentum
- Assess developer inventory competition before purchasing
The phase of “easy resale gains” in early construction cycles has largely passed.
The December 2025 Property Monitor report captures a market transitioning into a more mature and balanced stage. Prices have softened modestly, transaction levels remain historically high, and launches have expanded the supply universe at record scale.
Two markets are now clearly visible: a developer-driven off-plan ecosystem and a more selective completed-property segment with tight villa supply and moderated apartment resales.
For investors, the opportunity lies in understanding these dynamics and positioning around communities, developers, and price bands that show consistent absorption and realistic pricing.
As Dubai enters 2026, the environment rewards thoughtful engagement, disciplined underwriting, and clarity on investment horizons.
Next step
Let’s Talk
If you’d like to unpack where the most resilient opportunities are emerging — in stabilised residential areas or income-generating commercial zones — I’m happy to share a focused, data-driven shortlist based on your investment goals.
📞 No pressure, no sales pitch—just a focused, informed conversation about your investment goals. Let’s talk.
Published 29 January 2026 by Stephen James Mitchell MBA. Market figures quoted reflect the data available at that date.