The US Federal Reserve raised its benchmark rate by 25 basis points to 3.75%–4.00% this week, and the Central Bank of the UAE lifted the base rate on its overnight deposit facility by the same margin to 3.9%. Because the dirham is pegged to the dollar, that sequence is automatic rather than discretionary. It is also, per Arabian Business, the first hike since 2023 — which means every leveraged investor who built a model in the past two years built it on a falling or flat rate assumption.
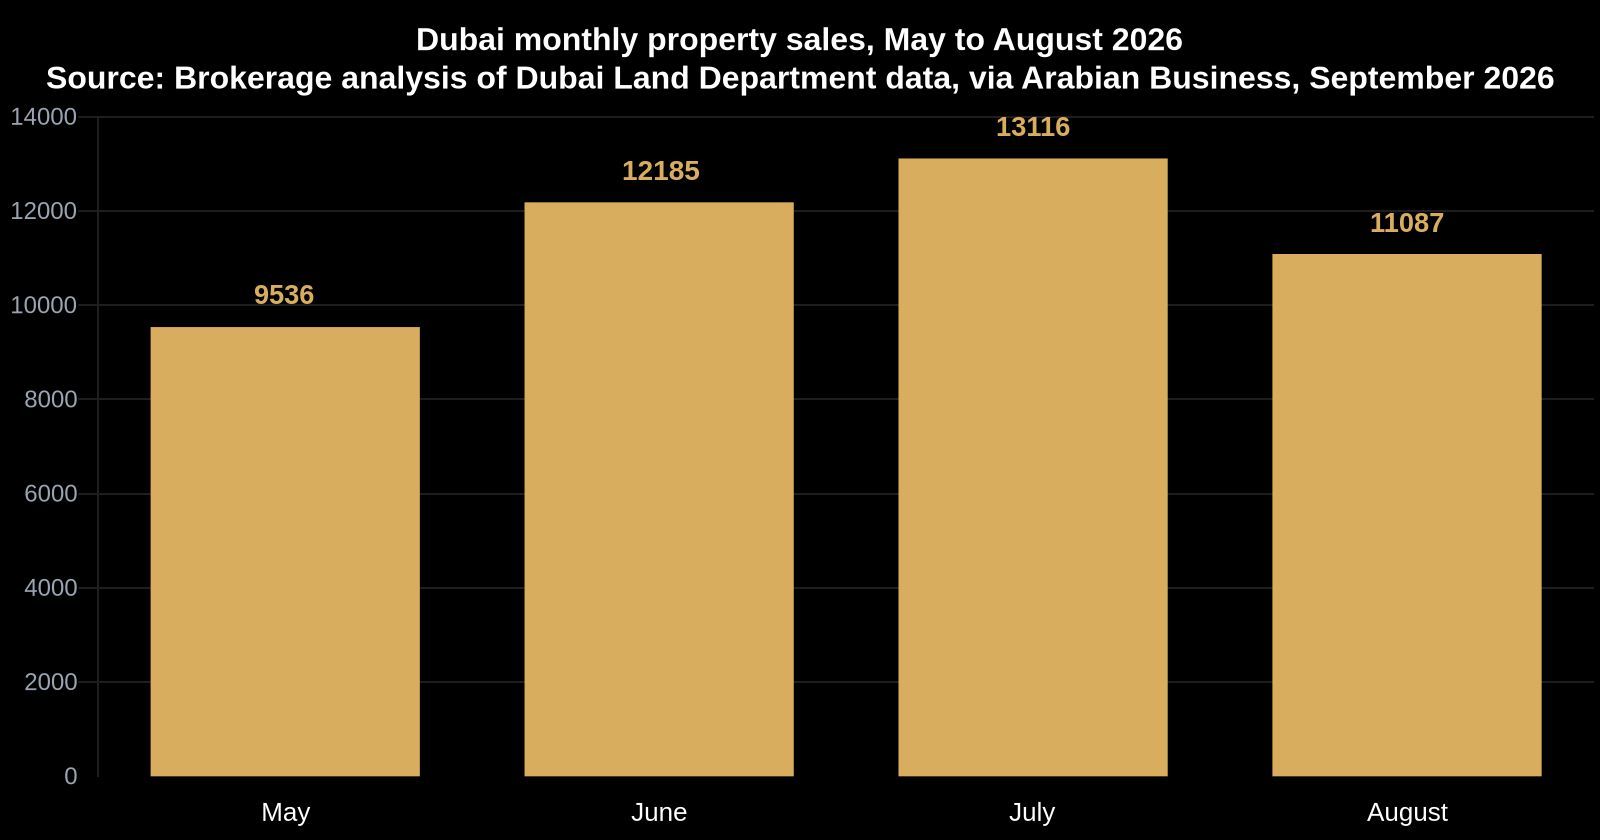
The transaction data moved the other way. A brokerage analysis of Dubai Land Department figures put May sales at 9,536, the lowest monthly total in three years, before volumes rose 28% month-on-month to 12,185 in June and reached 13,116 in July — a 38% recovery from the May low. August eased back to 11,087. Price per square foot was higher year-on-year in 81% of tracked communities, with a median increase of 6.6%.
So the week's central tension is this: volumes are recovering into a rising cost of money, and between 71% and 76% of those monthly sales were off-plan — purchases that will complete years after the rate at which they were underwritten has changed. That gap between when a decision is priced and when it is delivered runs through almost every story below.
If you're weighing entry points while this market reprices, I can show you where the risk-adjusted opportunities are emerging. Click here to speak with me directly.
Section 01
The Fed's 25bps Move Passed Straight Through to a 3.9% UAE Base Rate, and Most of the GCC Followed
Policy rates after this week's moves (Arabian Business, September 2026)
| Rate | |
|---|---|
| US Federal Reserve benchmark | 3.75%–4.00%, +25bps |
| UAE overnight deposit facility base rate | 3.9%, +25bps |
| Saudi Arabia repo / reverse repo | 4.50% / 4.00%, both +25bps |
| Oman repo rate | 4.5%, +25bps |
| Qatar and Bahrain key rates | +25bps (resulting rates not published) |
| Kuwait | Unchanged |
Saudi Arabia, Qatar, Bahrain and Oman all followed the Fed. The Central Bank of Kuwait, which manages against a currency basket rather than a straight dollar peg, left rates unchanged, citing "the soundness and strength of the monetary and financial stability" in the country.
Arabian Business's accompanying analysis makes the general point without quantifying it: higher borrowing costs for corporate borrowers and property buyers, mid-market buyers facing tightening budgets while cash buyers are less affected, higher US Treasury yields raising the cost of Gulf sovereign and corporate eurobond issuance, and banks seeing near-term margin expansion before deposit costs catch up. No specific UAE mortgage spread or bank repricing figure was published, so treat that piece as context rather than data.
Twenty-five basis points is not, on its own, a portfolio event. On AED 3 million of variable-rate debt it is roughly AED 7,500 a year before compounding. The point is directional: an investor holding variable-rate exposure should re-run debt service at the new base rate now, and should assume in stress-testing that this is the first move of a series rather than the last. If your acquisition case only works at the rate you were quoted in 2025, it is no longer a case.
Section 02
Dubai Volumes Recovered 38% From May's Three-Year Low, but Up to 76% of Deals Were Off-Plan
The same brokerage analysis of DLD data records over 40,000 new and renewed tenancy contracts in June, described as the highest monthly figure recorded, with average rents up 3.1% year-on-year and Jumeirah Islands rental growth at 25%. On capital values, Palm Jumeirah Garden Homes villas were up 37% year-on-year and Al Jaddaf apartments up 35.5%. Off-plan villa and townhouse sales rose 27% year-on-year in Q2 with the value of those transactions up 83%, and luxury off-plan sales above AED 15 million rose 12% year-on-year in August.
Two qualifications matter. First, this is a brokerage-commissioned analysis of government data, not an independent government or advisory-firm release — I am using the DLD-derived numbers and disclosing the origin, and I would weight it below a first-party DLD or Cavendish Maxwell publication. Second, the same source expects approximately 74,100 homes to complete in Dubai in 2026 and as many as 160,700 units in 2027. Dubai has consistently delivered below its announced pipeline, so read those as ceilings.
A 38% bounce off a three-year low is a recovery in activity, not necessarily in pricing power, and August's retreat to 11,087 says the trend is not yet established. With off-plan at up to three-quarters of volume and a 2027 completion ceiling above 160,000 units, the binding question for a buyer today is not entry price but delivery date — who else hands over on your street in the same twelve months you do.
Dubai Holding Real Estate and ADCB announced a bespoke off-plan financing partnership under which, at Palm Jebel Ali, The Acres and Nad Al Sheba Gardens, eligible buyers can access financing once 50% of the property value is paid to the developer, irrespective of construction progress. Pre-approvals are valid for up to 18 months, with pricing from 3.49% per annum fixed for three years and waived processing and valuation fees. Buyers in other Nakheel, Meraas and Dubai Properties communities can access ADCB off-plan financing at prescribed construction milestones.
This was distributed as a company statement rather than independent reporting, and the language is the developer's and the bank's. I am reporting the mechanics, not endorsing the pricing. Note also the contrast with the section above: a three-year fixed rate of 3.49% is being marketed in the same week the UAE base rate moved to 3.9%.
Construction commitment continued alongside it. Nakheel awarded a main contract worth more than AED 800 million ($218 million) to Metac General Contracting for phases one and three of Bay Grove Residences on Dubai Islands — 537 dwellings across seven buildings, with handover planned for 2028. The full community will run to 1,154 homes across 15 buildings, with the remaining 617 units still in planning. In April, Nakheel awarded a separate AED 527 million infrastructure contract for Island B.
When a bank will lend against an off-plan unit at 50% paid regardless of construction progress, it is taking a view on the developer's covenant, not the building's. That is a useful third-party signal for buyers — but it also means the buyer's risk shifts from payment-plan flexibility to fixed debt service on an asset that produces no income until 2028 or later. Model the void.
Dubai retail, H1 2026 (Cavendish Maxwell)
| Data | |
|---|---|
| Sales value | AED 3.8bn ($1.03bn), +177% YoY |
| Number of sales | 850, +56% YoY |
| Average transaction value | AED 4.4m ($1.2m), +77% YoY |
| Off-plan share of transactions / value | ~60% / ~70% |
| Retail rents | ~+4.5% YoY (quarterly rents −1%) |
| Retail rental contracts signed | ~33,000; new contracts −26% YoY |
| Flagship mall occupancy | ~98% |
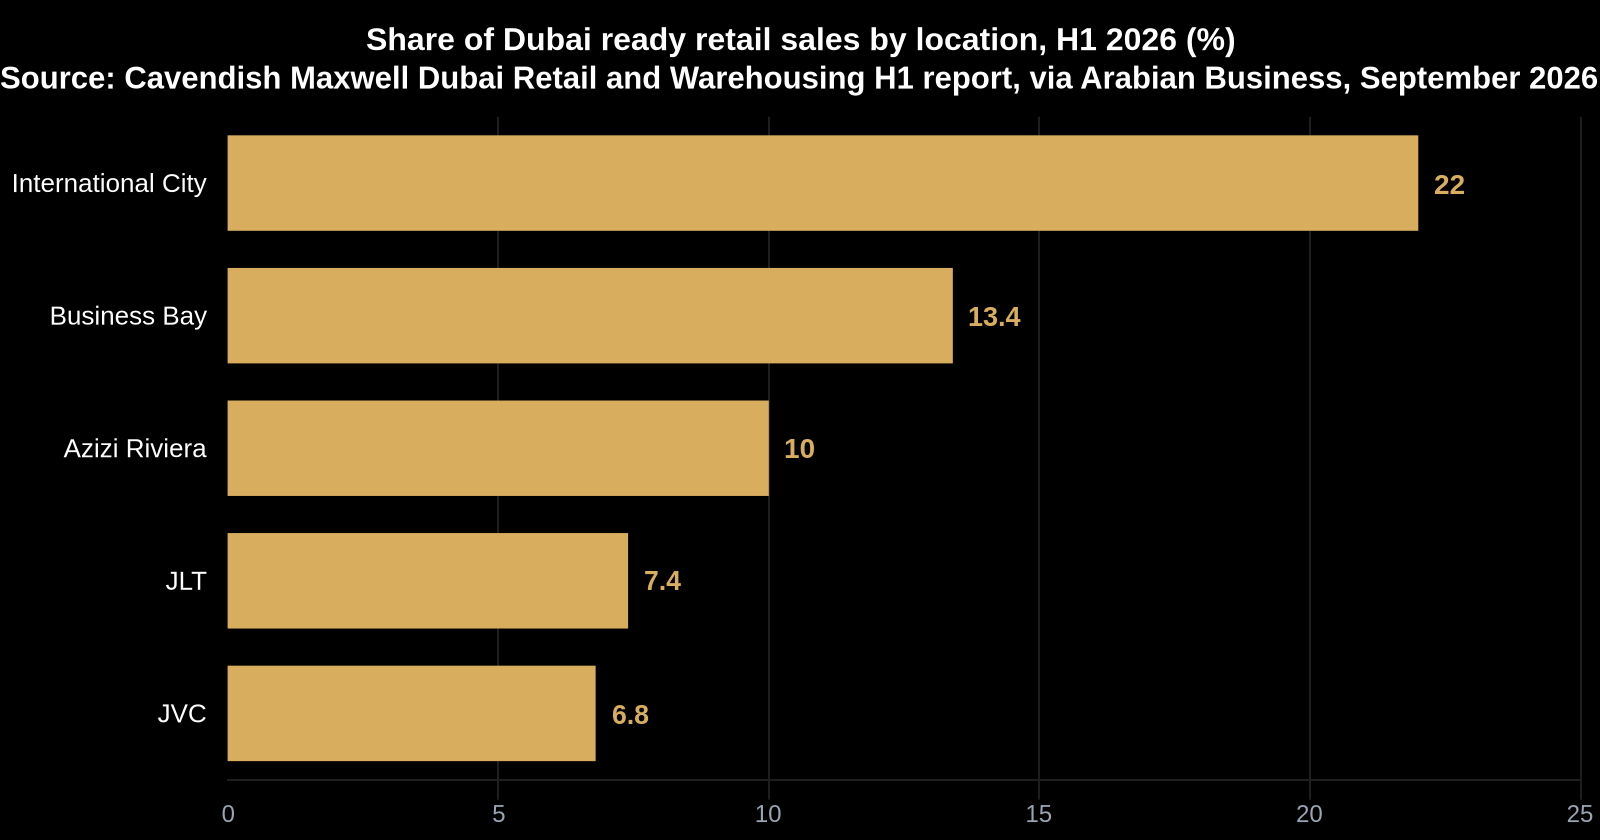
Cavendish Maxwell's Dubai Retail and Warehousing H1 performance report is the strongest independent data of the week, and it points somewhere most residential-focused investors are not looking. Sales values rose 177% year-on-year to AED 3.8 billion across 850 transactions, up 56%. Off-plan led the locations: JVC took more than 12% of off-plan transactions, Majan 10%, Dubai South 9.8%, Motor City 8.6% and Sobha Central 7.6%. Among ready retail, International City accounted for 22% of sales, Business Bay 13.4%, Azizi Riviera 10%, JLT 7.4% and JVC 6.8%. Q2 sales fell 25% against Q1 but were more than 60% above Q2 2025.
The leasing data is more sober than the capital data: new rental contracts were down 26% year-on-year and total contracts down 6%, while renewals rose 1.5%. That combination — investors buying hard, occupiers renewing rather than expanding — is how a strata retail market builds vacancy risk two years out. If you are buying retail units off-plan in JVC or Dubai South, underwrite the rent you can actually sign in 2028, not the guaranteed-return figure in the launch brochure.
Explore curated office and retail opportunities at Mitchell's Commercial Real Estate.
Property Finder's H1 2026 data records the headline of the week: average retail sale prices on Al Marjan Island in Ras Al Khaimah rose 348% year-on-year to AED 19.7 million from AED 4.4 million, with RAK Central up 254% to AED 11.9 million and Al Hamra Village up 44%. Quarter-on-quarter, both of the leading pockets fell — Al Marjan down 4.4% and RAK Central down 33.8% from Q1 to Q2. That reversal inside the same dataset is the discipline check on the annual number. This is portal-sourced data from a listings platform with a commercial interest in transaction flow, not an advisory-firm valuation series; I would not underwrite against it alone.
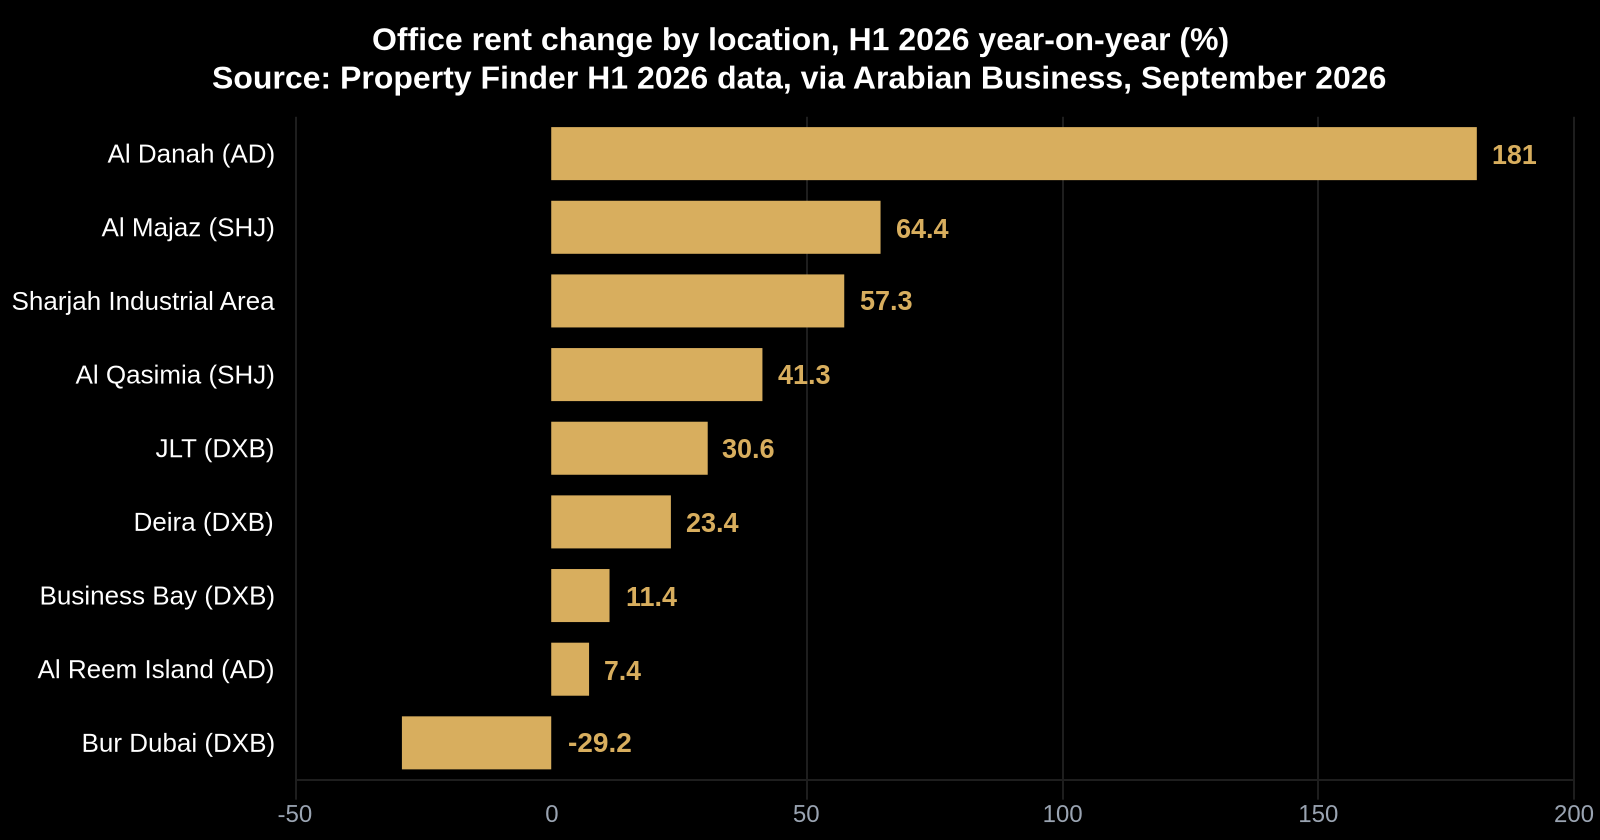
Rental movements were broad but uneven. In Dubai, Deira retail rents rose 61.5% to AED 643,855 and JLT office rents 30.6% to AED 475,870, while Bur Dubai office rents fell 29.2%. In Abu Dhabi, Al Danah office rents rose 181% to AED 523,434 while Mussafah retail fell 54.3%. In Sharjah, Al Majaz office rents rose 64.4% and Sharjah Industrial Area retail fell 30.1%.
Sharjah's own market data is more consistent. Trading value reached $8.03 billion (AED 29.5 billion) in H1 2026, up 9.3% year-on-year, across 59,460 transactions (+23.7%), with sales of 16,426 and mortgage activity of 2,590 transactions worth AED 7.6 billion. August alone produced AED 4.6 billion across 9,139 deals. The emirate's Executive Council reviewed a draft lost-and-abandoned-property law on 15 September and referred it to the Consultative Council; no implementation date or penalties have been published. Worth saying plainly: this is a draft under review, not a new law in force, and the reporting headline runs ahead of that.
Both the RAK and the Sharjah stories are about pockets. A 348% annual print that falls 4.4% within the same half-year is a thin market repricing on very few comparables. Treat individual-asset diligence — tenant, lease term, catchment — as doing all the work here, because the index will not.
The DLD updated its service page on 8 September 2026 to confirm that mortgaged property qualifies for its 10-year investor residency service, subject to a bank no-objection letter showing the amount paid and outstanding balance, with evidence of AED 2 million ($544,589) paid against the mortgaged property. Federal ICP guidance published in August also permits financed property via approved local bank loans, requiring a total property value of at least AED 2 million fully registered in the investor's name, and allows qualifying off-plan units of at least AED 2 million from DLD-approved local developers. GDRFA Dubai requires property totalling at least AED 2 million, with joint owners needing an individual share at that level. Applicants must be inside the UAE when applying; processing runs seven to 10 business days, and published charges total about AED 9,884.75.
Read the two thresholds carefully, because they are not the same test. The DLD route asks for AED 2 million paid against a mortgaged property; the ICP route asks for total property value of at least AED 2 million financed through an approved local bank. Which door you use determines how much cash equity you need. For a buyer structuring a purchase around residency eligibility, that distinction is worth a conversation with the lender before exchange, not after.
Still reading
Need expert help on this subject?
New DCT Abu Dhabi rules allow individual owners, joint owners, legal entities, tenants and authorised persons to operate holiday homes. Units cannot be listed online without a valid DCT Abu Dhabi licence, and the licence number must be displayed on listings. Occupancy is capped at three people per room, partial room rentals are not permitted, and units cannot be subdivided. In 2025, Abu Dhabi's holiday home supply grew 77% year-on-year, adding over 2,000 eligible units to end the year at 4,771, while guest volumes rose 77% to slightly over 335,000 — domestic guests up 114% to 82,900 and international visitors up 68% to 252,500.
Permitting tenants to operate licensed holiday homes enlarges the supply pool without a single new unit being built, because it converts existing leased stock into short-let inventory. For a landlord, that cuts both ways: it may raise the rent a tenant can afford to pay you, and it will increase competition for the same guest. If you own in Abu Dhabi, two practical items this week — check whether your lease permits sub-letting into short-let use, and check whether your building insurance and owners' association rules contemplate it.
Aldar and Mubadala acquired Masdar City Square for AED 918 million ($250 million) through their 2024 joint venture, taking the JV's Masdar City portfolio to AED 4.7 billion ($1.28 billion). The asset comprises more than 47,000 sq m of net leasable area, completed in Q1 2026 and 99% occupied, with tenants including TAQA, the Department of Energy, Emirates College and Mohamed bin Zayed University of Artificial Intelligence. The JV now holds more than 158,000 sq m of commercial space with a weighted average unexpired lease term of approximately 5.2 years, plus more than 1,400 fully occupied residential units.
A 5.2-year WAULT on a 99%-let complex, bought by two state-linked balance sheets, is an institutional bid for long-income Abu Dhabi office at a moment when many global office markets are still discounting the asset class. Private investors cannot access this trade directly, but they can read it: covenant quality and lease length are being paid for, and short-let or vacant-possession office stock is not the same product.
Brent settled down 0.95% at $103.87 a barrel on Friday and WTI down 1.61% at $100.30, both having been up more than 2% earlier in the day. Week-on-week, Brent fell about 0.7% while WTI rose 0.24%. Prices had surged towards $110 on Monday after Saudi Arabia shut its East-West pipeline following attacks, and on Thursday Saudi Civil Defence reported one person killed and two injured by debris from an intercepted Houthi drone in Taif governorate. Iran's Mohammad Bagher Zolghadr said Tehran would not reopen the Strait of Hormuz until Trump and Netanyahu are removed from power. Gold settled at $4,377.91 an ounce and silver at $66.25.
Set against that, a Reuters poll cited this week found most Gulf economies are expected to contract more sharply this year than previously forecast before rebounding in 2027, linked to the Iran conflict and the effective closure of Hormuz.
Triple-digit oil supports UAE fiscal capacity and the government spending that underwrites much of the property demand picture — but it is doing so through a supply disruption, not through demand strength, and the same disruption is what the Reuters poll expects to shrink regional output this year. Do not read $103 Brent as an unambiguous positive for your rent roll.
In closing
Final View for Dubai Property Investors
Three things changed this week that should change an investor's behaviour. The cost of money went up for the first time since 2023, and the peg means it went up here automatically. Transaction volumes recovered materially from May's floor but did so with up to 76% of deals in off-plan, against a 2027 completion ceiling that could reach 160,700 units. And the most credible independent dataset of the week — Cavendish Maxwell's retail report — showed capital values racing ahead of leasing fundamentals, with sales value up 177% while new rental contracts fell 26%.
The practical response is the same in each case: separate the price you pay from the income you will actually collect, and date both. This week, that means re-running every variable-rate debt schedule at the new base rate; asking any off-plan seller for the handover cohort around your unit rather than just your own completion date; and, if you are buying commercial strata on the back of the retail numbers, testing the deal against a signed 2028 lease rather than a projected one. For those structuring around residency, check whether your purchase is being assessed on AED 2 million paid or AED 2 million of value before you commit the equity — the answer is worth more than the rate move.
Next step
Let’s Talk
If you’d like to unpack where the most resilient opportunities are emerging — in stabilised residential areas or income-generating commercial zones — I’d be happy to share a focused, data-driven shortlist based on your investment goals.
📞 No pressure, no sales pitch—just a focused, informed conversation about your investment goals.
Published 19 September 2026 by Stephen James Mitchell MBA. Market figures quoted reflect the data available at that date.