Dubai’s property market remains red-hot in July 2025, with fresh records being set across sales volumes, prices, and mortgage activity. Yet beneath the surface, signs of cooling momentum and buyer selectivity are becoming more visible.
For investors, the July 2024 Property Monitor Report offers valuable insights into both risks and opportunities shaping the market’s next phase.
Measured Growth vs. Market Momentum
Property prices rose 0.99% month-on-month, pushing the average to AED 1,625 per sq ft. That’s 31.7% above the 2014 peak. For context, property prices in the US are now more than 100% above 2014 levels, suggesting the UAE market still has significant headroom compared to other developed economies.
However, compared to June’s 1.71% increase, July’s rise reflects a more measured pace. This doesn’t signal weakness—it suggests the market is normalizing after months of rapid acceleration.
Apartments vs. Villas & Townhouses: Diverging Trends
- Apartments: Price growth is slowing, a possible indicator of saturation.
- Villas & Townhouses: These segments continue to gain momentum, reflecting growing demand for larger homes, lifestyle upgrades, and long-term investments.
For investors, this divergence underscores the importance of choosing the right asset class. Villas and townhouses are showing resilience, while apartments face greater competition from the surge in new launches.
👉 Get in touch today to explore the best opportunities in Dubai’s dynamic property market.
July 2025 Sales Surge Explained
Dubai recorded 20,116 transactions in July, a 21.3% increase from June. While this seems like a dramatic surge, much of it reflects a rebound from June’s Eid slowdown.
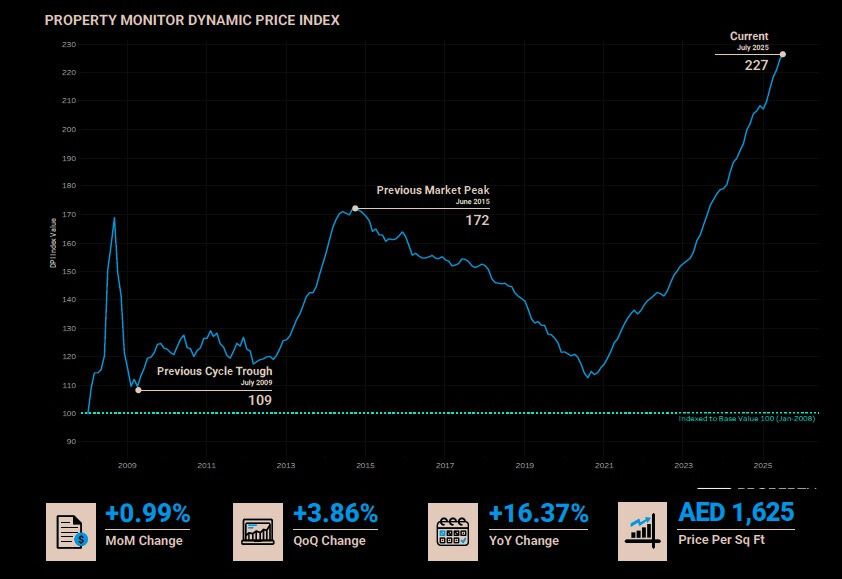
Image Credit: Property Monitor
Residential vs. Commercial Split
- Residential (93.7% of sales): 18,843 transactions
- Commercial: Office spaces (2.2%), vacant land (1.3%), hotel apartments (0.9%), retail spaces (0.9%)
Residential remains the dominant driver, reinforcing Dubai’s position as a preferred end-user and investor hub.
Year-to-Date Sales on Track for 200K+
With over 119,000 transactions YTD, sales are already 23% higher than 2024. If this pace continues, Dubai will surpass 200,000 transactions in 2025, setting yet another all-time record.
Off-Plan Transactions Dominate with 72% Share
Off-plan sales surged in July, representing 72.1% of the market after adjusting for classification differences. Developers’ incentives, flexible payment plans, and attractive launches are driving this dominance.
Resale Activity Declines – Why It Matters
Resale transactions fell 5.2% month-on-month, now at 27.7% of total sales. Off-plan resales, once above 33% in April, have dropped to 19.9%.
This decline signals that buyers prefer new launches directly from developers, leaving resellers struggling to match pricing and payment flexibility.
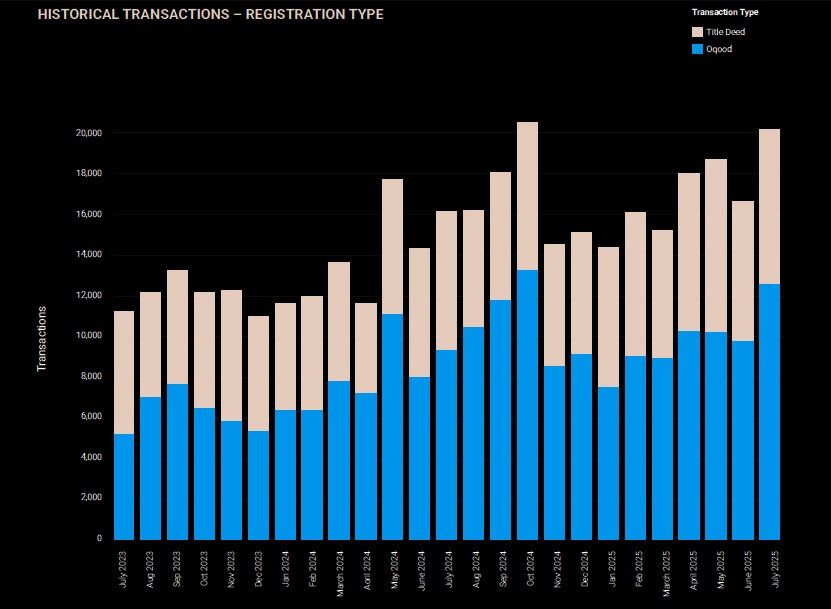
Image Credit: Property Monitor
Buyer Behavior: Incentives vs. Premium Pricing
Many resale listings are priced at premiums, but today’s buyers are more value-conscious and selective.
For investors, this means flipping off-plan units before handover is no longer a guaranteed profit strategy.
July’s 50+ Launches Bring 13,800 New Units
Developers launched 13,800 units worth AED 38B in July alone, pushing the YTD tally to 93,000 units and AED 270B in sales potential.
Buyer Urgency Eases – More Value-Driven Decisions
Unlike in previous years, projects aren’t selling out in hours. Instead, buyers are taking time to compare, evaluate, and negotiate. This doesn’t indicate weakening demand, but rather a more mature, sustainable market dynamic.
For investors, this means that project differentiation and location will matter more than ever.
📩Reach out to discuss which upcoming projects stand out in Dubai’s crowded launch pipeline and where real long-term value can be found.
Still reading
Need expert help on this subject?
Surge in New Purchase Mortgages
Mortgage activity hit a record 4,891 loans in July, with new purchases accounting for 45.6% of activity. Average loan sizes stood at AED 1.8M.
Lower Loan-to-Value Ratios Signal Affordability Pressures
The average LTV ratio at 73.7% remains below the historical 75–77% range. This reflects tighter lending regulations, requiring higher upfront cash commitments from buyers.
Image Credit: Property Monitor
Bulk Mortgages: Developers & Portfolio Investments
785 bulk loans were issued, spread across large projects like Rabdan Building and Shorooq Land 2. This suggests institutional confidence remains strong, even as retail buyers face affordability challenges.
Read the full report: July 2025 Property Monitor Report
The July 2025 Property Monitor Report signals both challenges and opportunities. Here’s what investors should consider:
Risks: Oversupply & Selectivity Rising
Oversupply: With 93,000 new units launched YTD, resale values face pressure.
Strategy:Target low-density projects, prime locations with limited supply, or mixed-use communities that hold long-term appeal.
Affordability Constraints: Lower LTV ratios reduce the pool of mortgage-backed buyers.
Strategy:Focus on cash-rich international buyers, rental units for professionals, and properties supported by innovative mortgage solutions.
Fewer Flipping Opportunities: Off-plan resales dropped to 19.9% of transactions.
Strategy: Shift to mid-term holds, negotiate bulk deals directly with developers, or exit near completion when end-user demand strengthens.
Opportunities: Commercial Properties, Villas, Townhouses, and Value Projects
Commercial Real Estate: With supply at record lows and residential facing oversupply, commercial presents a prime opportunity for investors seeking higher yields and price stability to diversify their portfolios.
Strategy: Consider shifting capital into commercial assets where demand is strong, vacancy rates are low, and yields are more robust.
Villas & Townhouses: Demand remains resilient, with lifestyle-driven buyers leading growth.
Strategy:Prioritize units in well-established communities, corner or park-facing plots, and locations with strong rental potential.
High Liquidity: With Dubai on track for 200,000+ sales in 2025, market entry and exit are easier.
Strategy:Accumulate during seasonal lulls, reinvest rental yields into off-plan projects, and position assets for global buyers seeking safe-haven markets.
End-User Focus: Buyers are value-driven, preferring affordable projects with strong amenities and flexible terms.
Strategy: Invest in mid-market communities, seek developer incentives (post-handover plans, waived service fees), and avoid oversupplied “cookie-cutter” projects.
Portfolio Balance
Investors should diversify across:
- Commercial real estate
- Ready units for rental income.
- Villas/townhouses for capital growth.
- Selective off-plan projects for longer-term upside.
Frequently asked questions
1201Are Dubai property prices still rising in 2025?
Yes, prices are up 0.99% in July and stand 31.7% above the 2014 peak. Growth has slowed but remains positive.
02Is the Dubai real estate market at risk of oversupply?
With 93,000 new units launched YTD, oversupply risk is rising. Demand is still strong, but absorption is slowing.
03Should investors focus on off-plan or resale properties?
Off-plan dominates with 72% market share. Resale activity is softening, making quick flips harder.
04Which property types are performing best?
Villas and townhouses are outperforming apartments, driven by end-user and lifestyle demand.
05How is mortgage availability affecting buyers?
Mortgages hit a record high, but lower LTV ratios mean higher upfront cash requirements.
06What’s the outlook for the second half of 2025?
Expect continued activity, but with greater buyer selectivity and slower absorption of new launches.
07Where are the best opportunities for long-term capital growth?
Emerging mid-market communities like JVC, Al Furjan, and Dubai Land still offer strong upside.
08How can investors protect against oversupply risk?
Focus on prime locations, low-density projects, and branded residences where demand remains resilient.
09Are rental yields still attractive in 2025?
Yes, yields remain healthy, particularly in mid-market apartments and family-friendly villa communities.
10Is flipping off-plan properties still a viable strategy?
Quick flips are less reliable. The stronger play is holding until near handover when end-user demand peaks.
11How are global investors viewing Dubai real estate?
Dubai is seen as a safe-haven market, attracting capital from Europe, Asia, and GCC investors.
12What should investors prioritize when selecting projects in 2025?
Look for developer credibility, delivery timelines, and unique value propositions over hype-driven launches.
Next step
Let’s Talk: Positioning Your Portfolio for Dubai’s Next Phase
The July 2025 Property Monitor Report shows a market still breaking records—prices are climbing, sales volumes are at all-time highs, and mortgage activity continues to expand.
But behind the headlines, the landscape is shifting: supply is at historic levels, affordability is tightening, and buyers are becoming more selective. For investors, this isn’t a warning—it’s a signal to adapt.
Now is the time to focus on:
- Villas and townhouses in communities where lifestyle-driven demand is strongest
- Value-focused off-plan projects with real differentiation and flexible payment terms
- Prime resale units that hold their value despite new supply pressures
- Bulk and portfolio acquisitions structured for income resilience and yield growth
- Tailored strategies grounded in transaction data, absorption trends, and financing realities
Whether your priority is capital appreciation, rental yield, or securing allocations in high-demand launches, I can provide the insight, access, and structure to move decisively.
📞 No pressure, no sales pitch—just a focused, informed conversation about your investment goals. Let’s talk!
Published 27 August 2025 by Stephen James Mitchell MBA. Market figures quoted reflect the data available at that date.