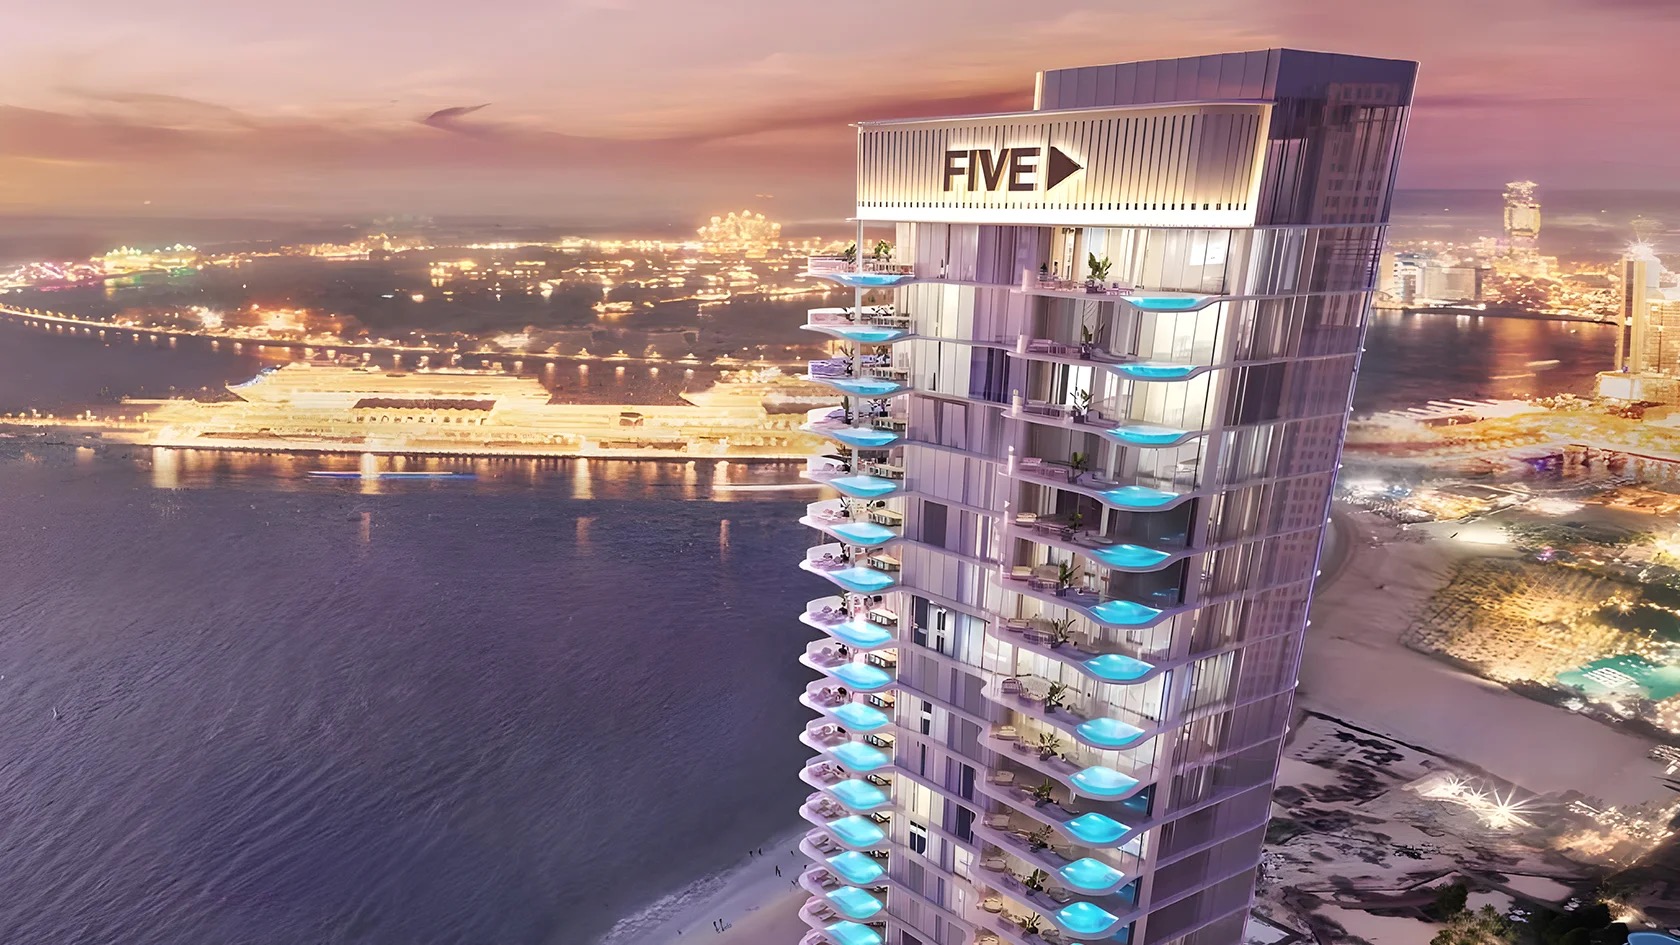
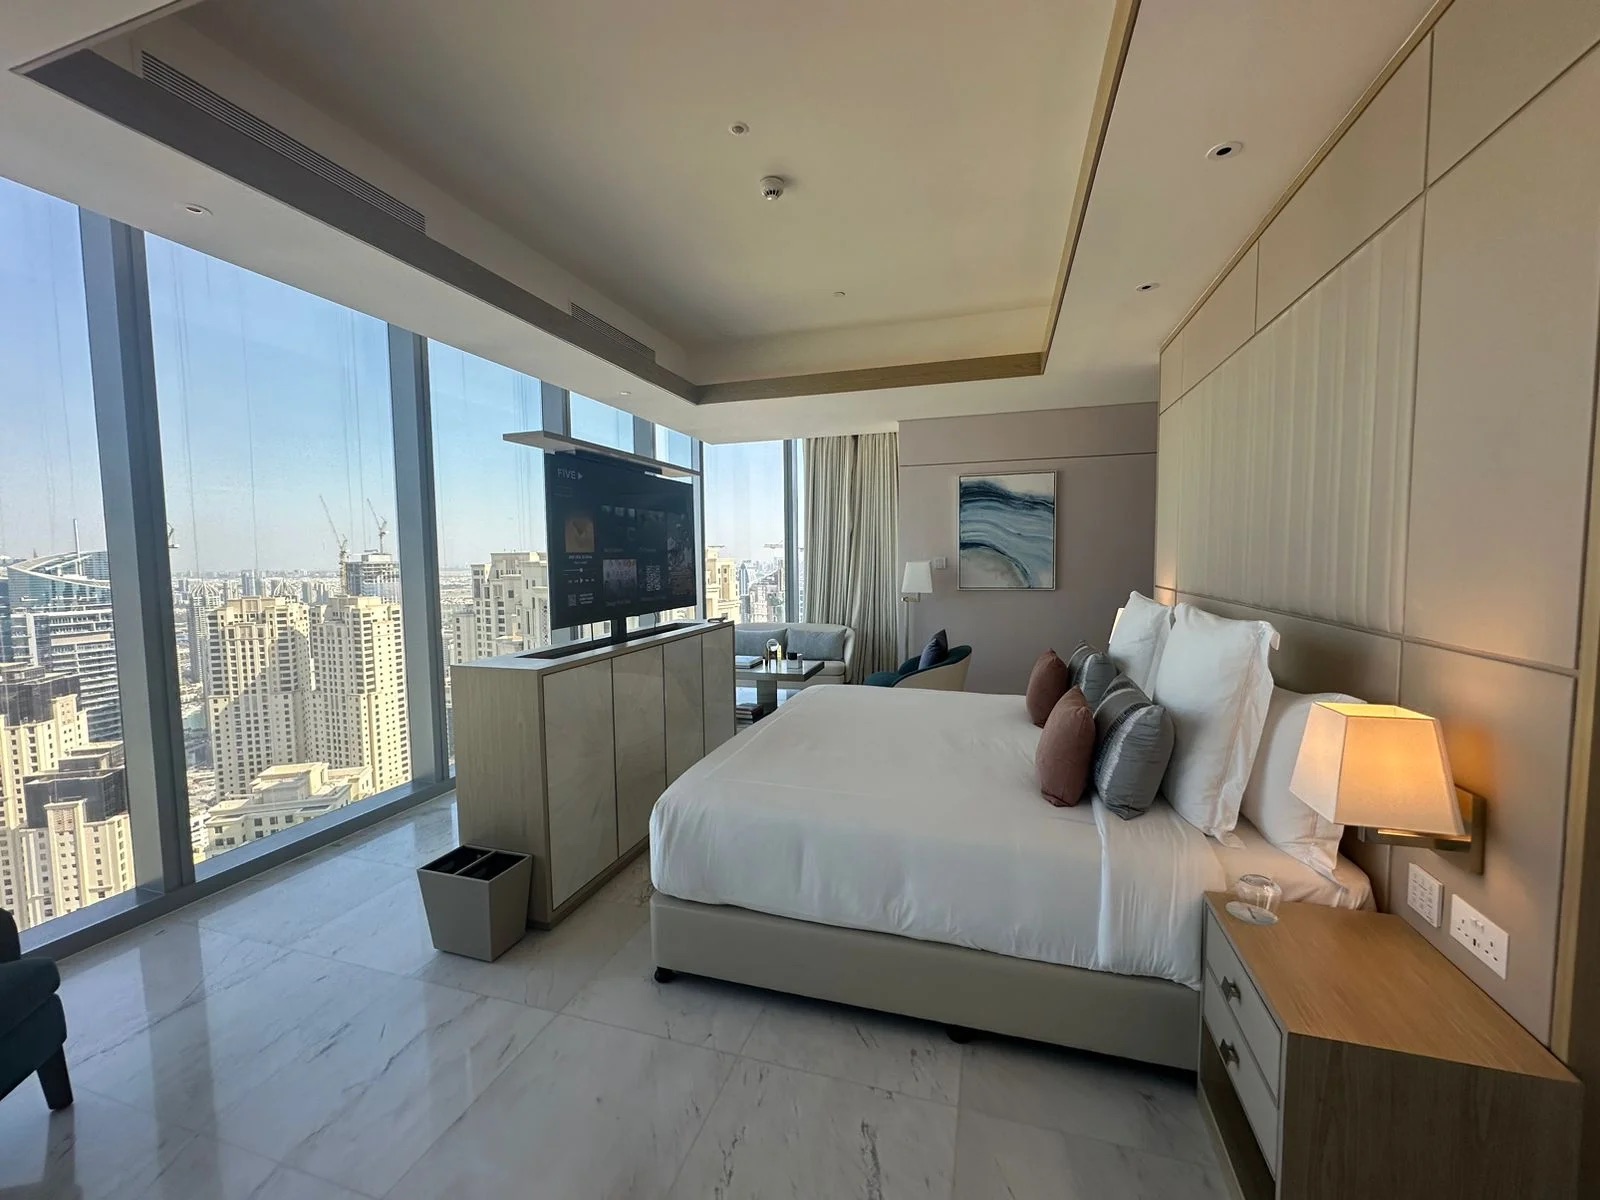
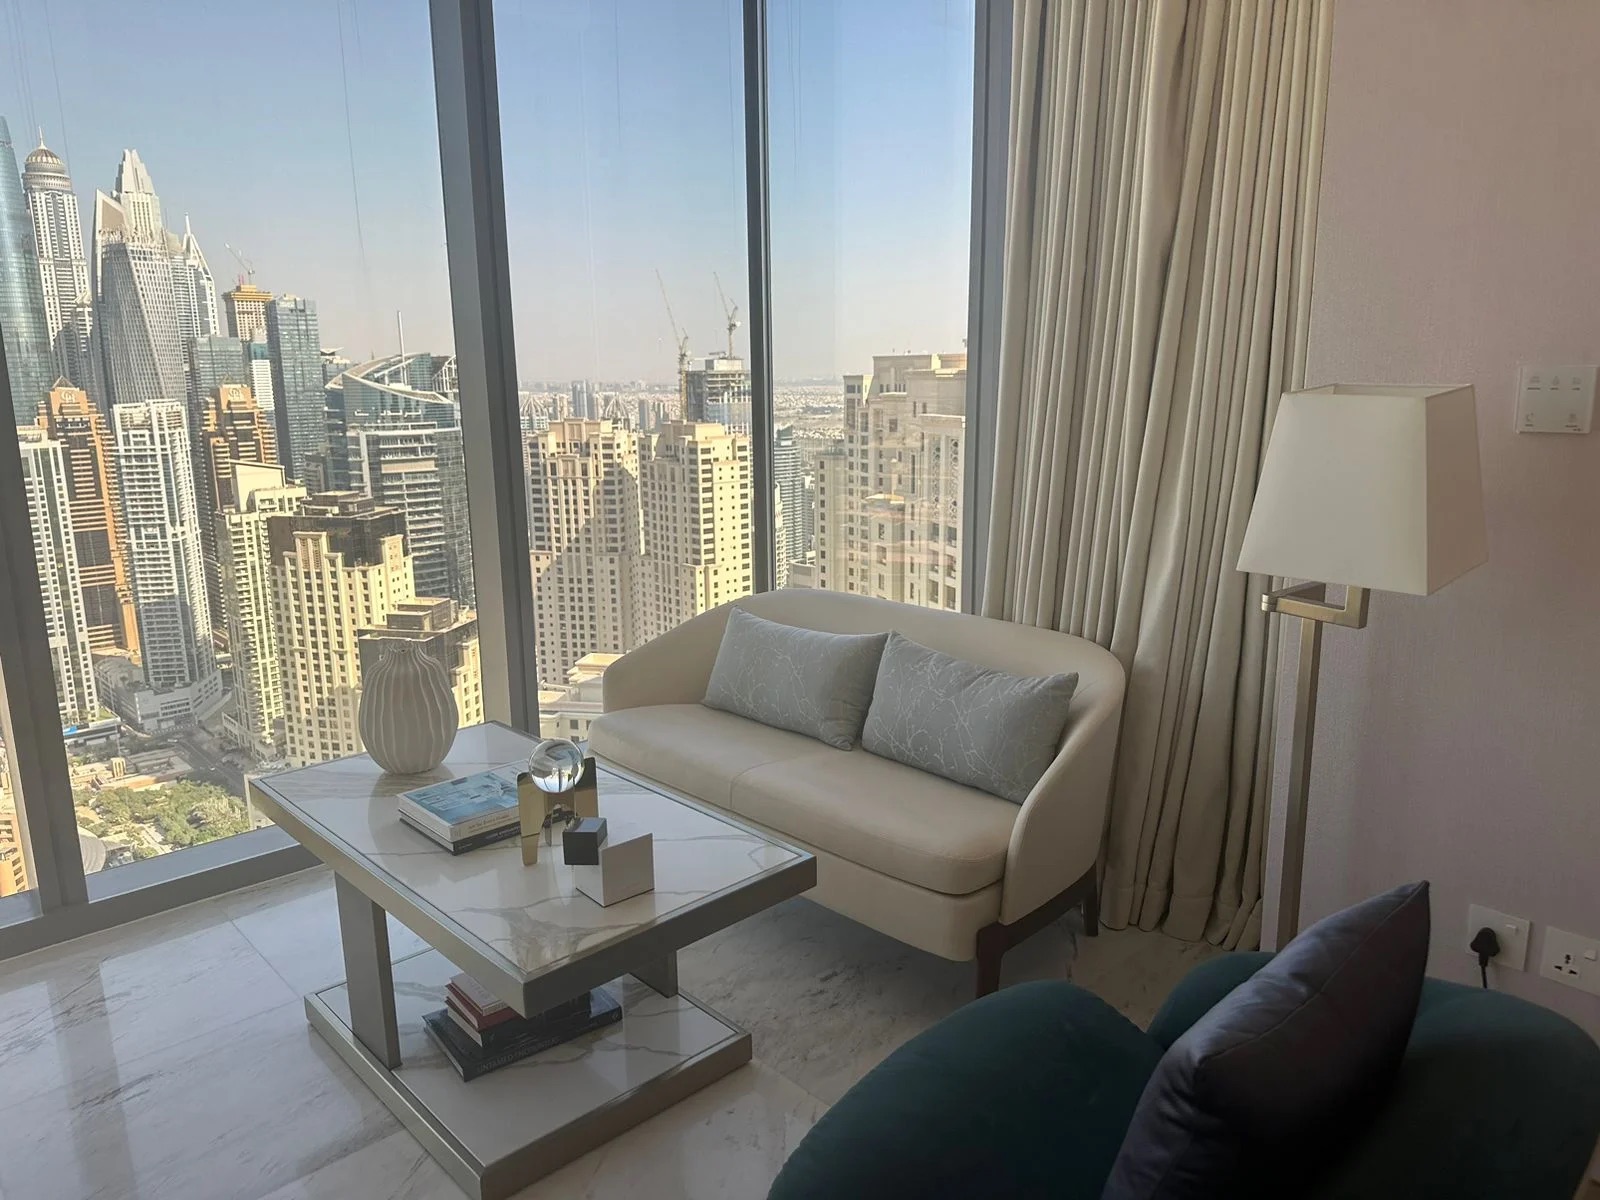
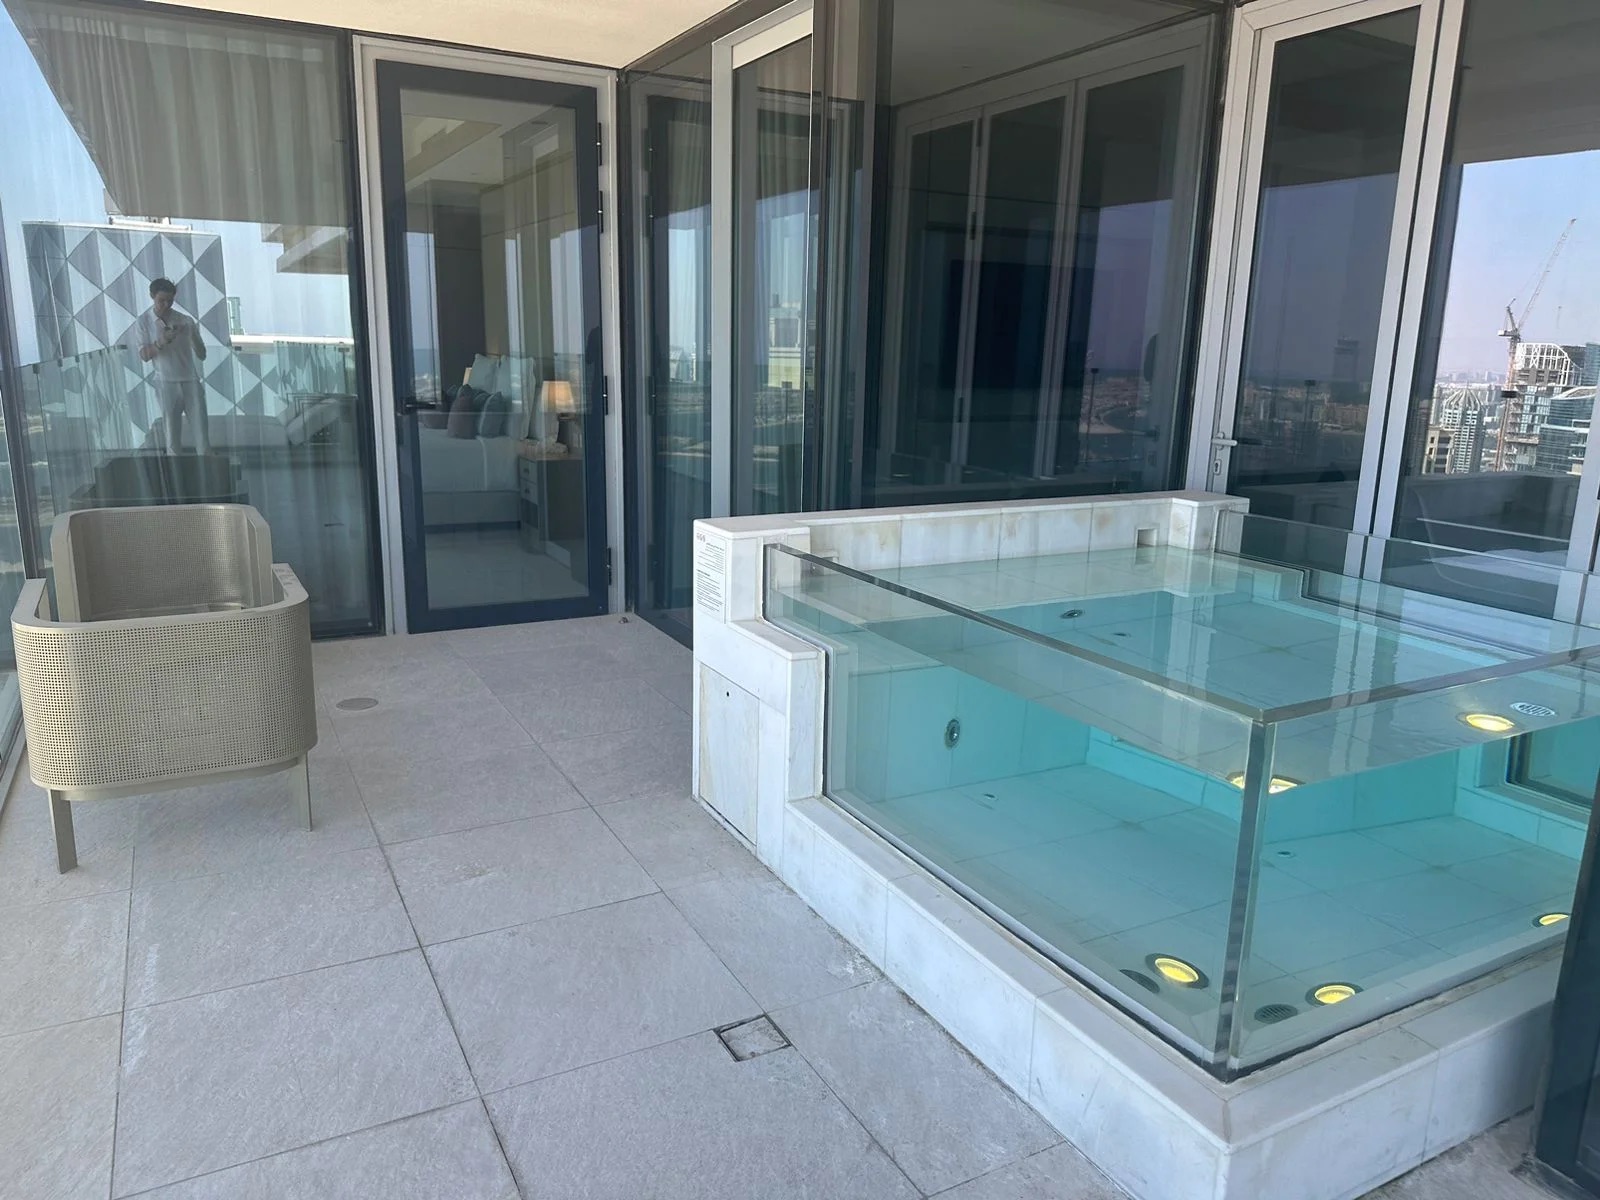
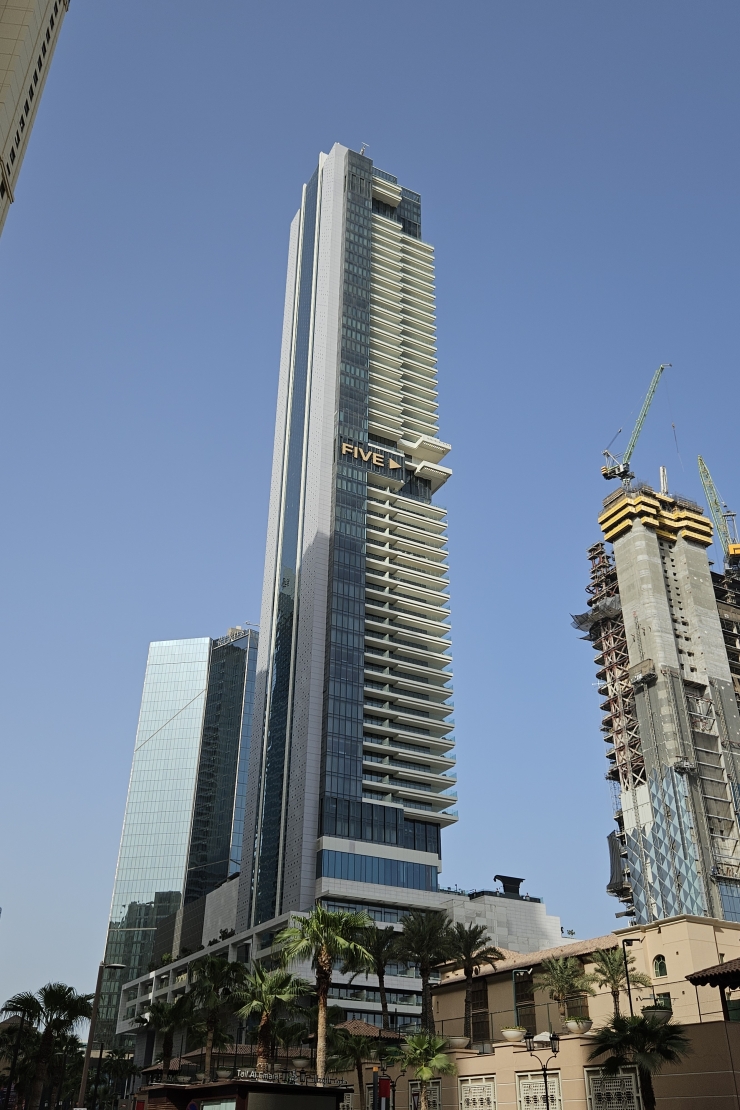
This two-bedroom apartment at Five Luxe, Jumeirah Beach Residence, is offered at AED 7,500,000 against a market price of AED 8,690,000 — AED 1,190,000, or 13.7%, below market. The unit is high floor, 1,603 sq.ft, with sea and Palm Jumeirah views, and it is ready. That last point governs everything else about the deal. There is no developer balance to inherit, no completion date to underwrite and no instalment ladder: the full AED 7,500,000 goes to the seller at transfer, and with fees the total cost to the buyer is AED 7,962,320. The entry basis is AED 4,679 per sq.ft on built-up area. Because the property is complete and vacant, the discount here is quoted against market evidence rather than against an original developer price, which is the correct basis for a completed resale.
Devco · Jumeirah Beach Residence
DISTRESS DEAL: 2-BR IN FIVE LUXE
- Unit
- 2-BR
- Size
- 1,603 sq.ft
- Developer
- Devco
The discount is measured against the market price recorded for this unit, not against a valuation.
Available when we last checked. The asking price shown is the one published when the listing was added on 19 September 2026, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.
On this page
Quick navigation
The numbers
Payment breakdown
- Payment to sellerAED 7,500,000
- DLD Transfer fee (4% + 40 AED)AED 300,040
- Trustee Office FeeAED 4,200
- Buyer's Agency Commission (2% + VAT)AED 157,500
- Title Deed FeeAED 580
- Total on transferAED 7,962,320
Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.
Ask about these termsUnit details
- Property type
- Apartment
- Floor
- High
- View
- Sea and Palm Jumeirah
- Handover
- Ready
Photography
Gallery
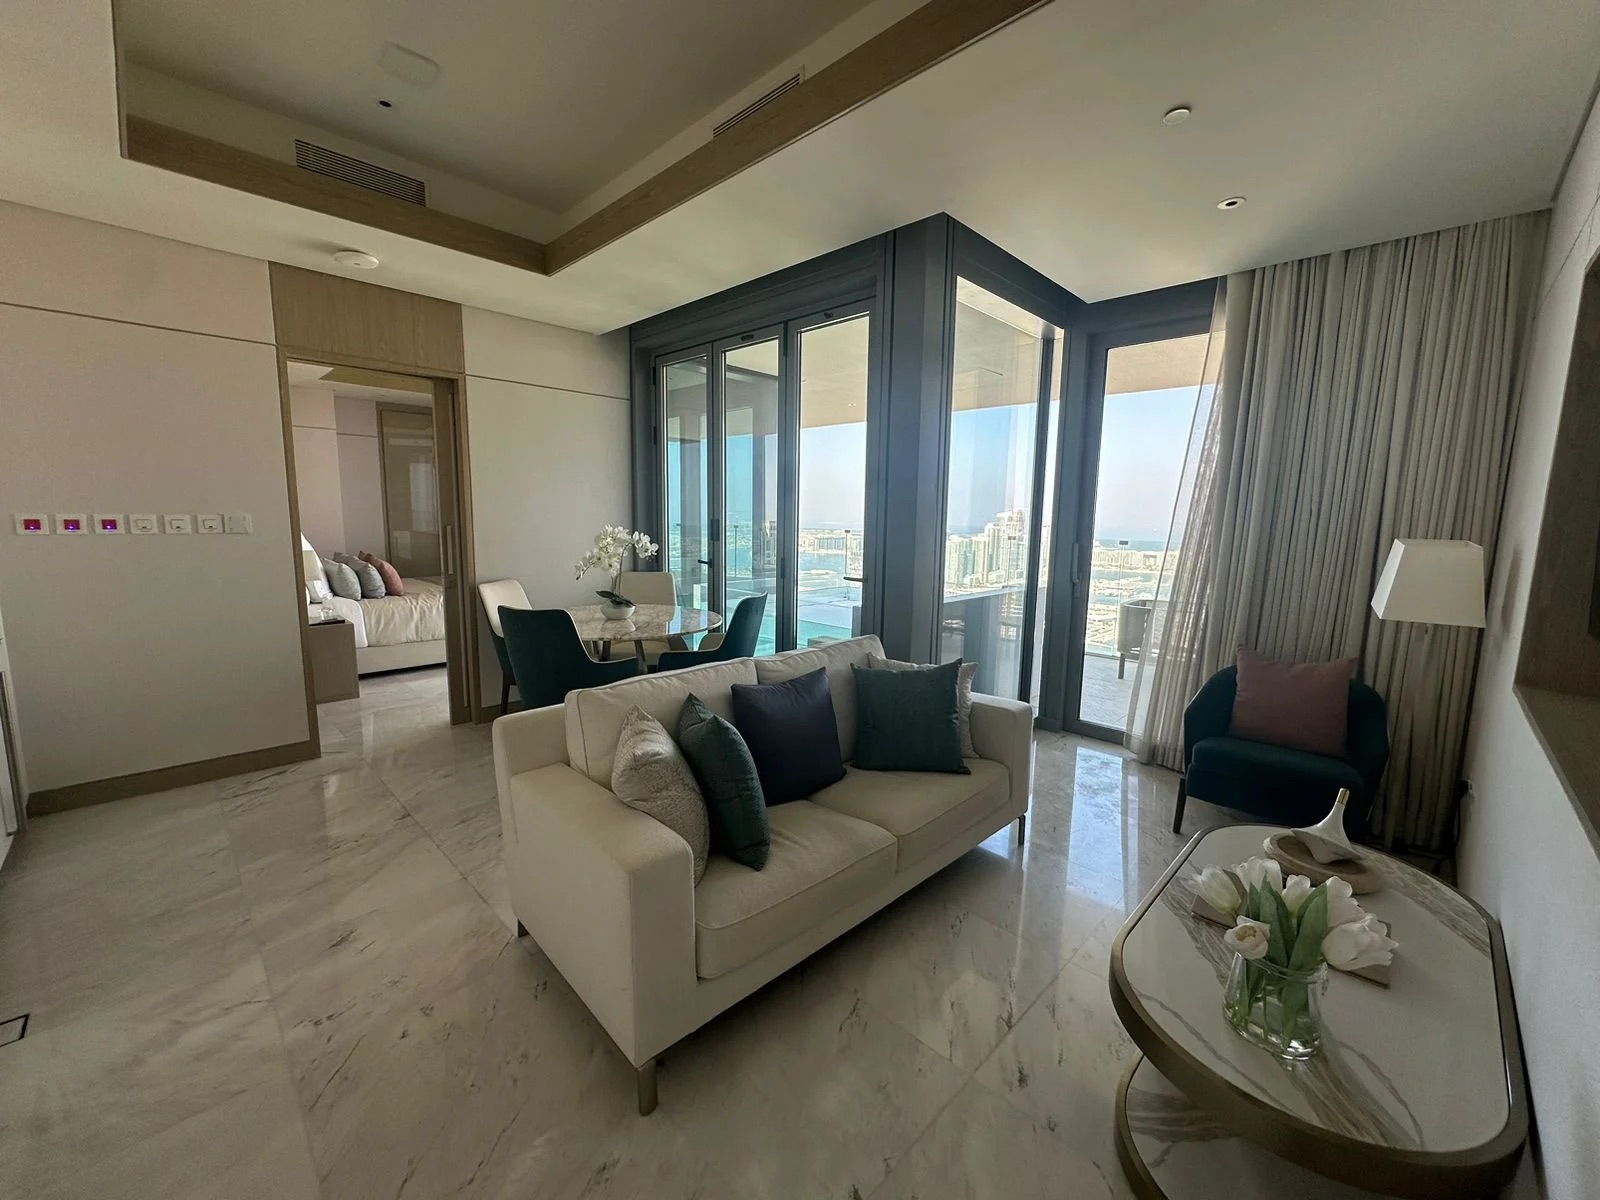
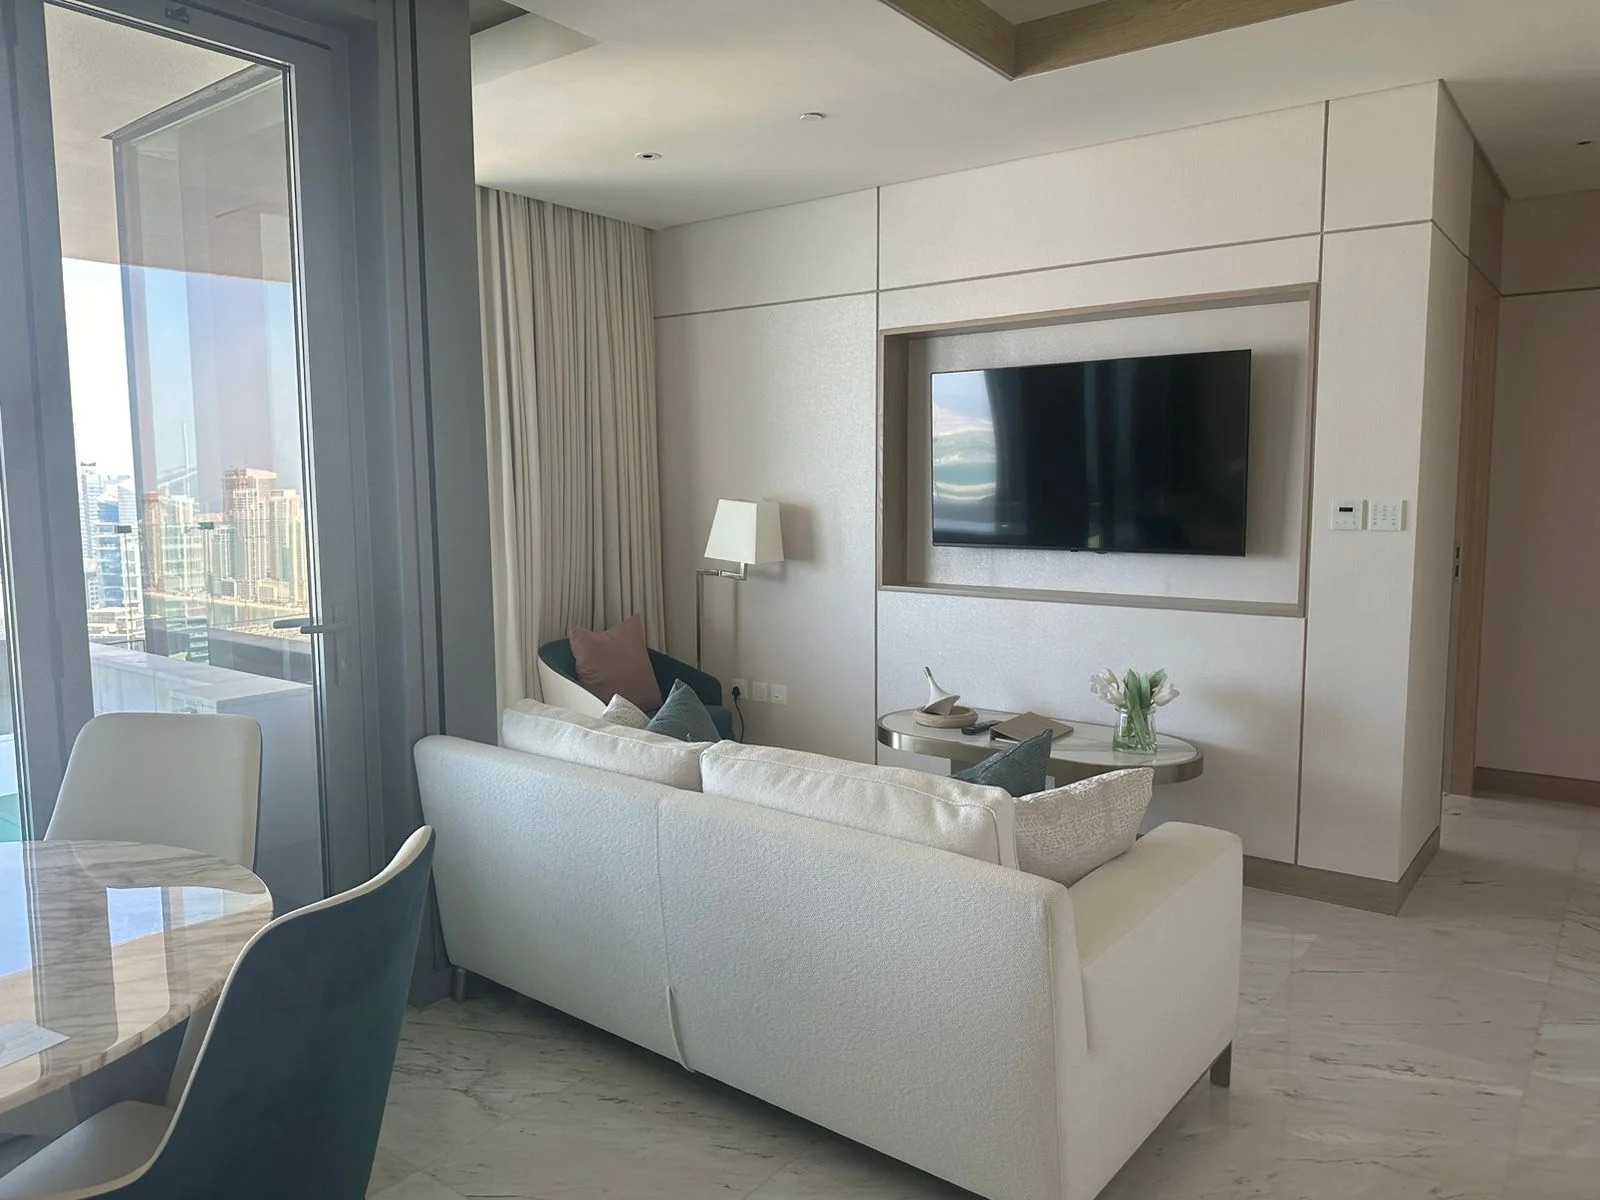
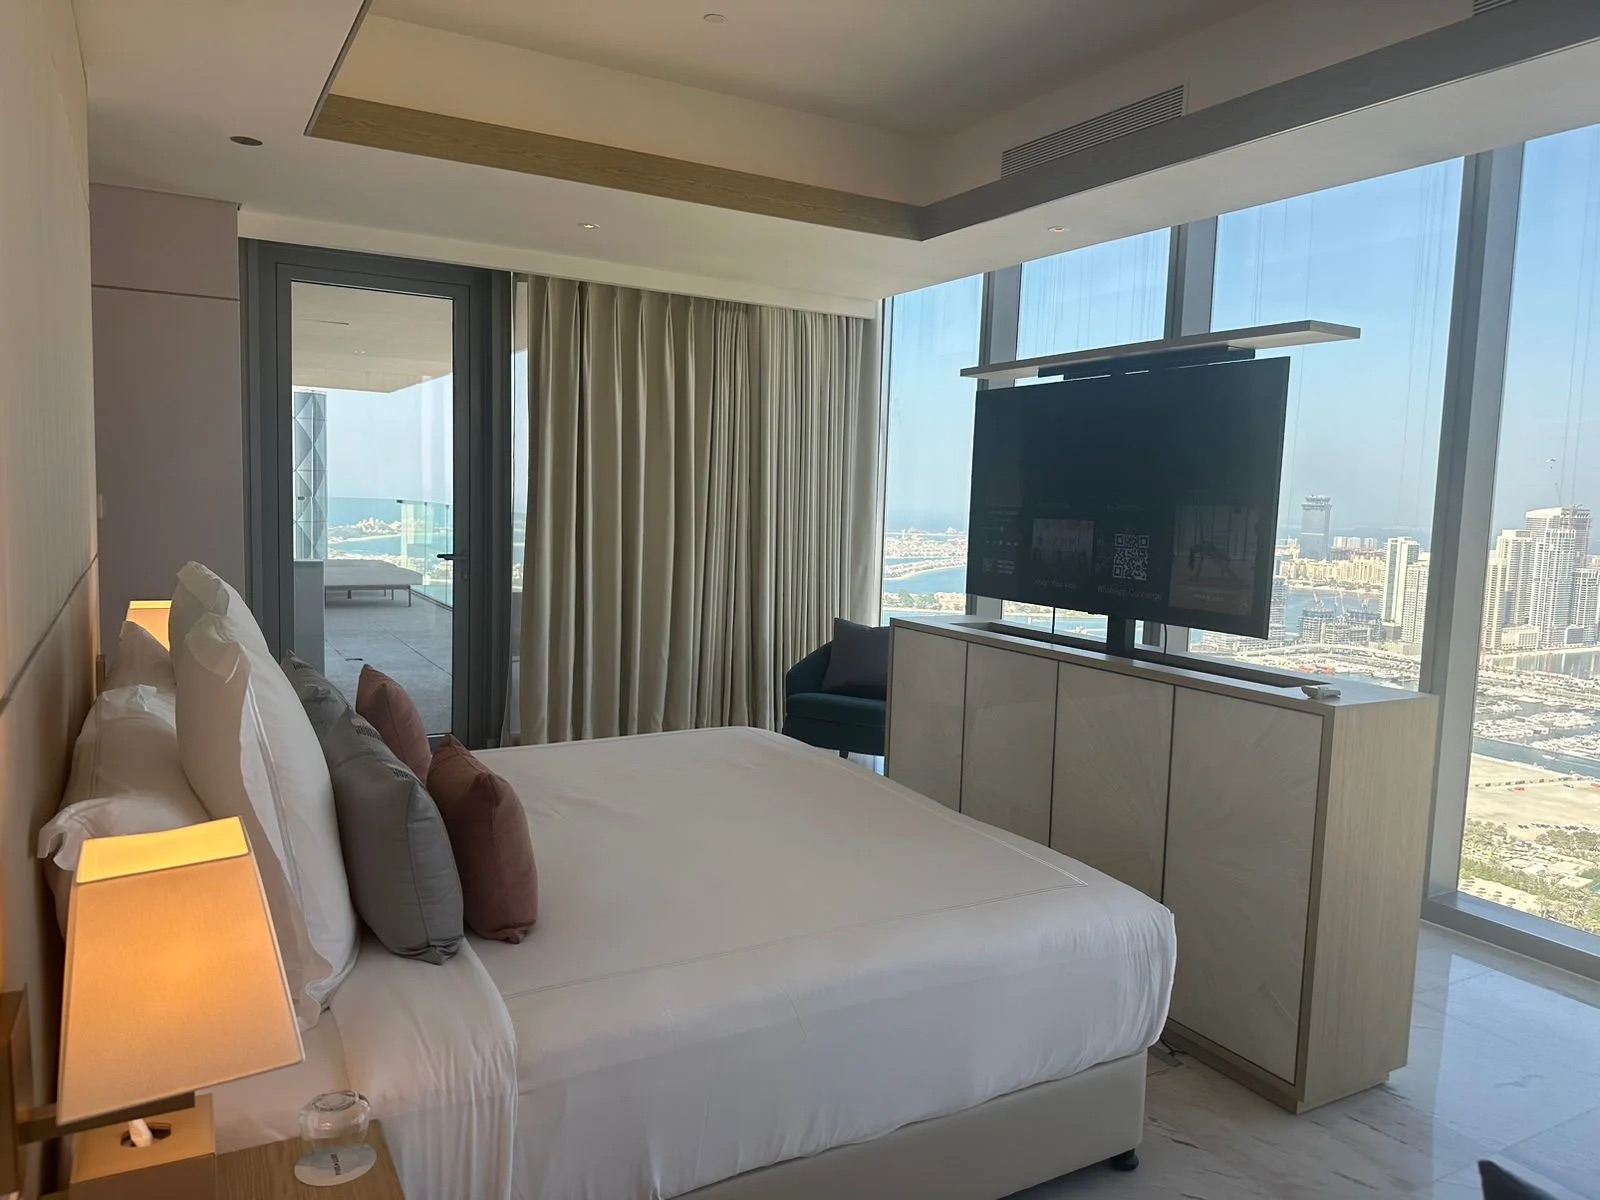
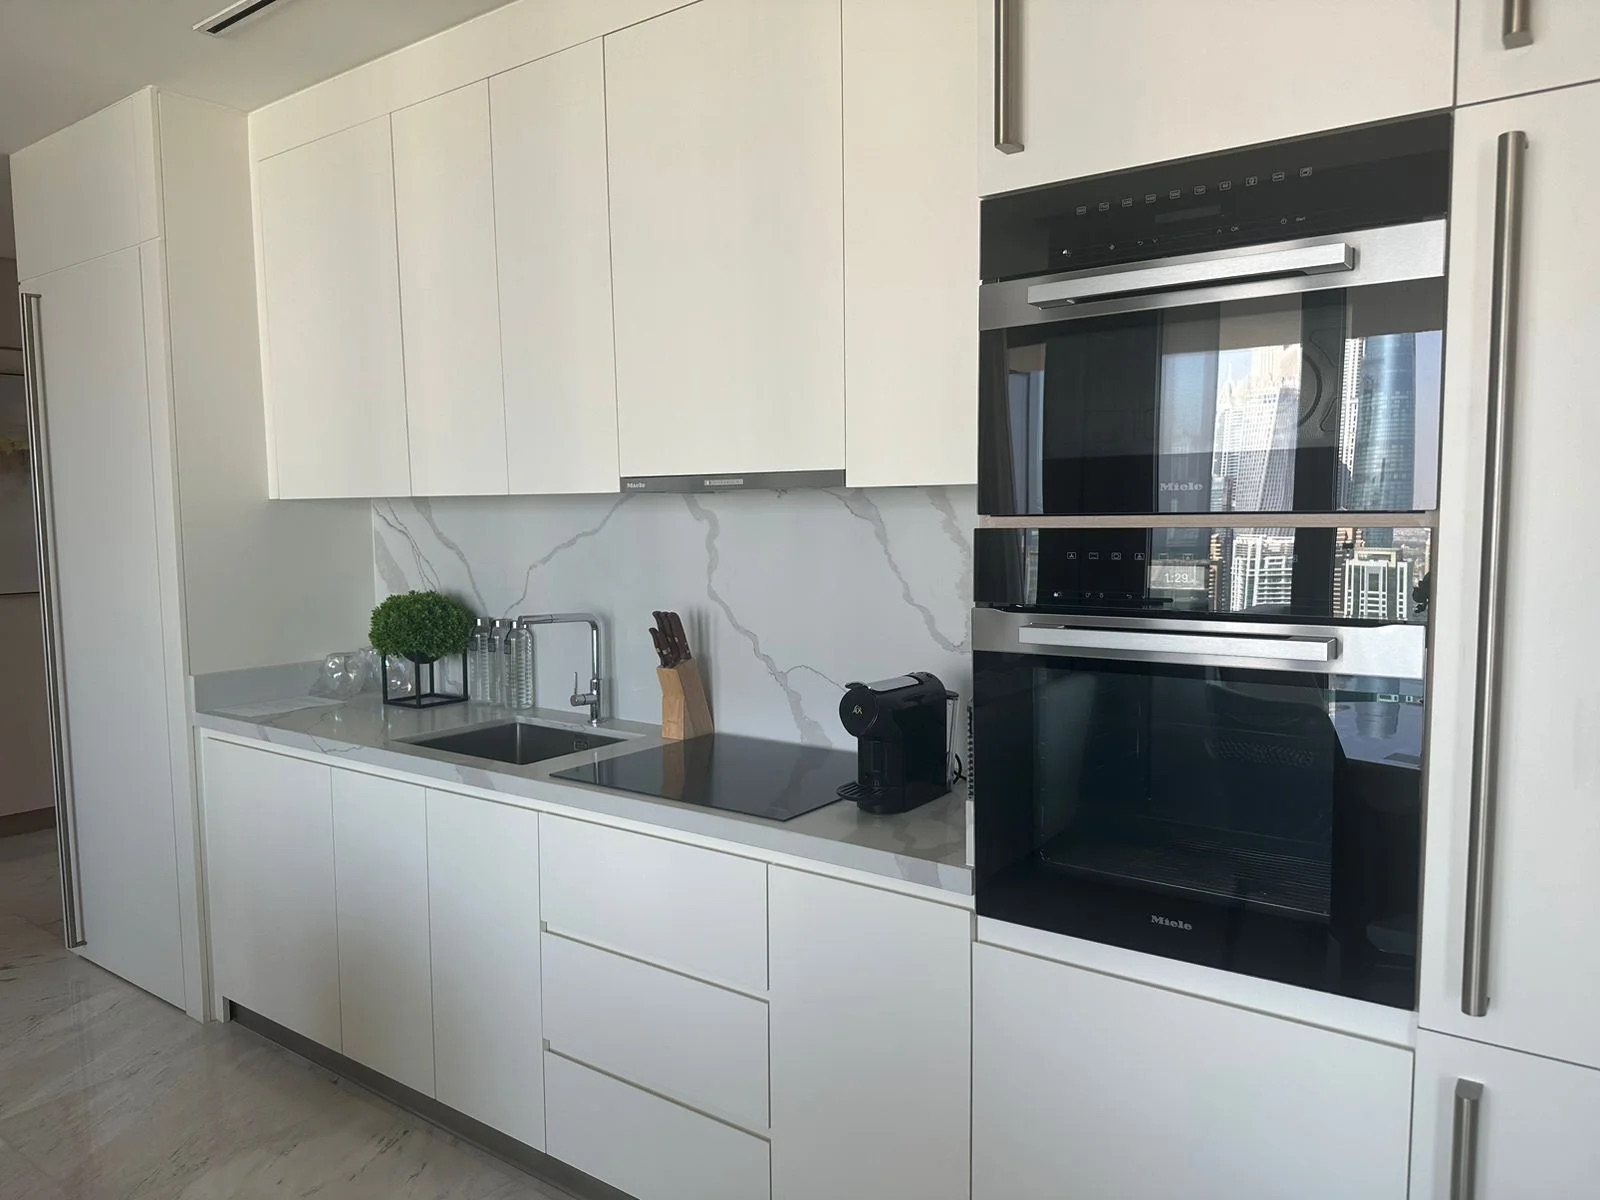
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
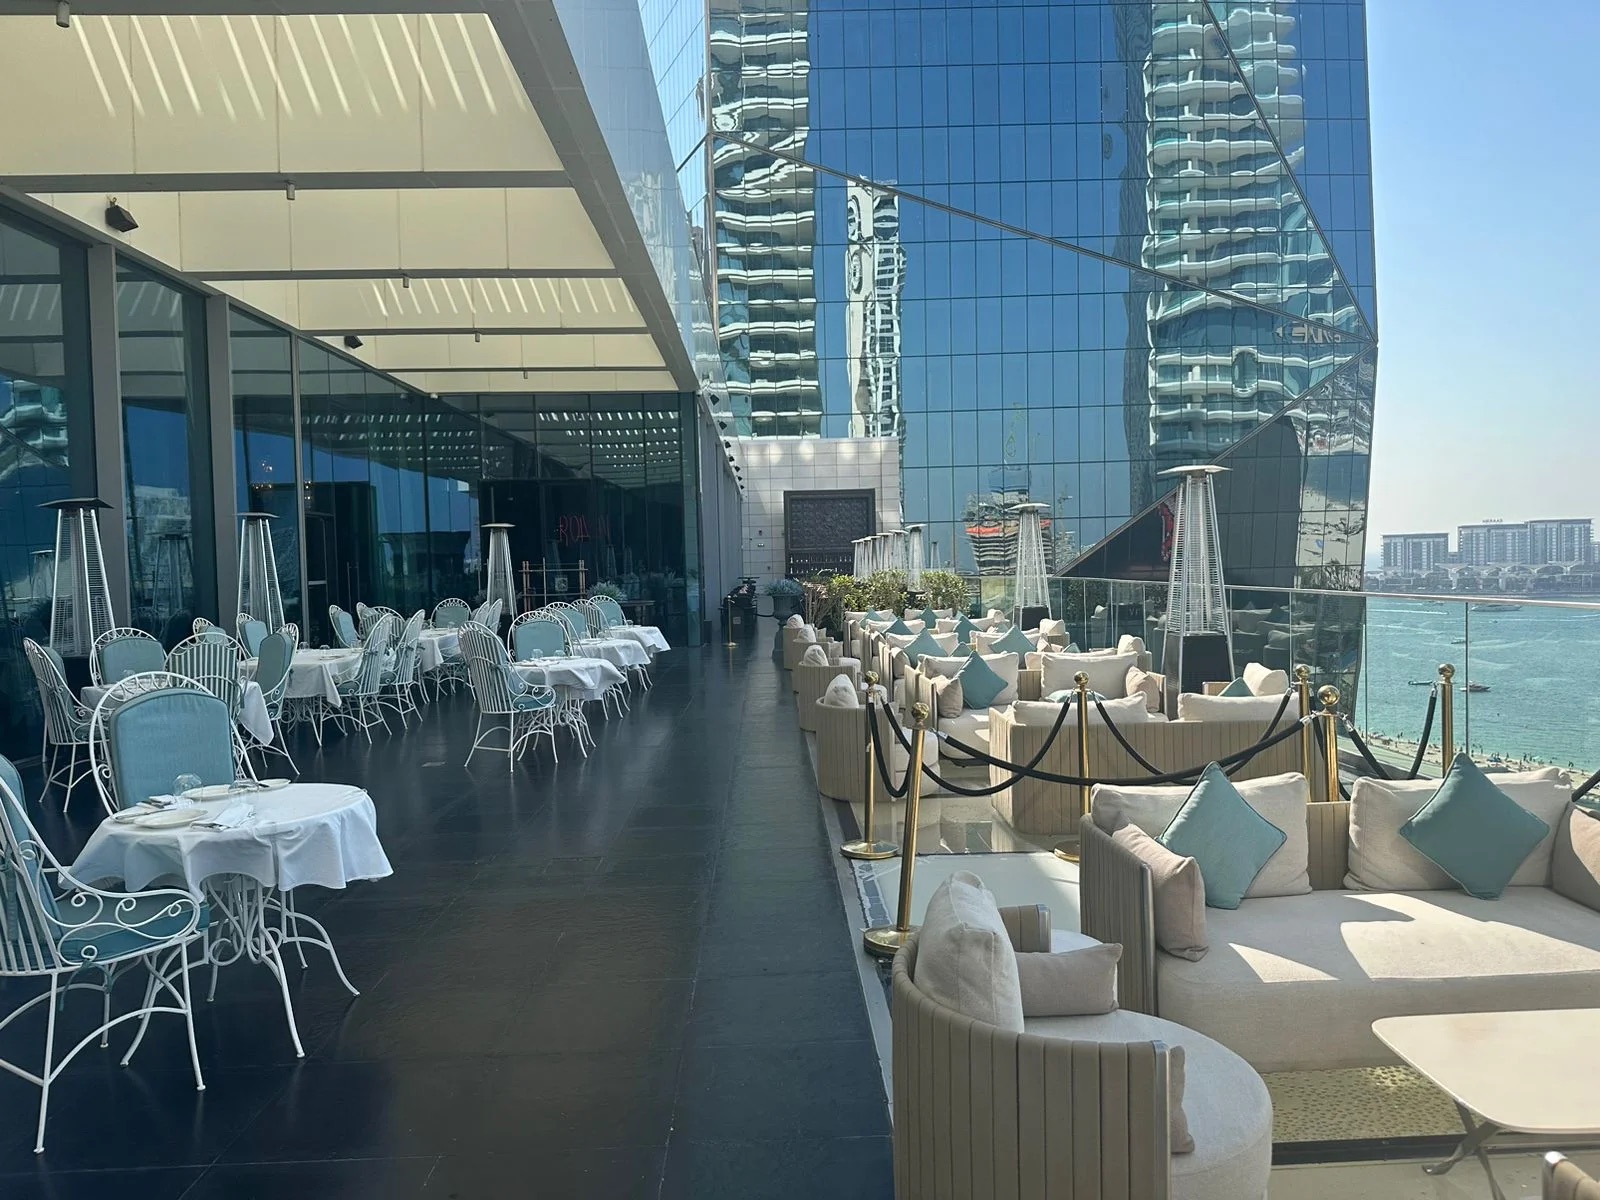
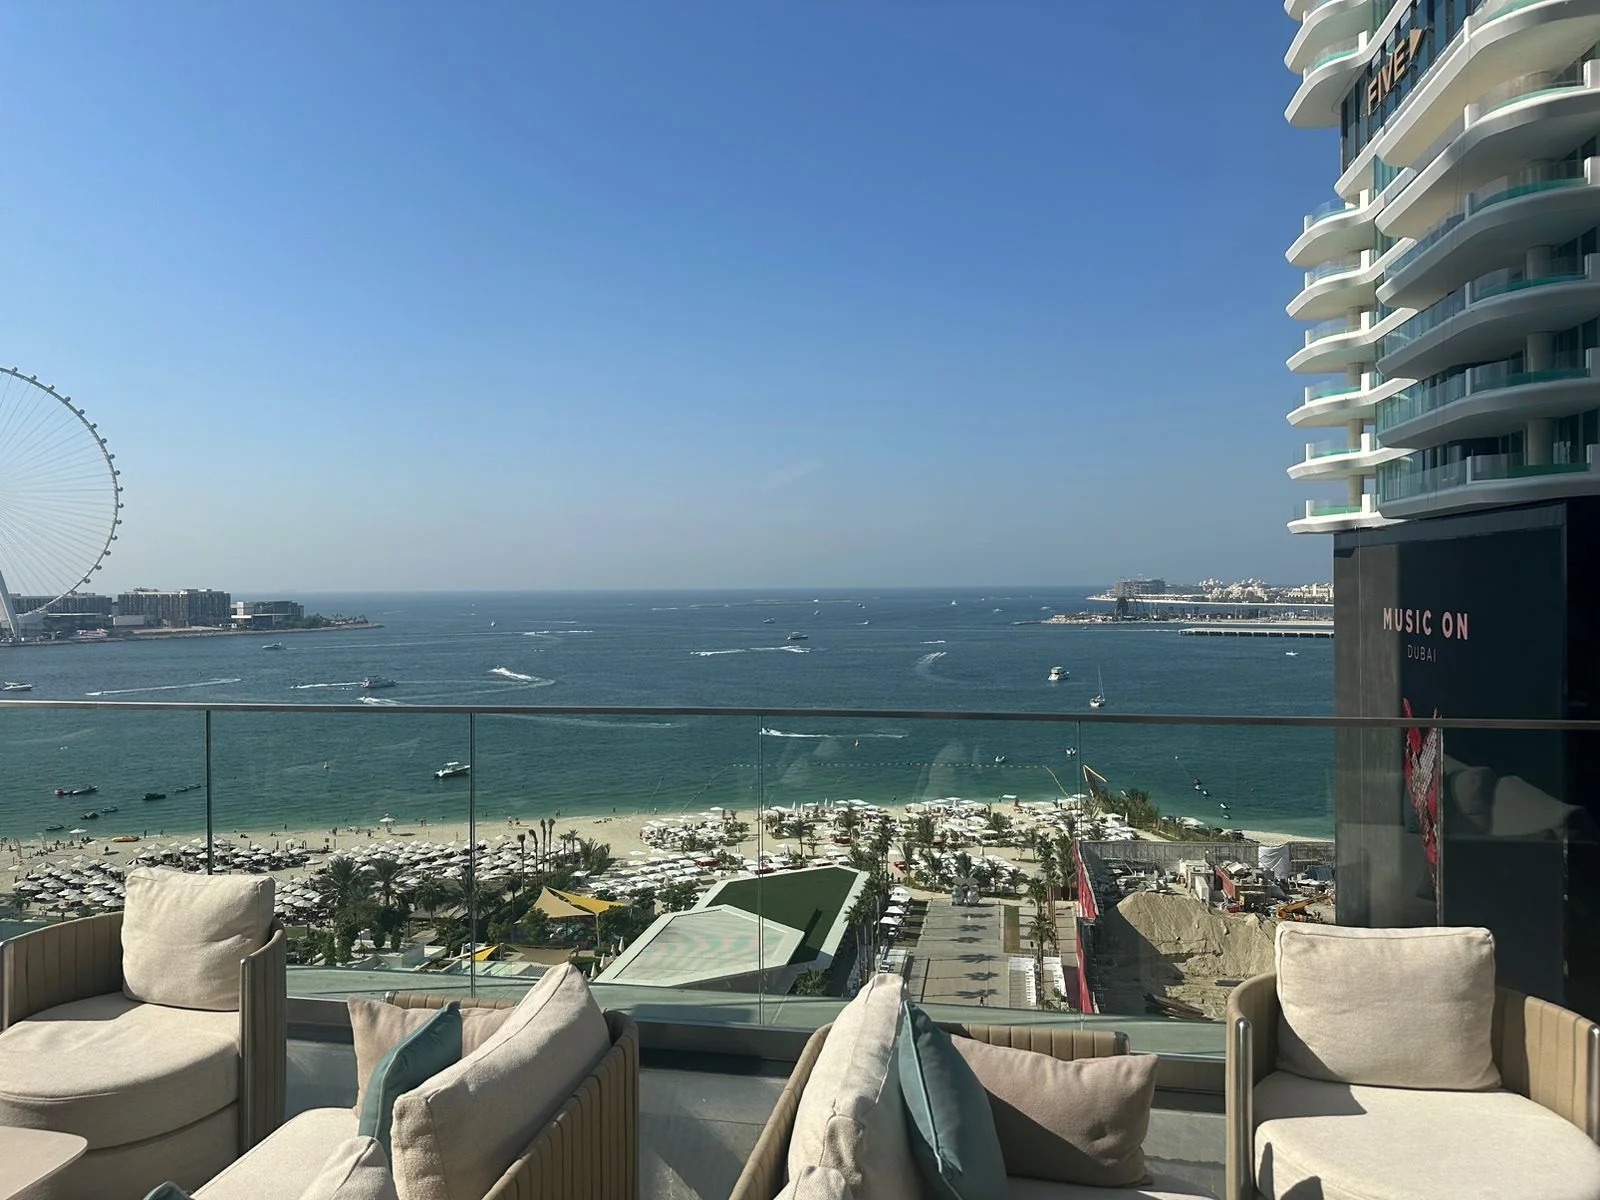
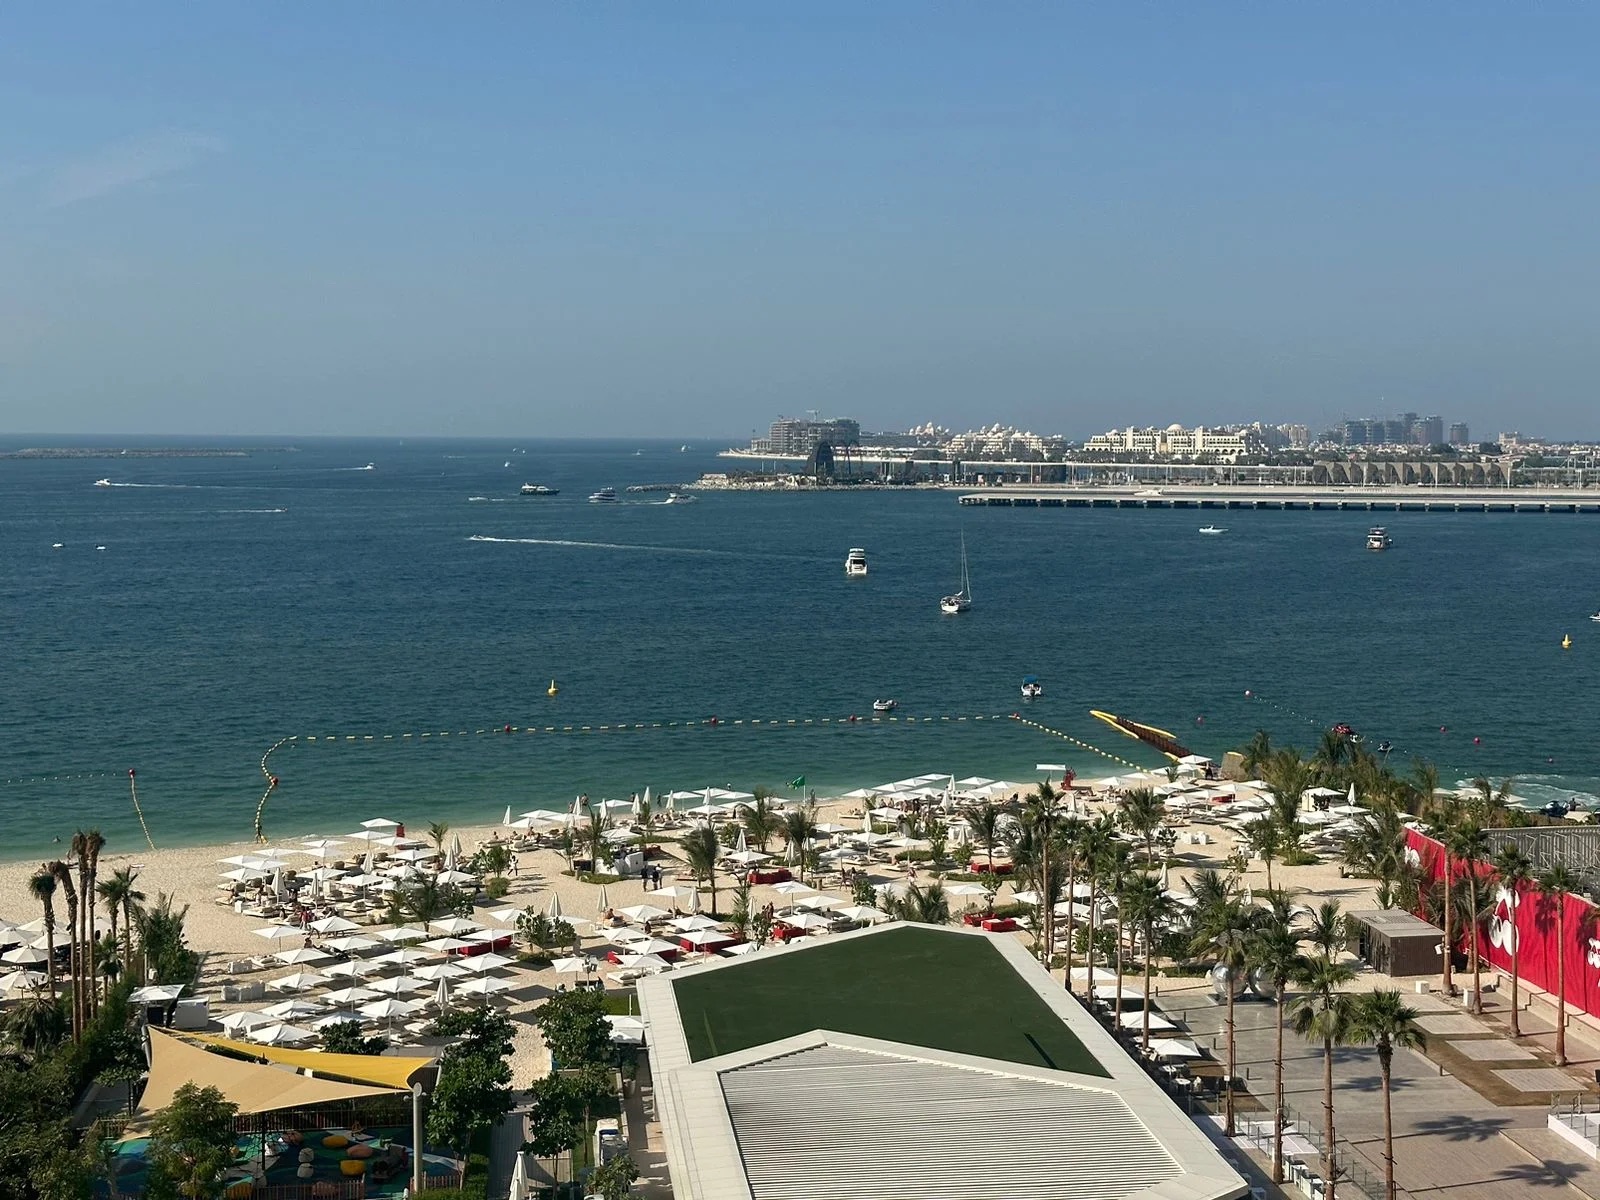
Jumeirah Beach Residence is one of the most established waterfront addresses in Dubai and, unlike the newer districts, it is fully mature: the beach, The Walk, The Beach retail strip and the tram all exist and have done for years. Five Luxe sits at the northern end of JBR, facing the open sea with Bluewaters Island and Ain Dubai immediately to the north and Palm Jumeirah across the water to the west. The Dubai Tram runs through JBR and connects to the Red Line metro at Jumeirah Lakes Towers and Dubai Marina, making this one of the few genuinely beachfront Dubai addresses with rail access. Sheikh Zayed Road is a few minutes inland. For a landlord, that combination of beach, retail and transit is what underpins JBR's rental depth in both the long-let and holiday-let markets.
AMENITIES & SURROUNDING
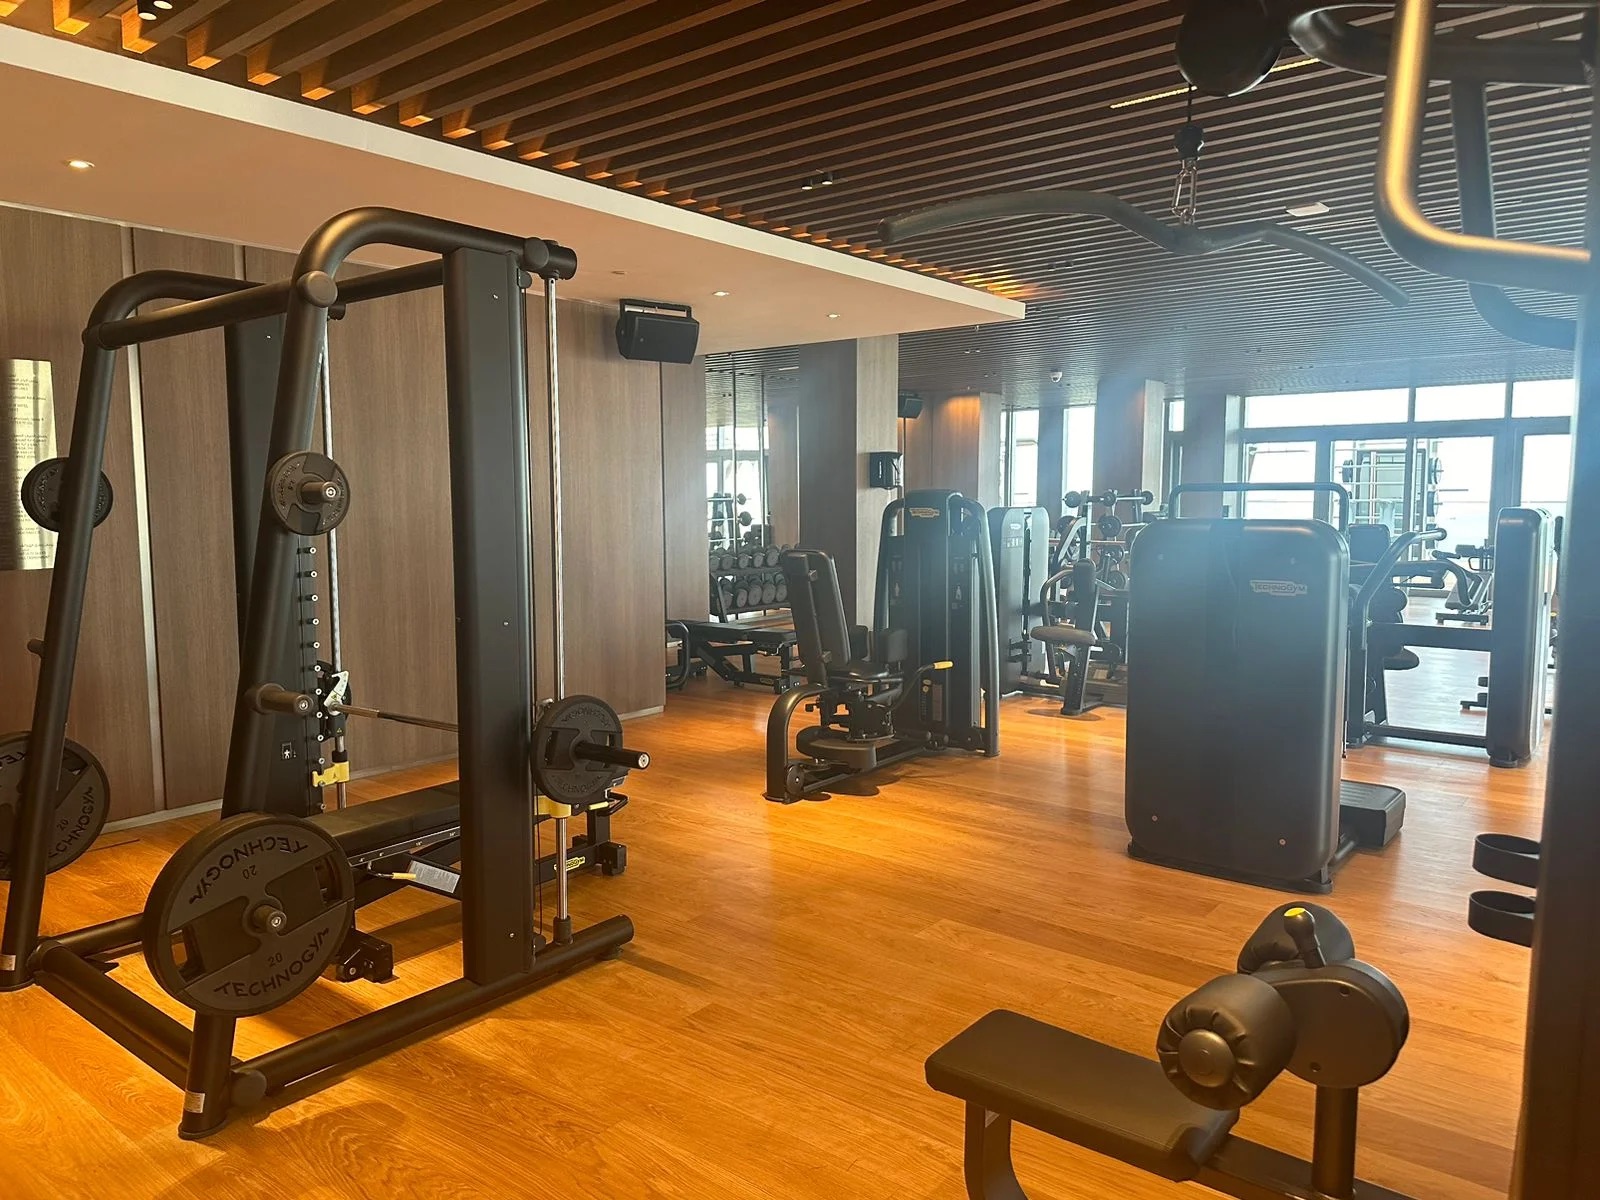
Five Luxe is the newest of the FIVE-branded properties on the JBR beachfront, developed by Devco and operating on the hospitality-led model the brand is known for. That has direct consequences for an owner: buildings of this type typically carry higher service charges than unbranded stock, and equally typically support higher nightly and monthly rates, so the yield question turns on which of the two moves further. A high-floor unit with both a sea and a Palm aspect is the configuration that commands the premium within the building, and it is also the configuration with the deepest resale audience. The immediate surroundings need little development: The Walk and The Beach are at the foot of the building and the beach itself is directly in front.
MARKET
At AED 4,679 per sq.ft this sits below the AED 5,420 per sq.ft implied by the stated market price of AED 8,690,000 on the same 1,603 sq.ft. That is the whole of the discount claim and it is measured against market rather than an original contract price, because the unit is complete. JBR's ready two-bedroom market is liquid by Dubai standards, which cuts both ways: a buyer can verify the level against genuine comparables rather than relying on a developer's list price, and a seller has fewer places to hide an inflated reference. The risks are the ones that attach to branded ready stock — service charges at the upper end, and a holiday-let income stream that is more sensitive to tourism cycles than a standard long let. Against that, the property can be inspected, valued and let immediately, with no construction risk at all.
CONCLUSION
This suits a buyer who wants income from day one on a mature beachfront address and is prepared to pay branded-residence running costs to get it. The 13.7% is below market, not below an original price, and that distinction matters: it is a claim about today's comparables rather than about what a first buyer once contracted to pay. The two figures to establish before proceeding are the current service charge per square foot and, if the intention is short-let, the building's policy on it.
Location
FIVE LUXE — Jumeirah Beach Residence, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 2-BR IN FIVE LUXE behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
The date this listing was added to our records. The asking price below is the one published then, and is not re-checked against the market automatically — confirm it with us before relying on it.
The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 7,957,500 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 7,342,500 | AED 7,342,500 |
| Years 1–5 | AED 0 | AED 7,342,500 | AED 7,342,500 |
| Less the year-0 outflow of AED 7,957,500 → total profit | −AED 615,000 | ||
Exit at year 5: illustrative sale price AED 7,500,000 less selling costs AED 157,500 = AED 7,342,500 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 5.80M | — | — | — |
| −3% p.a. | AED 6.44M | — | — | — |
| 0% p.a.your figure | AED 7.50M | — | — | — |
| 3% p.a. | AED 8.69M | — | — | — |
| 5% p.a. | AED 9.57M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Bu Kadra
DISTRESS DEAL: 1-BR IN SOBHA ONE - TOWER D
- Size
- 540 sq.ft
- Price / sq.ft
- AED 2,093
- Developer
- Sobha
Downtown Dubai
DISTRESS DEAL: 2-BR IN BINGHATTI SKYBLADE
- Size
- 1,260 sq.ft
- Price / sq.ft
- AED 3,730
- Developer
- Binghatti
Business Bay
DISTRESS DEAL: 1-BR IN BINGHATTI SKYRISE - TOWER C
- Size
- 966 sq.ft
- Price / sq.ft
- AED 1,760
- Developer
- Binghatti
- Handover
- Q1 2028
Maritime City
DISTRESS DEAL: 1-BR IN SARIA
- Size
- 829 sq.ft
- Price / sq.ft
- AED 2,051
- Developer
- Beyond
- Handover
- Q1 2028
City Walk
DISTRESS DEAL: 1-BR IN VERVE - TOWER B
- Size
- 834 sq.ft
- Price / sq.ft
- AED 2,698
- Developer
- Meraas
- Handover
- Q1 2028
Dubai Design District
DISTRESS DEAL: 2-BR IN DESIGN QUARTER - TOWER A
- Size
- 1,184 sq.ft
- Price / sq.ft
- AED 2,428
- Developer
- Meraas
- Handover
- Q1 2027
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.