Palm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,145/sqftDowntown Dubai AED 2,884/sqftDubai Islands AED 2,775/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,499/sqftDubai Marina AED 2,476/sqftDubai Hills Estate AED 2,460/sqftJumeirah Lakes Towers AED 2,323/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,054/sqftJumeirah Village Triangle AED 1,656/sqftDubai South AED 1,652/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,326/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,145/sqftDowntown Dubai AED 2,884/sqftDubai Islands AED 2,775/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,499/sqftDubai Marina AED 2,476/sqftDubai Hills Estate AED 2,460/sqftJumeirah Lakes Towers AED 2,323/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,054/sqftJumeirah Village Triangle AED 1,656/sqftDubai South AED 1,652/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,326/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO OCT 2026

Distress Deal

DISTRESS DEAL: 1-BR IN SOBHA ONE - TOWER D

Available
Listed 31 October 2026

Available when we last checked. The asking price shown is the one published when the listing was added on 31 October 2026, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.

Interested in distressed property deals?

Ask us anything about this one — the asking price, the payment terms, the running costs, or how it compares with what else is trading nearby. A member of the Mitchell's team will come back with a straight answer and a clear next step. It takes under a minute, and there's no obligation.

Choose one — the next questions adapt to your answer.

On this page

Quick navigation

The numbers

Payment breakdown

Total cost for buyerAED 1,212,594The unit price plus the transfer fees and commission — the whole commitment, not the headline.
Unit priceAED 1,130,000
Fees and commissionAED 82,594
Step 01Due at transferAED 676,855Payable when the unit transfers to the buyer.
  • Payment to sellerAED 594,261
  • DLD Transfer fee (4% of OP + 40 AED)AED 53,614
  • Trustee Office FeeAED 5,250
  • Buyer's Agency Commission (2% + VAT)AED 23,730
  • Total on transferAED 676,855
Step 02Payable to Sobha after transferAED 535,739The balance of the payment plan, which the buyer takes over.
  • On HandoverAED 535,739
  • Total remaining payment planAED 535,739

Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.

Ask about these terms

Unit details

Property type
Apartment
View
Canal
Balcony
Yes
Handover
FEB 2027

Distress Deal

PROJECT DESCRIPTION

OVERVIEW

The property is a one-bedroom apartment in Sobha One - Tower D, a Sobha development in Bu Kadra. The stated size is 540 sq.ft. The listing records a canal view and a balcony. The scheme is off-plan, and handover is scheduled for FEB 2027.

The asking price is AED 1,130,000. The original price plus the 4% DLD fee is AED 1,392,920, so the reduction is AED 262,920, or 18.9% below original price. On the stated size the price works out at AED 2,093 per sq.ft, against AED 2,579 per sq.ft at the original price plus DLD. At transfer the buyer pays AED 676,855, of which AED 594,261 goes to the seller. The balance of AED 535,739 falls due to the developer on handover, with no instalment before it. The transfer rows and the handover payment above add up to a total cost for the buyer of AED 1,212,594.

The layout opens from the entrance into a hall that leads to an open kitchen and dining area. The living area sits beyond it and opens onto the balcony. The bedroom sits to one side, with fitted wardrobes and glazing onto the balcony. The bathroom opens off the hall, and a utility cupboard sits next to the kitchen.
LOCATION & TRANSPORT

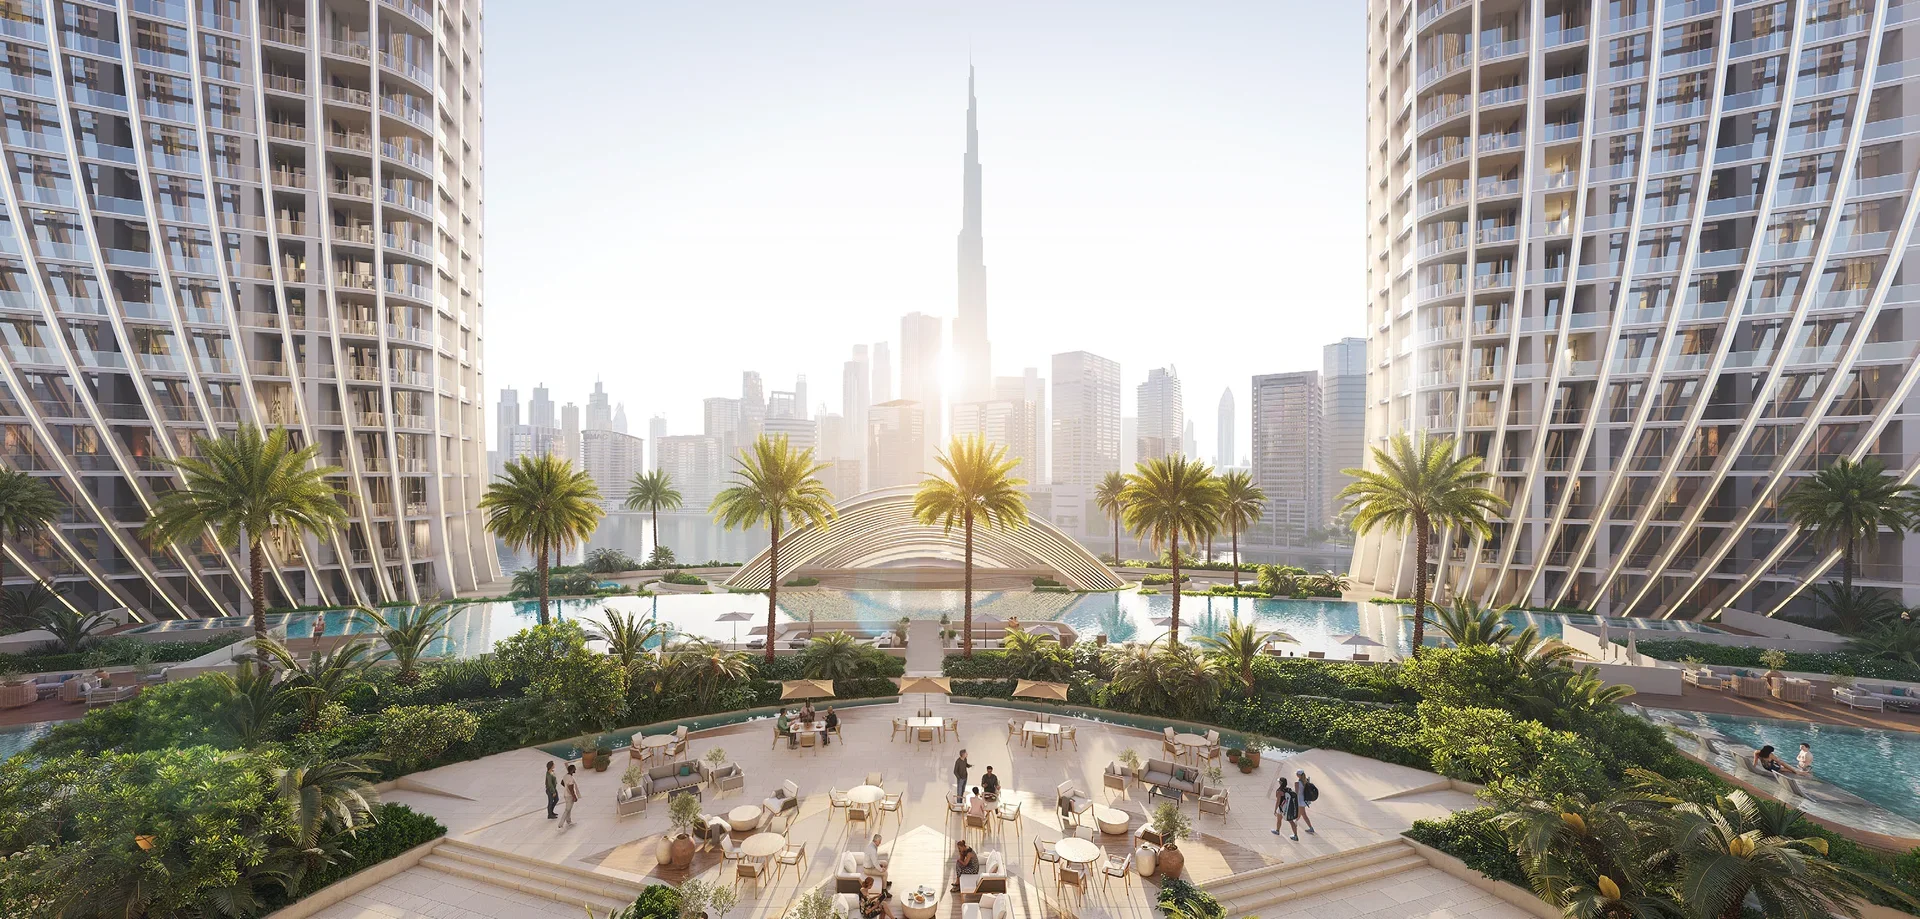
Sobha One - Tower D sits in Bu Kadra, the sub-community recorded for this unit. The listing records a canal view. A buyer who values that outlook should confirm the unit's orientation with the developer before signing.

Travel is best judged against the buyer's own routine. The commute to work, the school run and other regular journeys each depend on where the buyer needs to be. We suggest driving those routes at peak hours before committing. Public transport options should be checked on the current RTA journey planner.

Handover is scheduled for FEB 2027. A buyer who plans to live in the unit should ask the developer how residents will reach the building at handover.

AMENITIES & SURROUNDING

The scheme is off-plan, so the shared facilities remain a commitment from the developer until handover. The amenity list that binds the developer is the one in the SPA and its schedules. A buyer should read that list and treat it as the reference for what the building will provide.

Inside the apartment, the layout works as a self-contained one-bedroom home. The balcony is reached from the living area, and the bedroom has fitted wardrobes. The utility cupboard keeps household storage out of the living space.

A buyer should visit Bu Kadra and check shops, schools, clinics and gyms against daily needs. The listing records a canal view, and the balcony gives the apartment its own outdoor space.

MARKET

The reduction is measured against the original price plus the 4% DLD fee. On that basis the apartment is offered at 18.9% below original price, or AED 486 per sq.ft below the original rate on the stated size. The stated size is 540 sq.ft, and handover is scheduled for FEB 2027.

The DLD transfer fee is AED 53,614. Because the asking price sits below the original price, the fee is struck on the original price, at 4% plus AED 40. The trustee office fee is AED 5,250 and the buyer's agency commission, at 2% plus VAT, is AED 23,730. Those items and the AED 594,261 payment to the seller make up the AED 676,855 due at transfer. The payment to the seller and the balance on handover together equal the asking price.

CONCLUSION

The apartment suits a buyer who wants a one-bedroom unit in Bu Kadra from Sobha, with a canal view, a balcony and a single payment left to make on handover in FEB 2027. It also suits an investor who prefers to pay the larger share at transfer and the remainder on handover, with an entry price 18.9% below original price.

AED 676,855 is paid at transfer and AED 535,739 on handover, for a total cost of AED 1,212,594 across the rows above. Before terms are agreed, a current statement of account should be obtained from the developer to confirm the amount paid to date and the balance outstanding. The buyer should also ask the developer to set out the Oqood transfer steps.

Location

SOBHA ONE - TOWER D — Bu Kadra, Dubai

Get Directions

Illustrative model

Scenario modeller

Set your own assumptions and see how DISTRESS DEAL: 1-BR IN SOBHA ONE - TOWER D behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.

Listed
31 October 2026

The date this listing was added to our records. The asking price below is the one published then, and is not re-checked against the market automatically — confirm it with us before relying on it.

Below original price
18.9%

As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.

Asking price per sq.ft
AED 2,093/sqft

The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.

Purchase

Seeded from this page. Change it to your figure.

Drives the service charge only.

Rent and service charge both start here.

Holding & income

Your figure. We have not assumed one.

0% holds rent flat. It may be negative.

Your figure — we publish none. A month vacant plus re-letting time is roughly 8%, if that fits your building.

Your figure — we publish none. Letting fees and routine repairs.

Your figure — we publish none. Look your building up on Mollak — rates run AED 3 to AED 30+.

Acquisition costs

4% is the Dubai standard.

Buyer-side. 5% VAT added.

Your figure — we publish none. The trustee tariff is tiered and the admin lines vary by office; ask your trustee office for the total, and add your NOC and any legal quote.

Exit

1 to 40 years.

0% by default: we publish no price forecasts.

5% VAT added automatically.

Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 1.20M
Price plus every acquisition cost
Illustrative exit price
AED 1.13M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
—
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
—
Set a gross annual rent
Cash out, and cash back over 5 years
Cash out at t0AED 1,198,930
Cash back, years 1–5—

Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.

Cash required at completion
Purchase priceAED 1,130,000
DLD transfer fee (4%)AED 45,200
Agency fee (2%)AED 22,600
VAT on agency fee (5%)AED 1,130
Conveyancing, trustee & adminAED 0
Total cash investedAED 1,198,930

ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.

No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.

Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)—
Maintenance & management (not set)—
Service charge (540 sq ft at a rate not yet set)—
Net operating income—

Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.

Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
YearNet operating incomeSale proceeds, netNet cash flow
0 · today——−AED 1,198,930
1AED 0—AED 0
2AED 0—AED 0
3AED 0—AED 0
4AED 0—AED 0
5AED 0AED 1,106,270AED 1,106,270
Years 1–5AED 0AED 1,106,270AED 1,106,270
Less the year-0 outflow of AED 1,198,930 → total profit−AED 92,660

Exit at year 5: illustrative sale price AED 1,130,000 less selling costs AED 23,730 = AED 1,106,270 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.

Sensitivity — the same purchase at −5% to +5% exit growth
Exit growthExit priceTotal profitROIIRR
−5% p.a.AED 874k———
−3% p.a.AED 970k———
0% p.a.your figureAED 1.13M———
3% p.a.AED 1.31M———
5% p.a.AED 1.44M———

Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.

Method
Handover
The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
Gross yield
Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
Net yield
(Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
Rent growth
Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
ROI
Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
ROE
Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
Cash-on-cash return
Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
IRR
The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.

Email my results

We’ll send this scenario — your assumptions and the figures they produce — to your inbox.

Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.

An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.

Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.

Got questions?

Get Answers!

Read next

A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.

The gold rule under an entry is its length, against the longest piece here.

Guides

Articles

Need help?