

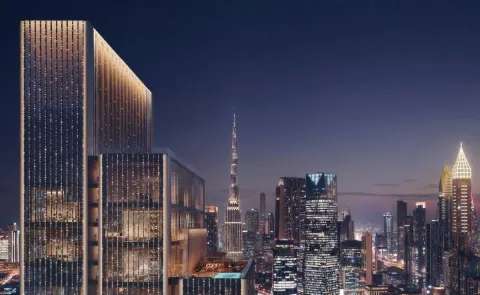
Luxury Listing
Two-Bedroom Apartment, Jumeirah Residences Emirates Towers, DIFC, 1,373 sq ft (third listing)
- Off-plan
AED 8,354,750, as listed on 7 October 2026
Jumeirah Residences Emirates Towers, DIFC

What is the asking price?
AED 8,354,750, as listed on 7 October 2026
Source: Owner's asking price as listed on 7 October 2026; captured 23 October 2026
Of this, AED 3,995,750 is payable to the seller; the balance is paid to the developer under the existing payment plan.
AED 6,085 per sq ft, on the recorded sq ft.
Pictures
What exactly is for sale?
- Type
- Apartment
- Status
- Off-plan
- Availability
- Available
- Bedrooms
- 2 bedrooms
- Size
- 1,373 sq ft
- View
- Burj Khalifa View
- Payment plan
- In place
- Development
- Jumeirah Residences Emirates Towers
- Community
- DIFC
Floor plan
About this unit
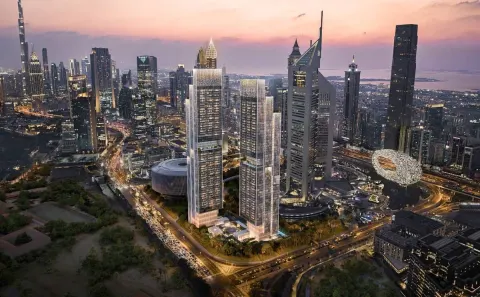
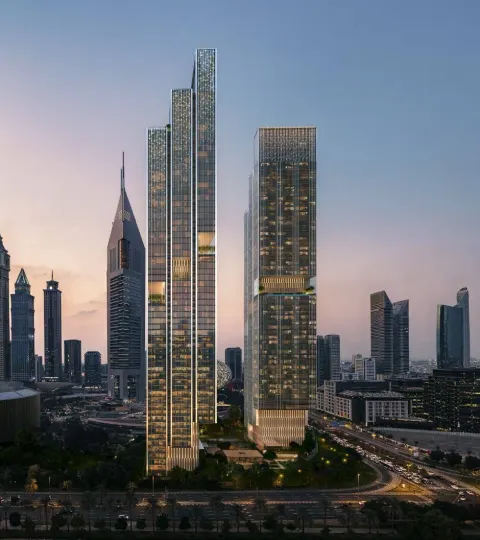
Jumeirah Residences Emirates Towers is a landmark residential project in DIFC, Dubai's prestigious business district, developed by Dubai Holding and managed with Signature Jumeirah services. This two-bedroom apartment in Tower A (type B2) offers 1,373 sqft (128 sqm) of total area with Burj Khalifa views. Estimated completion is Q3 2030.
The layout includes a primary bedroom with an en-suite bathroom, a second bedroom with its own bathroom, a maid's room with a bathroom, an open kitchen, a living and dining area, and a balcony. The project is designed with iconic architecture and hotel-style living.
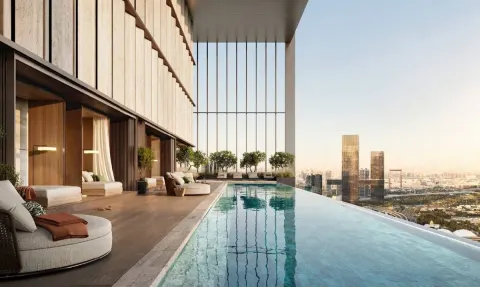
Residents have access to adults-only and family pools, a spa, a gym, private dining, sky terraces, a padel court and a 24/7 concierge. The payment plan to the developer runs in instalments from February 2027, with the final 100% of construction payment due in August 2030.
DIFC offers direct access to Dubai Mall and the Metro.
Where is it?
Jumeirah Residences Emirates Towers is in DIFC.
Location
Jumeirah Residences Emirates Towers — DIFC, Dubai
Illustrative model
Model this purchase
Set your own assumptions and see how Two-Bedroom Apartment, Jumeirah Residences Emirates Towers, DIFC, 1,373 sq ft (third listing) behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
The owner's asking price as listed on 7 October 2026, as published on this listing. Not a valuation.
As stated on this listing.
As published on this listing. The model below assumes the purchase price and all acquisition costs are paid at the outset; a staged plan defers part of the outlay, which raises the IRR on the same total profit. Treat the return figures as the unstaged case.
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is attached to this listing. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 8,864,390 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 8,179,300 | AED 8,179,300 |
| Years 1–5 | AED 0 | AED 8,179,300 | AED 8,179,300 |
| Less the year-0 outflow of AED 8,864,390 → total profit | −AED 685,090 | ||
Exit at year 5: illustrative sale price AED 8,354,750 less selling costs AED 175,450 = AED 8,179,300 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 6.46M | — | — | — |
| −3% p.a. | AED 7.17M | — | — | — |
| 0% p.a.your figure | AED 8.35M | — | — | — |
| 3% p.a. | AED 9.69M | — | — | — |
| 5% p.a. | AED 10.7M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
This unit is off-plan: set the time to handover below to the date the developer confirms. Rent and the service charge both start at handover.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
How does the purchase proceed?
- You agree terms with the owner through us. We act for you, the buyer.
- The developer's consent to the transfer is obtained, in the form of a no-objection certificate (NOC).
- The change of buyer is registered with the Dubai Land Department in the Interim Property Register (Oqood). From the date of transfer you take over what remains of the contract with the developer.
The transfer is explained step by step on our Luxury Listings hub, together with what the transfer costs.
