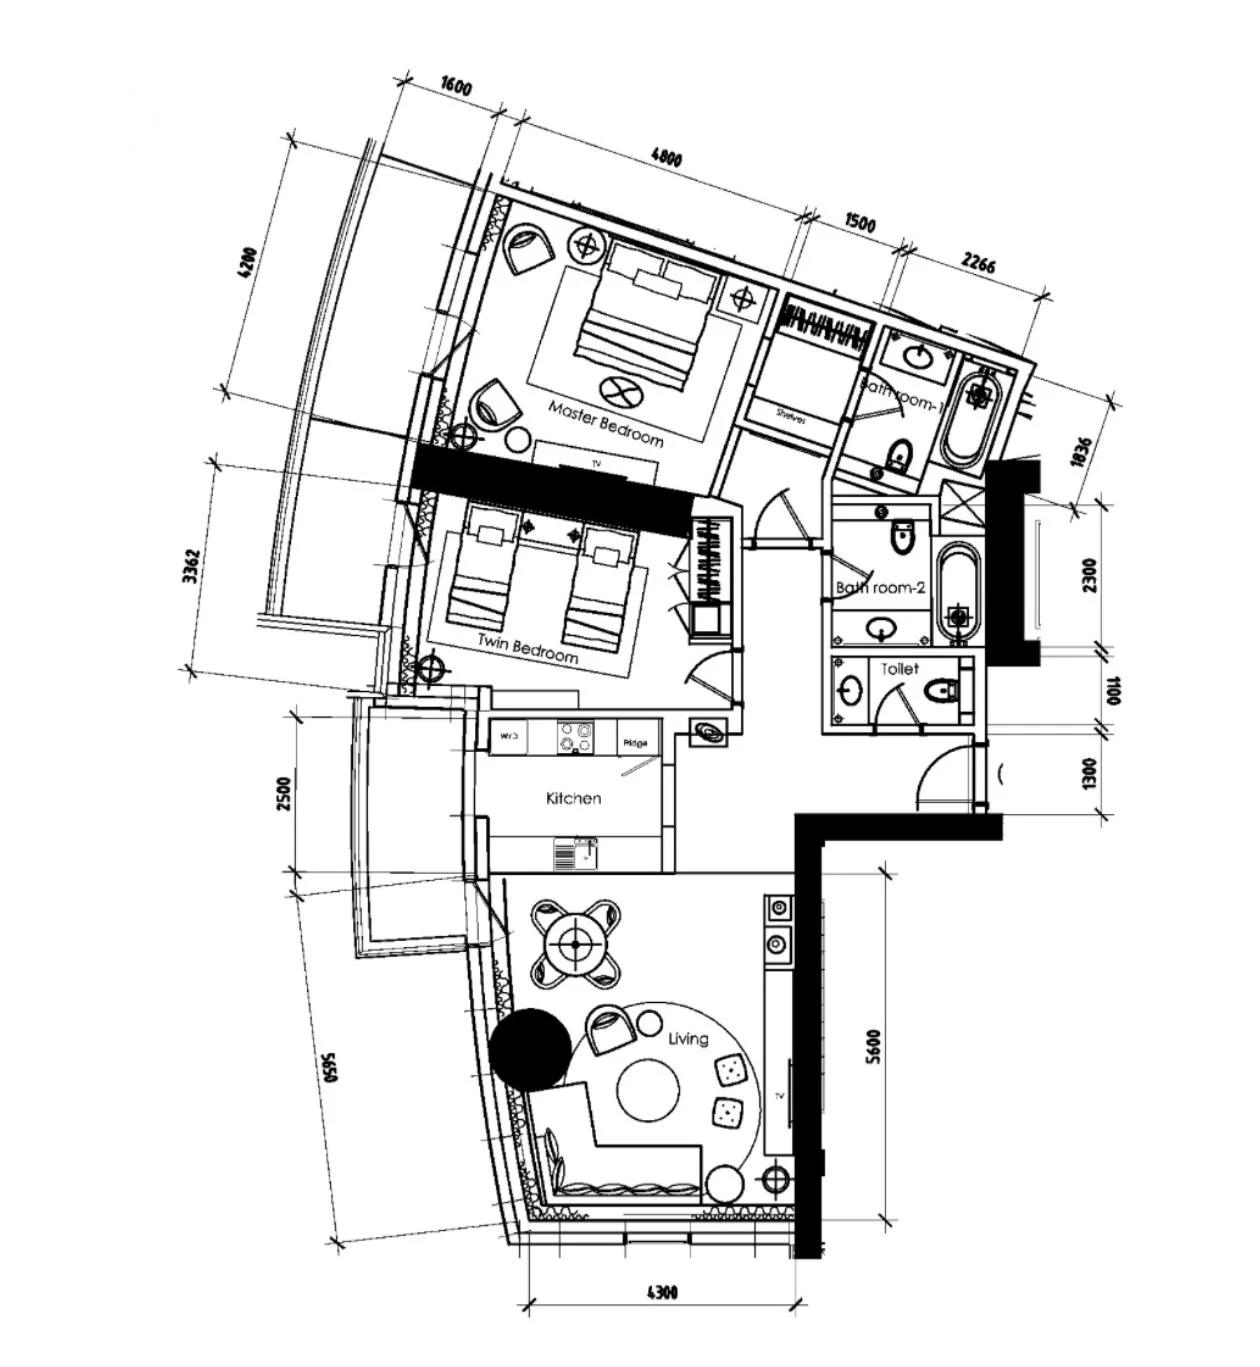
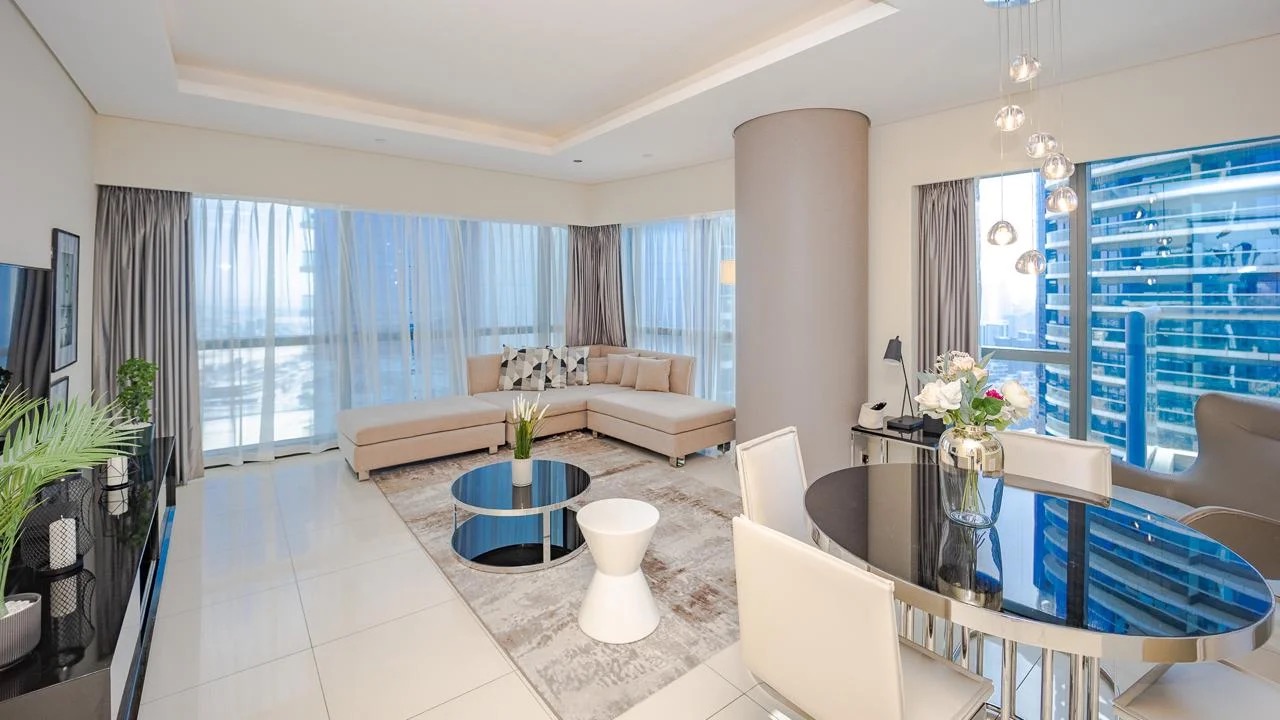
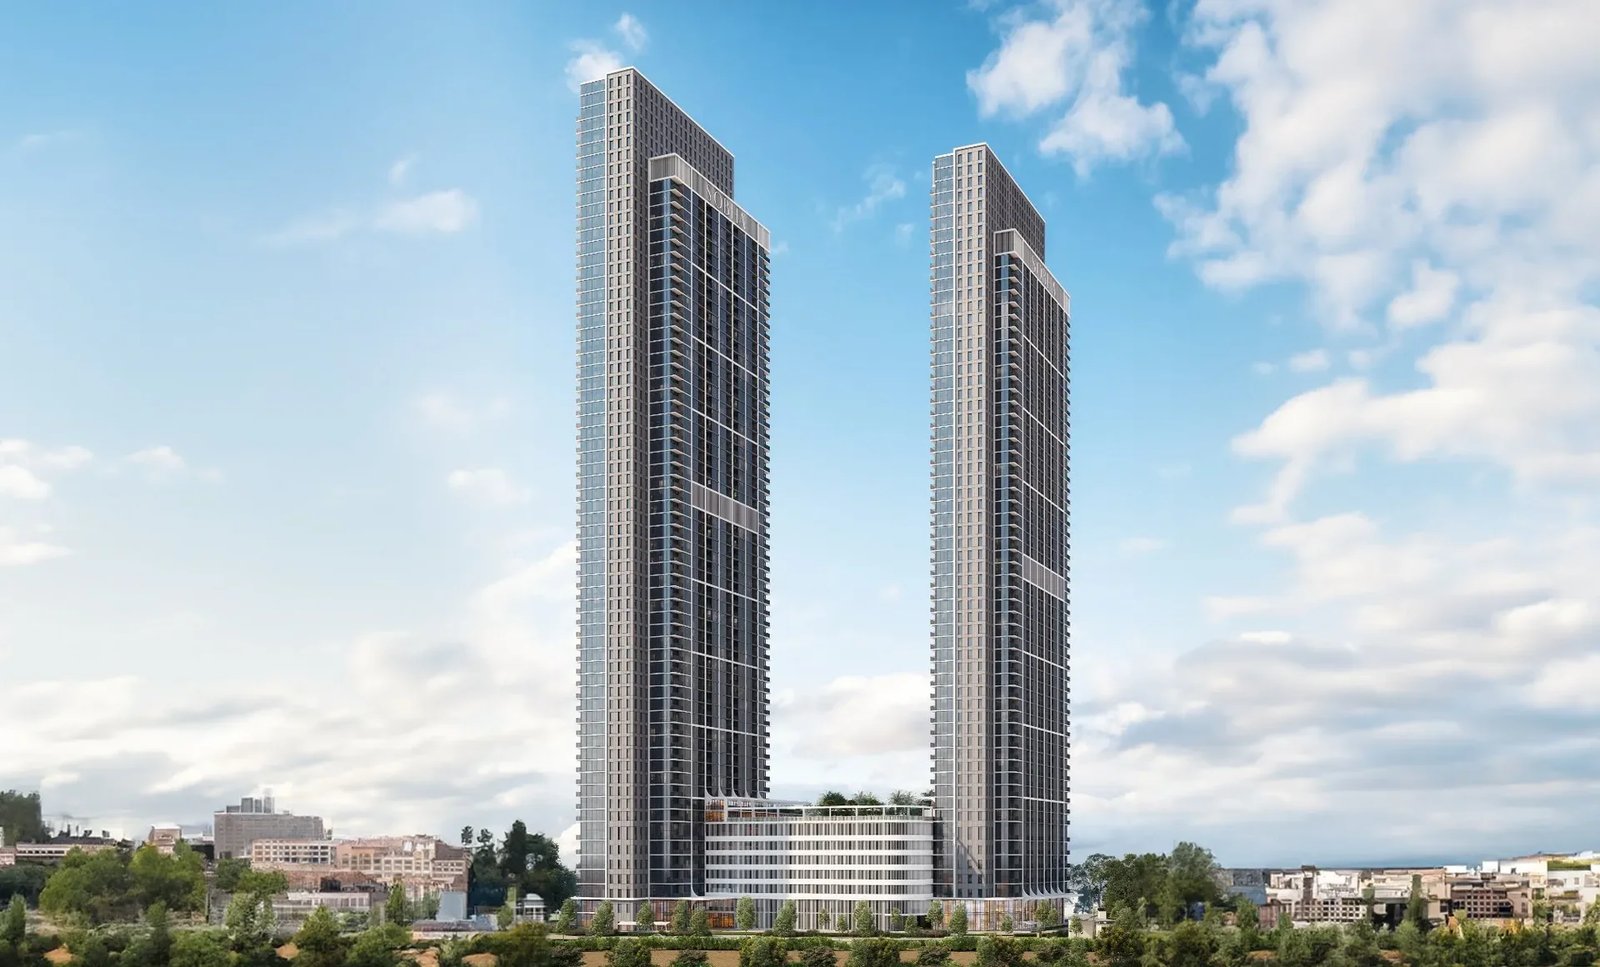
This two-bedroom apartment in Paramount Tower D, Business Bay, is offered at AED 2,000,000 against an original price plus DLD of AED 2,735,200 — AED 735,200, or 26.9%, below original price. The unit is fully furnished, 1,516 sq.ft of built-up area, which gives AED 1,319 per sq.ft on BUA. It sits on a high floor with a Burj Khalifa view and has a balcony. The property is complete and vacant, so there is no developer balance and no handover to wait for: the full AED 2,000,000 goes to the seller at transfer, and with the DLD, trustee, agency and title deed fees the total cost to the buyer is AED 2,152,020. The unit is ready, and the discount is measured against the original price plus DLD, the reference the source carries for this unit.
Available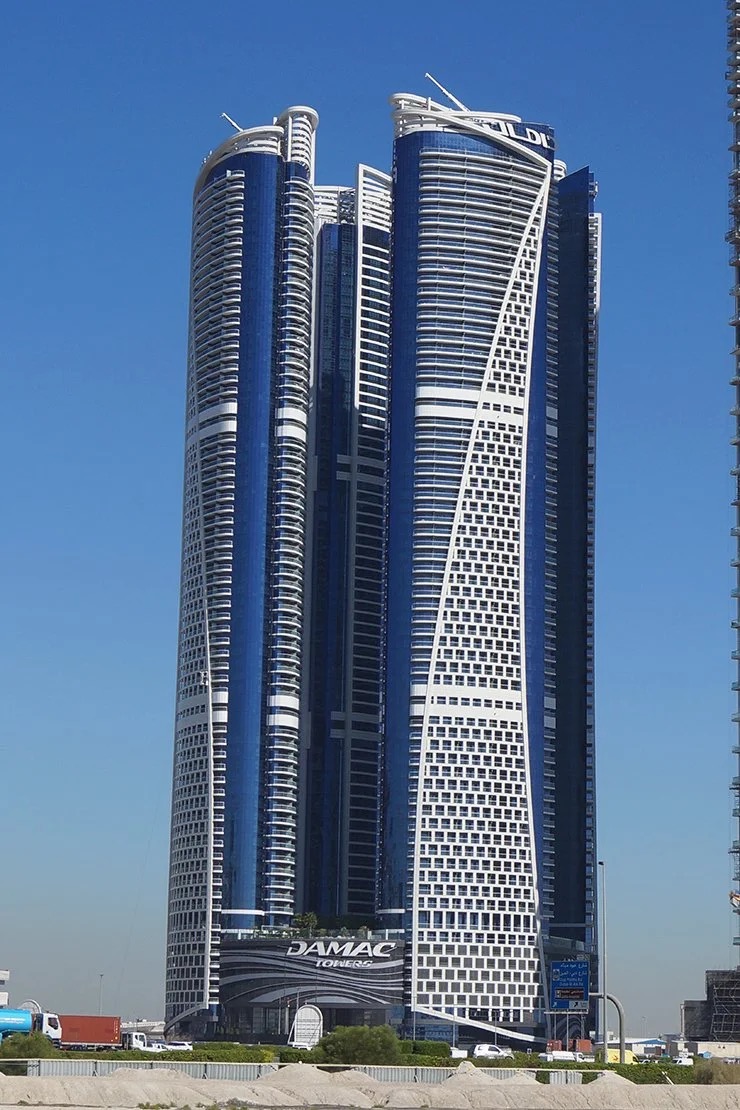 PARAMOUNT TOWER D · Business Bay1 / 3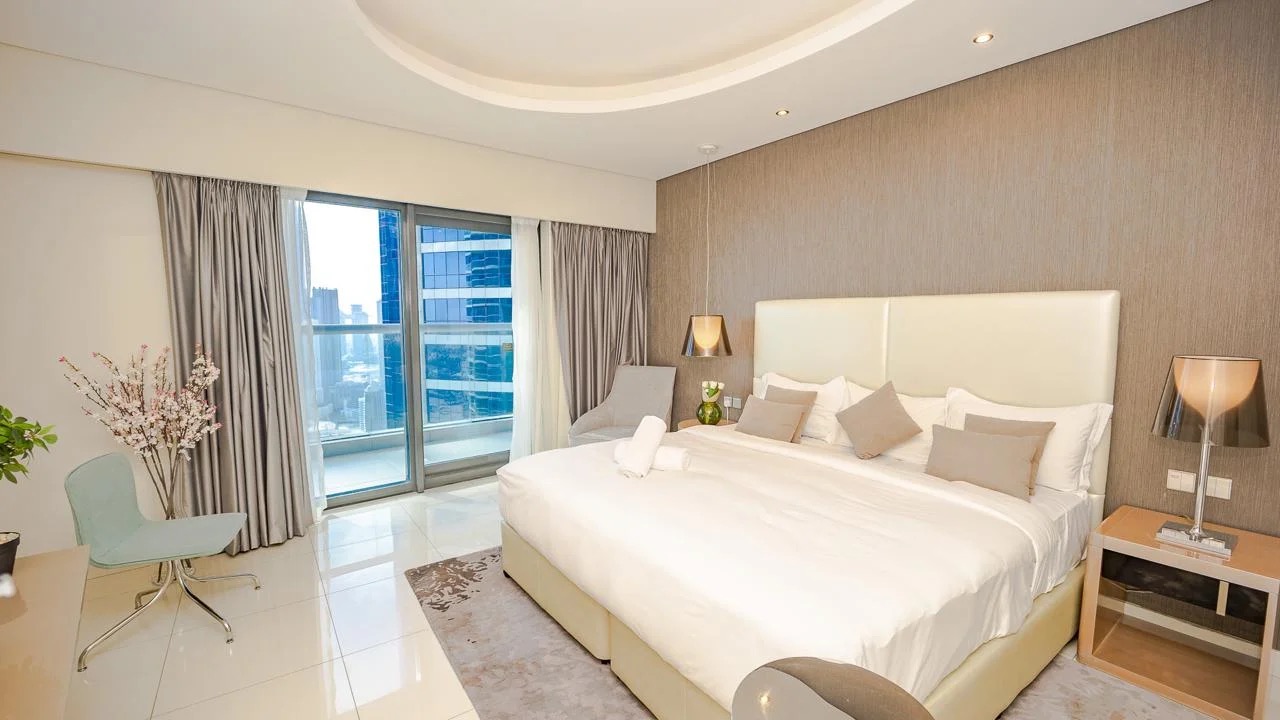
Damac · Business Bay
DISTRESS DEAL: 2-BR IN PARAMOUNT TOWER D
Asking priceAED 2,000,000,AED 1,319 per sq.ft
Original price + DLDAED 2,735,200
DiscountAED 735,20026.9% below original price
- Unit
- 2-BR
- Size
- 1,516 sq.ft
- Developer
- Damac
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
Available
Listed 28 September 2026
Available when we last checked. The asking price shown is the one published when the listing was added on 28 September 2026, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.
On this page
Quick navigation
The numbers
Payment breakdown
Total cost for buyerAED 2,152,020The unit price plus the transfer fees and commission — the whole commitment, not the headline.
Unit priceAED 2,000,000
Fees and commissionAED 152,020
At transferDue at transferAED 2,152,020Payable when the unit transfers to the buyer.
- Payment to sellerAED 2,000,000
- DLD Transfer fee (4% of OP + 40 AED)AED 105,240
- Trustee Office FeeAED 4,200
- Buyer's Agency Commission (2% + VAT)AED 42,000
- Title Deed FeeAED 580
- Total on transferAED 2,152,020
Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.
Ask about these termsUnit details
- Property type
- Apartment
- Floor
- High
- View
- Burj Khalifa
- Features
- Balcony
- Handover
- Ready
Photography
Gallery
Layout
Floor plan
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
Business Bay sits immediately south of Downtown Dubai, on the far side of the Dubai Water Canal from the Burj Khalifa and Dubai Mall, which is the view this unit carries. Sheikh Zayed Road runs along the district's western edge and gives direct access north to Downtown, DIFC and the airport, and south to Dubai Marina and the wider coast. Al Khail Road runs behind the towers and connects to Al Quoz and the outer ring roads without needing to touch Sheikh Zayed Road at all. The Business Bay metro station, on the Red Line, sits within the district, and the canal promenade runs along the water for the length of the community. For a tenant working in Downtown or DIFC, this is a short commute by road, metro or, increasingly, water taxi along the canal.
AMENITIES & SURROUNDING
Damac Towers by Paramount is a four-tower complex, Towers A to D, built on a shared podium and completed in 2018, according to the Dubai Land Department's project register. Tower D itself rises to 62 storeys. The development carries the Paramount Pictures brand and combines residential floors with hotel and hospitality operations, and the podium level holds restaurants, cafes and leisure space shared across the complex. The unit itself is finished in a neutral palette throughout, with floor-to-ceiling glazing in the living room and both bedrooms, mosaic-tiled bathrooms and a fitted wardrobe wall between the master bedroom and its en-suite. Both bedrooms open onto the skyline, and the master bedroom's balcony frames the Burj Khalifa directly. The kitchen is fitted with an integrated oven, hob, extractor and washer-dryer, and the living room's own balcony carries the same skyline aspect.
MARKET
What sets this listing apart is the payment structure rather than the price alone: because the unit is titled and vacant, the buyer pays once, at transfer, with nothing outstanding to a developer and no construction risk to underwrite. Business Bay's resale market is liquid by Dubai standards, which works in a seller's favour when it comes to letting or reselling the unit again. The branded-residence positioning typically carries a service charge premium against unbranded Business Bay stock, which a buyer should weigh against the hotel-style services and the Burj Khalifa view. Both the furnished condition and the vacant status support an immediate let, so the yield calculation can start from day one rather than from a projected handover date. Damac Towers by Paramount was completed in 2018, so the building carries an established service history rather than a newly formed one, and the four-tower complex gives the branded amenities a wider base of residents to draw on than a single-tower scheme would.
CONCLUSION
This suits a buyer who wants a furnished, high-floor two-bedroom in Business Bay with an unobstructed Burj Khalifa view and no construction timeline to manage. The AED 735,200 reduction is measured against the original price plus DLD, the reference for this ready and titled unit. The single payment at transfer removes the instalment planning that an off-plan purchase would require, and the property can be inspected, valued and let from the day it changes hands. Because the asking price sits below the original price, the DLD fee is calculated on the original price rather than the asking price, which sets the AED 2,152,020 total cost at transfer.
Location
PARAMOUNT TOWER D — Business Bay, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 2-BR IN PARAMOUNT TOWER D behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Listed
28 September 2026
The date this listing was added to our records. The asking price below is the one published then, and is not re-checked against the market automatically — confirm it with us before relying on it.
Below original price
26.9%
As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.
Asking price per sq.ft
AED 1,319/sqft
The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.
Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 2.12M
Price plus every acquisition cost
Illustrative exit price
AED 2M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
—
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
—
Set a gross annual rent
Cash out, and cash back over 5 years
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
Cash required at completion
Purchase priceAED 2,000,000
DLD transfer fee (4%)AED 80,000
Agency fee (2%)AED 40,000
VAT on agency fee (5%)AED 2,000
Conveyancing, trustee & adminAED 0
Total cash investedAED 2,122,000
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)—
Maintenance & management (not set)—
Service charge (1,516 sq ft at a rate not yet set)—
Net operating income—
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 2,122,000 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 1,958,000 | AED 1,958,000 |
| Years 1–5 | AED 0 | AED 1,958,000 | AED 1,958,000 |
| Less the year-0 outflow of AED 2,122,000 → total profit | −AED 164,000 | ||
Exit at year 5: illustrative sale price AED 2,000,000 less selling costs AED 42,000 = AED 1,958,000 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 1.55M | — | — | — |
| −3% p.a. | AED 1.72M | — | — | — |
| 0% p.a.your figure | AED 2M | — | — | — |
| 3% p.a. | AED 2.32M | — | — | — |
| 5% p.a. | AED 2.55M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Beachfront
DISTRESS DEAL: 1-BR IN DAMAC BAY 2 (779 SQ FT)
AED 3,278,080AED 2,585,000,Asking price
21.1%Below O.P.
- Size
- 779 sq.ft
- Price / sq.ft
- AED 3,318
- Developer
- Damac
- Handover
- Q4 2028
Beachfront
DISTRESS DEAL: 1-BR IN SOBHA SEAHAVEN - TOWER B
AED 3,270,492AED 2,900,000,Asking price
11.3%Below O.P.
- Size
- 850 sq.ft
- Price / sq.ft
- AED 3,412
- Developer
- Sobha
- Handover
- Q4 2028
Motor City
DISTRESS DEAL: 1-BR IN SOBHA SOLIS - TOWER B
AED 1,093,242AED 965,000,Asking price
11.7%Below O.P.
- Size
- 545 sq.ft
- Price / sq.ft
- AED 1,771
- Developer
- Sobha
Sobha Hartland II
DISTRESS DEAL: 2-BR IN 330 RIVERSIDE CRESCENT
AED 2,271,998AED 2,200,000,Asking price
3.2%Below O.P.
- Size
- 946 sq.ft
- Price / sq.ft
- AED 2,326
- Developer
- Sobha
Business Bay
DISTRESS DEAL: 4-BR IN PENINSULA 4 THE PLAZA B - HIGH FLOOR
AED 8,008,000AED 7,150,000,Asking price
10.7%Below O.P.
- Size
- 2,688 sq.ft
- Price / sq.ft
- AED 2,660
- Developer
- Select Group
Sobha Hartland
DISTRESS DEAL: 1-BR IN SOBHA CREEK VISTA HEIGHTS - TOWER B
AED 1,731,976AED 1,460,000,Asking price
15.7%Below O.P.
- Size
- 853 sq.ft
- Price / sq.ft
- AED 1,712
- Developer
- Sobha
- Handover
- Q1 2027
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.