Palm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO SEP 2026
DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLAS

Distress Deal

DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLAS

Asking PriceAED 23,500,000
Below Original Price10.7%
Size13,006 sq.ft
Bedrooms6
Price / Sq.FtAED 1,807
HandoverQ3 2027
Sold
Listed 21 May 2026Status confirmed 3 August 2026

This unit has sold and is no longer available. The page is kept as a record of a deal we transacted. Every figure on it — the asking price, the discount to original price and the payment schedule — is the position as listed on 21 May 2026 and is historic. It is not an indication of what the same unit, or a comparable one, would cost today.

Looking for something like DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLAS?

This unit has sold. Tell us the size, area and budget you're working to and a member of the Mitchell's team will come back with the stock that currently matches. It takes under a minute, and there's no obligation.

Choose one — the next questions adapt to your answer.

Scan or tap to message Mitchell's on WhatsAppScan or tap to chat

Prefer to connect directly?

On this page

Quick navigation

The numbers

Payment breakdown

UNIT PRICE AED 23,500,000

PAYMENTS ON TRANSFER

1. Payment to seller AED 10,842,000
2. DLD Transfer fee 4% + 40 AED AED 940,040
3. DLD Registration Trustee fee + 5%VAT AED 5,250
4. Buyer's agent commission 2% + 5%VAT AED 504,000

PAYMENT PLAN SCHEDULE

01-JUN-2026 AED 1,265,800
01-SEP-2026 AED 1,265,800
On Handover AED 10,126,400

SUMMARY

Total on Transfer AED 12,280,790
Total remaining Payment Plan AED 12,658,000
TOTAL COST FOR BUYER AED 24,938,790

Layout

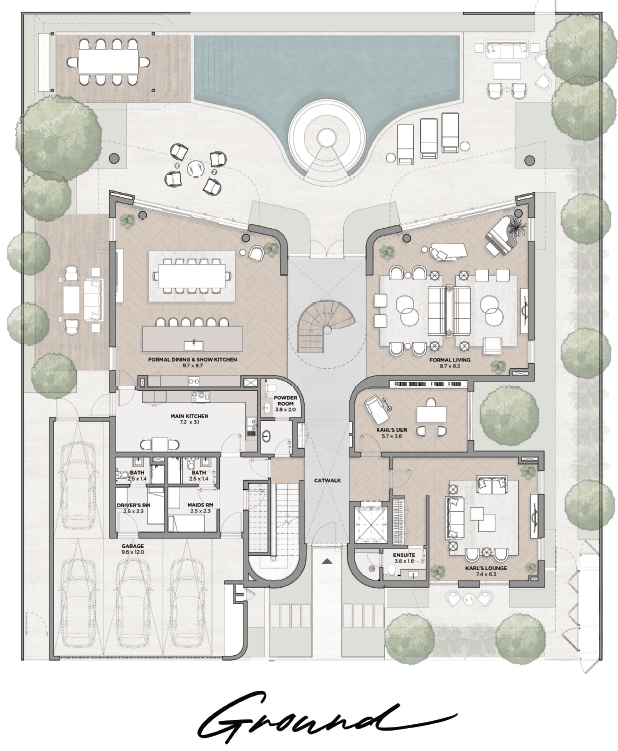
Floor plan

Floor plan for DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLASFloor planView full size

Floor plan

Floor plan for DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLAS

Distress Deal

PROJECT DESCRIPTION

OVERVIEW

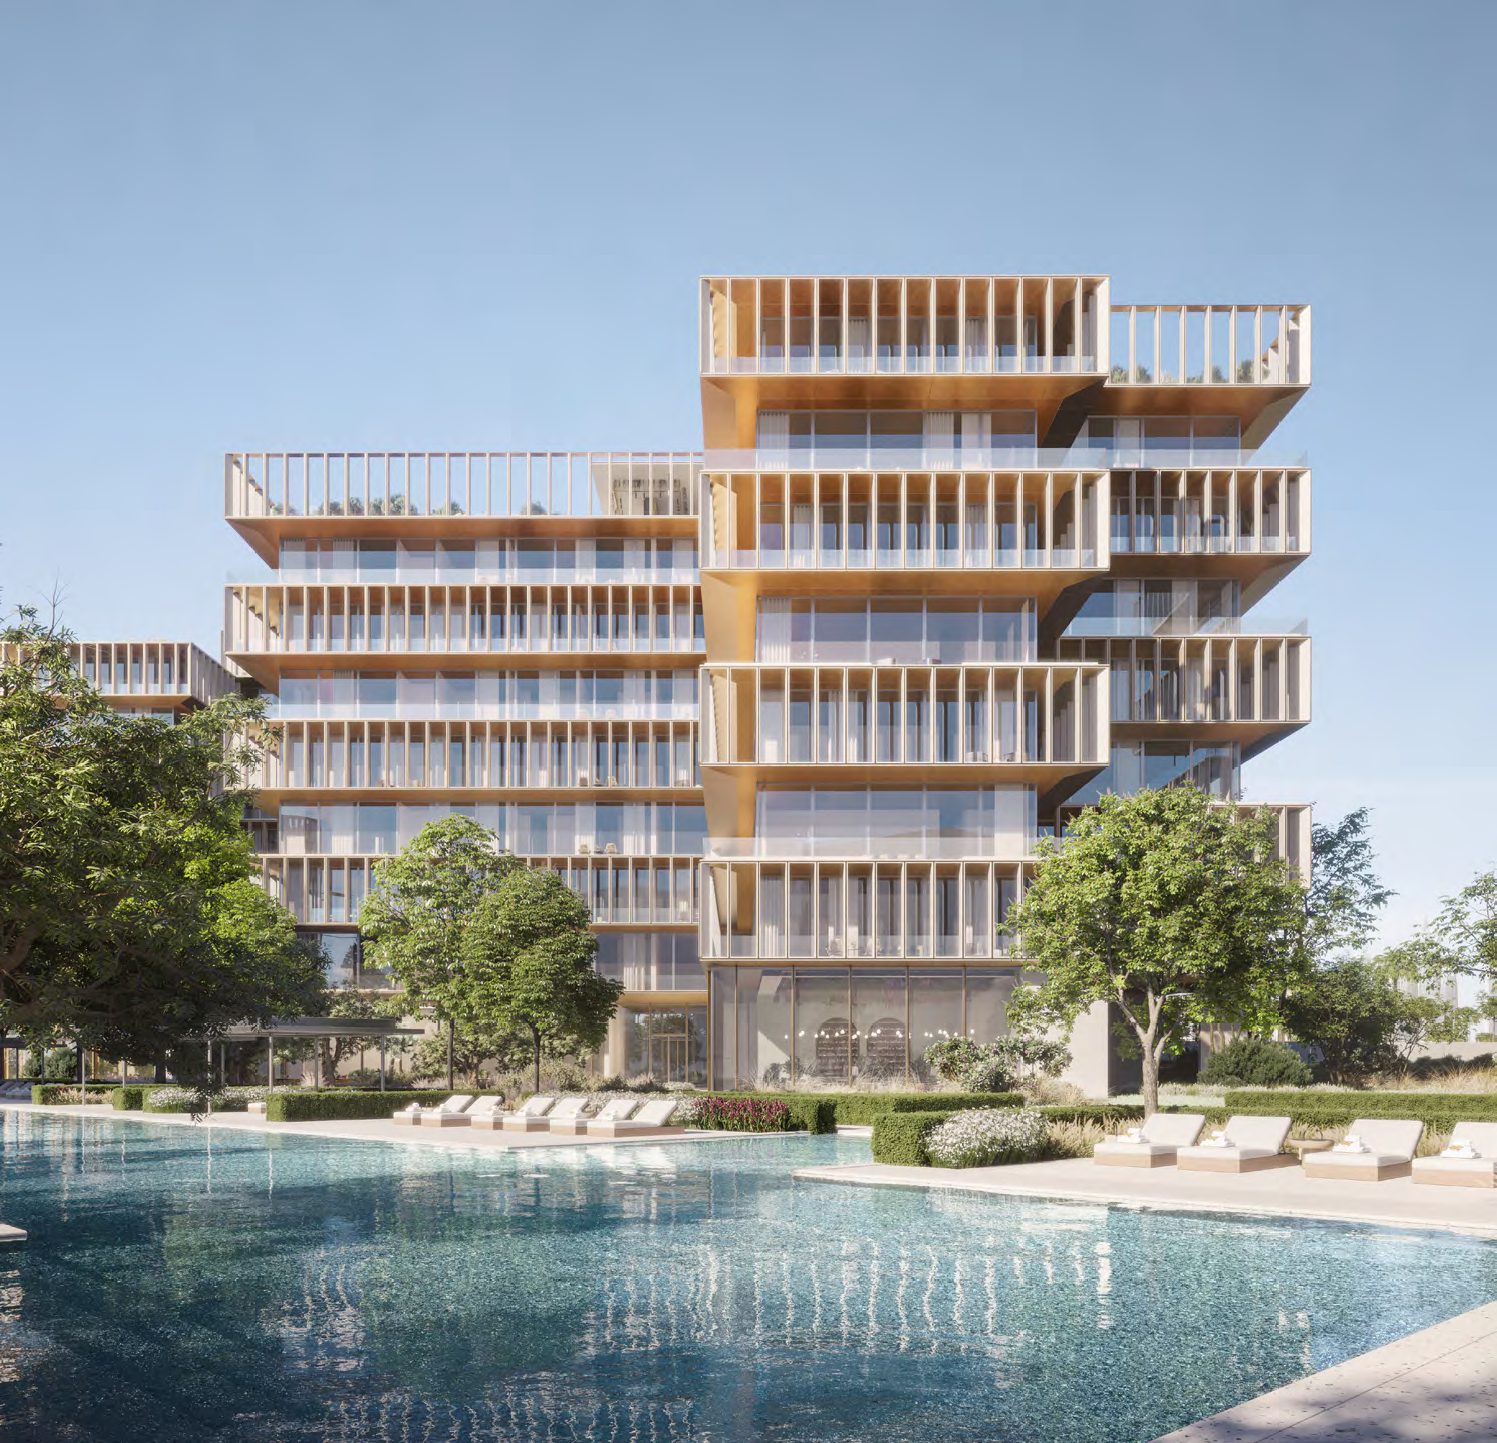
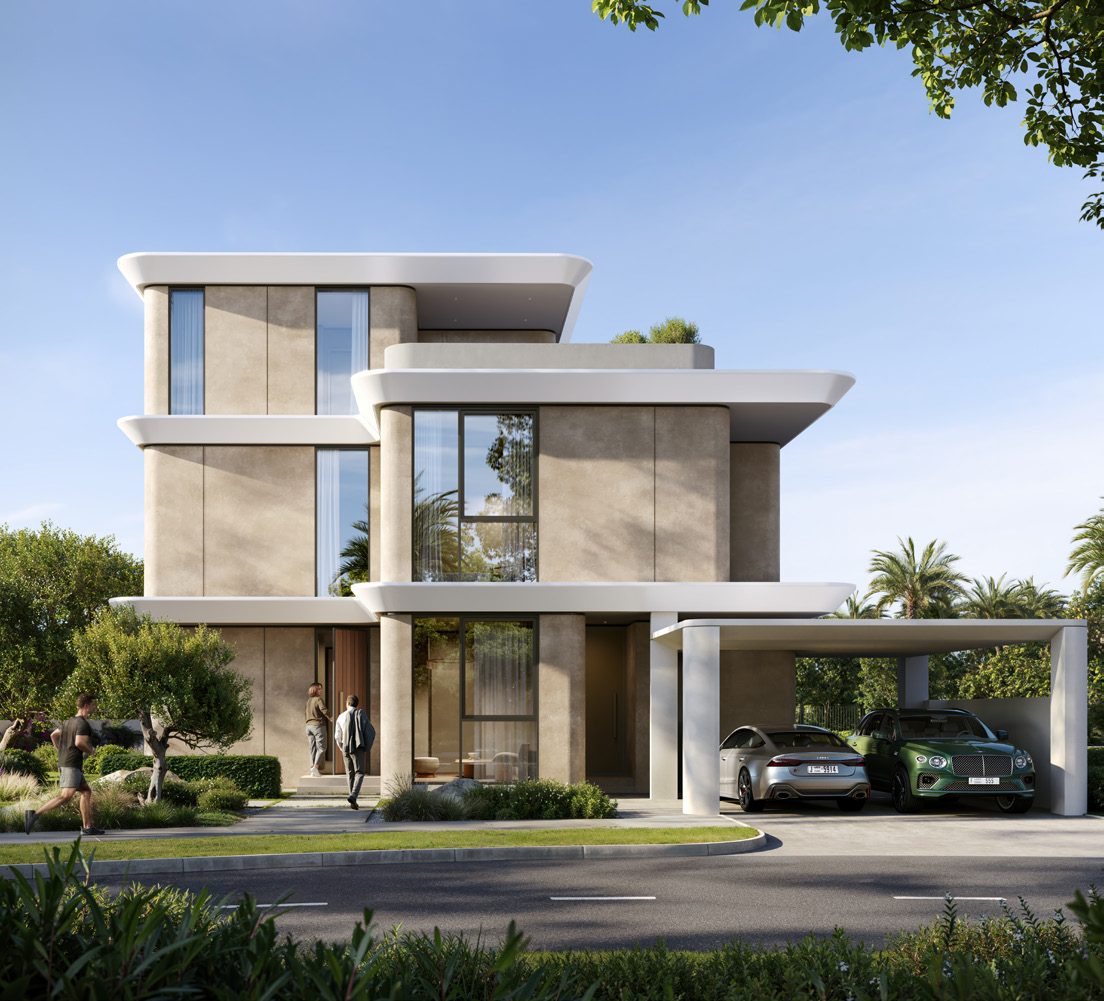
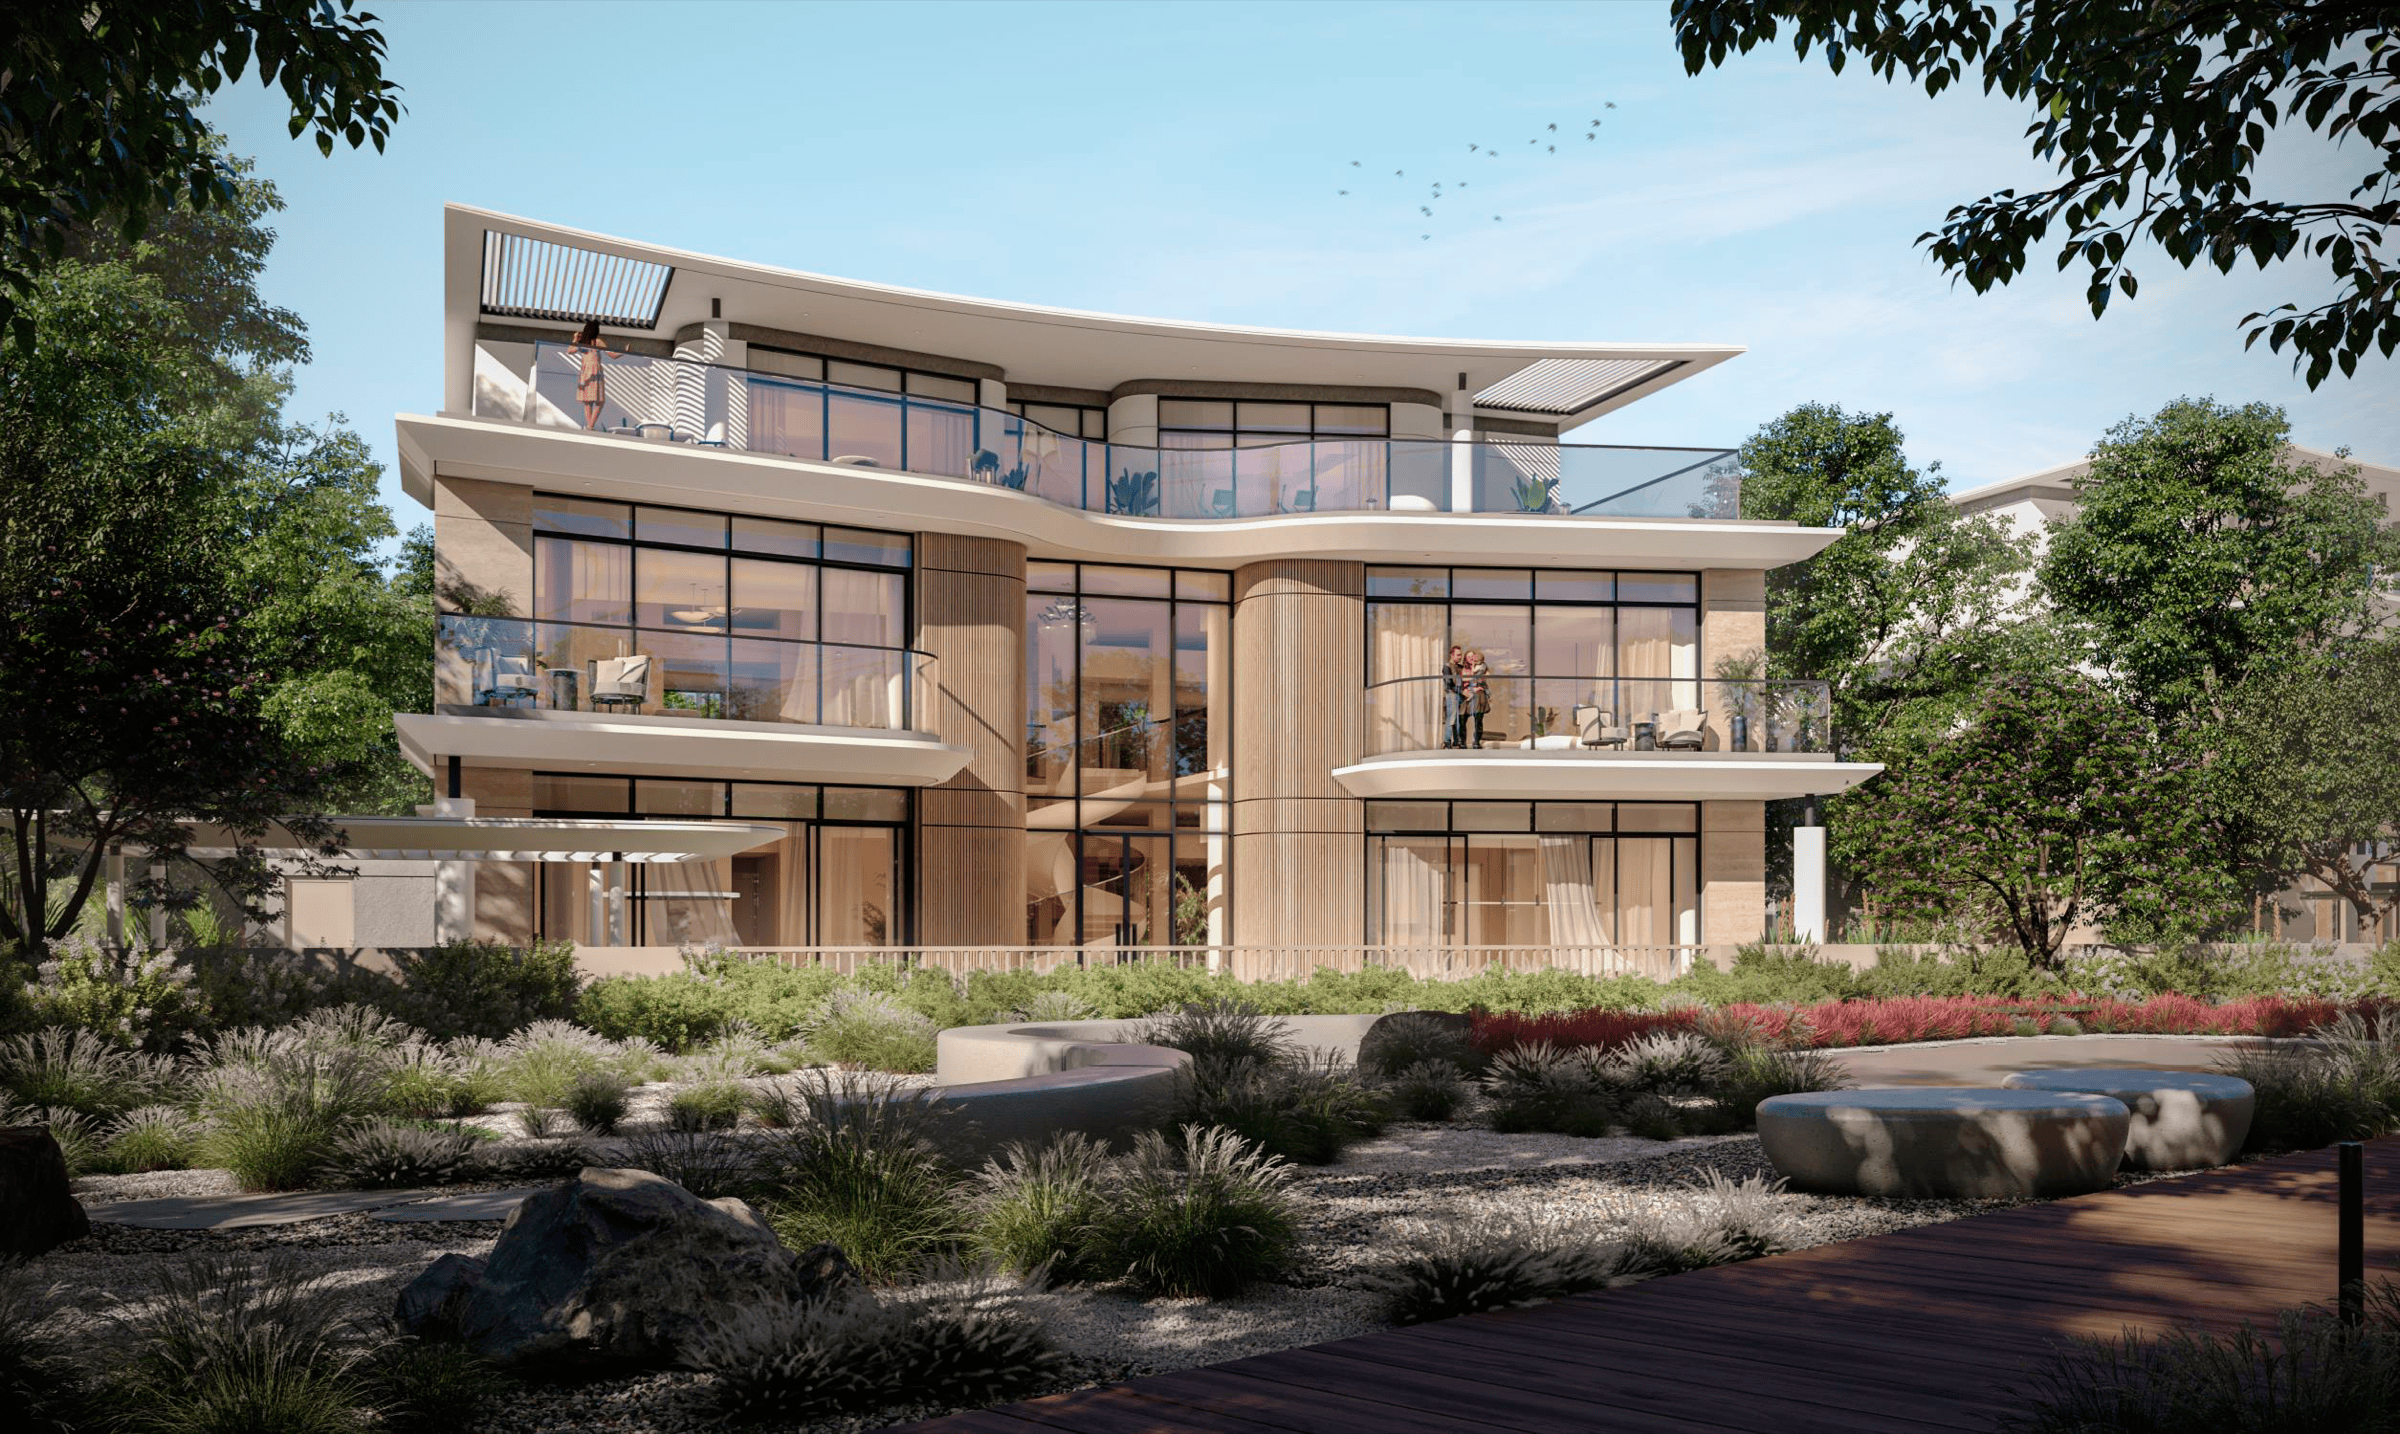
This 6-bedroom villa in Karl Lagerfeld Villas, Wadi Al Safa 3, is offered as a distress deal at AED 23,500,000. The original price, including DLD fees, was AED 26,328,640, so the current asking reflects a 10.7% discount. The built-up area is 13,006 sq.ft, with a price per square foot of AED 1,807. Handover is scheduled for Q3 2027, and the developer is Taraf. The payment structure is split between an initial transfer and a staged plan through to completion, which may suit buyers seeking to manage capital outlay over time. The immediate investment case is the below-market entry for a branded, large-format villa in a project with a limited number of units and a fashion-led design identity. The buyer is not taking on early-stage construction risk, as enabling works and main contracting are already underway, but should still factor in the usual off-plan delivery and market cycle considerations.

LOCATION & TRANSPORT

Karl Lagerfeld Villas is located in Wadi Al Safa 3, within Mohammed Bin Rashid City District 11, a growing residential zone in DubaiLand. This area is positioned for access to key Dubai corridors, with Al Ain Road and Sheikh Mohammed Bin Zayed Road providing connectivity to Downtown Dubai, Business Bay, and Dubai International Airport. The district is still maturing, so while private car remains the primary transport mode, planned infrastructure improvements are expected to enhance accessibility over the coming years. For investors, the location offers a balance between proximity to central Dubai and the space required for large villa formats. The area’s ongoing development trajectory suggests increasing liveability and potential for capital appreciation as the wider district completes.

AMENITIES & SURROUNDING

The Karl Lagerfeld Villas project is designed as a boutique, high-amenity villa cluster with only around 51 residences. Amenities include an artificial beach, children’s pool, clubhouse, fitness centre, gymnasium, library, and a rooftop terrace. The architectural style draws from Karl Lagerfeld’s fashion collections, with minimalistic lines, monochrome palettes, and distinctive features such as a Catwalk Spiral Staircase, sunken lounge, grand walk-in closet, and a rooftop terrace. The clubhouse pavilion hosts The Club, an entertainment space, and The Library, a lounge inspired by Lagerfeld’s personal interests. Each villa is designed for privacy and scale, with features such as a dedicated Majlis, feature pool, and basement. The surrounding area is evolving, with new retail, dining, and leisure infrastructure planned as part of the wider Mohammed Bin Rashid City vision.
MARKET

At AED 1,807 per sq.ft, this villa is priced significantly below recent transaction levels for larger units in the same project, where 7-bedroom villas have traded between AED 2,935 and AED 1,807 per sq.ft in 2026. The 6-bedroom format offers a substantial built-up area, which is attractive for buyers seeking space and privacy in a branded environment. The limited number of units and the fashion-branded positioning may appeal to both end-users and investors targeting the upper segment of Dubai’s villa market. Liquidity for this kind of asset is typically narrower than for smaller, more generic villas, but the discount to recent sales and the project’s design credentials may help underpin resale and rental demand. The main risk points are the off-plan delivery timeline, the evolving nature of the district, and the potential for further supply in the luxury villa segment. However, the below-market entry and the project’s unique branding provide a buffer against these factors.

CONCLUSION

This distress deal in Karl Lagerfeld Villas offers an investor a discounted entry into a limited-supply, design-led villa project in a maturing Dubai district. The 10.7% discount to original price, combined with a price per square foot well below recent transactions, creates a clear value case for buyers who are comfortable with the off-plan timeline and the evolving local infrastructure. The payment plan structure allows for staged capital deployment, which may suit investors seeking flexibility. The main considerations are the delivery schedule, the pace of area development, and the depth of end-user and rental demand for large, branded villas. For those seeking a differentiated asset with potential for capital appreciation as the district matures, this deal presents a balanced risk-reward profile, provided the buyer is clear-eyed about the project’s timeline and the dynamics of Dubai’s upper-tier villa market.

Illustrative model

Scenario modeller

Set your own assumptions and see how DISTRESS DEAL: 6-BR IN KARL LAGERFELD VILLAS behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.

Purchase

The price you are actually considering.

Drives the service charge only.

Rent and service charge both start here.

Holding & income

Your figure — we have not assumed one.

0% holds rent flat. It may be negative.

Your figure — we publish none. A month vacant plus re-letting time is roughly 8%, if that fits your building.

Your figure — we publish none. Letting fees and routine repairs.

Your figure — we publish none. Look your building up on Mollak — rates run AED 3 to AED 30+.

Acquisition costs

4% is the Dubai standard.

Buyer-side. 5% VAT added.

Your figure — we publish none. The trustee tariff is tiered and the admin lines vary by office; ask your trustee office for the total, and add your NOC and any legal quote.

Exit

1 to 40 years.

0% by default: we publish no price forecasts.

5% VAT added automatically.

Nothing to calculate yet

Enter the asking price to run the model.

Every figure recalculates as you type. Use the price you are actually considering.

How each figure is calculated
Handover
The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
Gross yield
Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
Net yield
(Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
Rent growth
Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
ROI
Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
ROE
Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
Cash-on-cash return
Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
IRR
The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.

An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.

Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.

Location

KARL LAGERFELD VILLASWadi Al Safa 3, Dubai

Get Directions

Got questions?

Get Answers!

Read next

A discounted unit is bought the same way any other is — the questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase actually costs.

The gold rule under an entry is its length, against the longest piece here.

Guides

Articles

Need help?