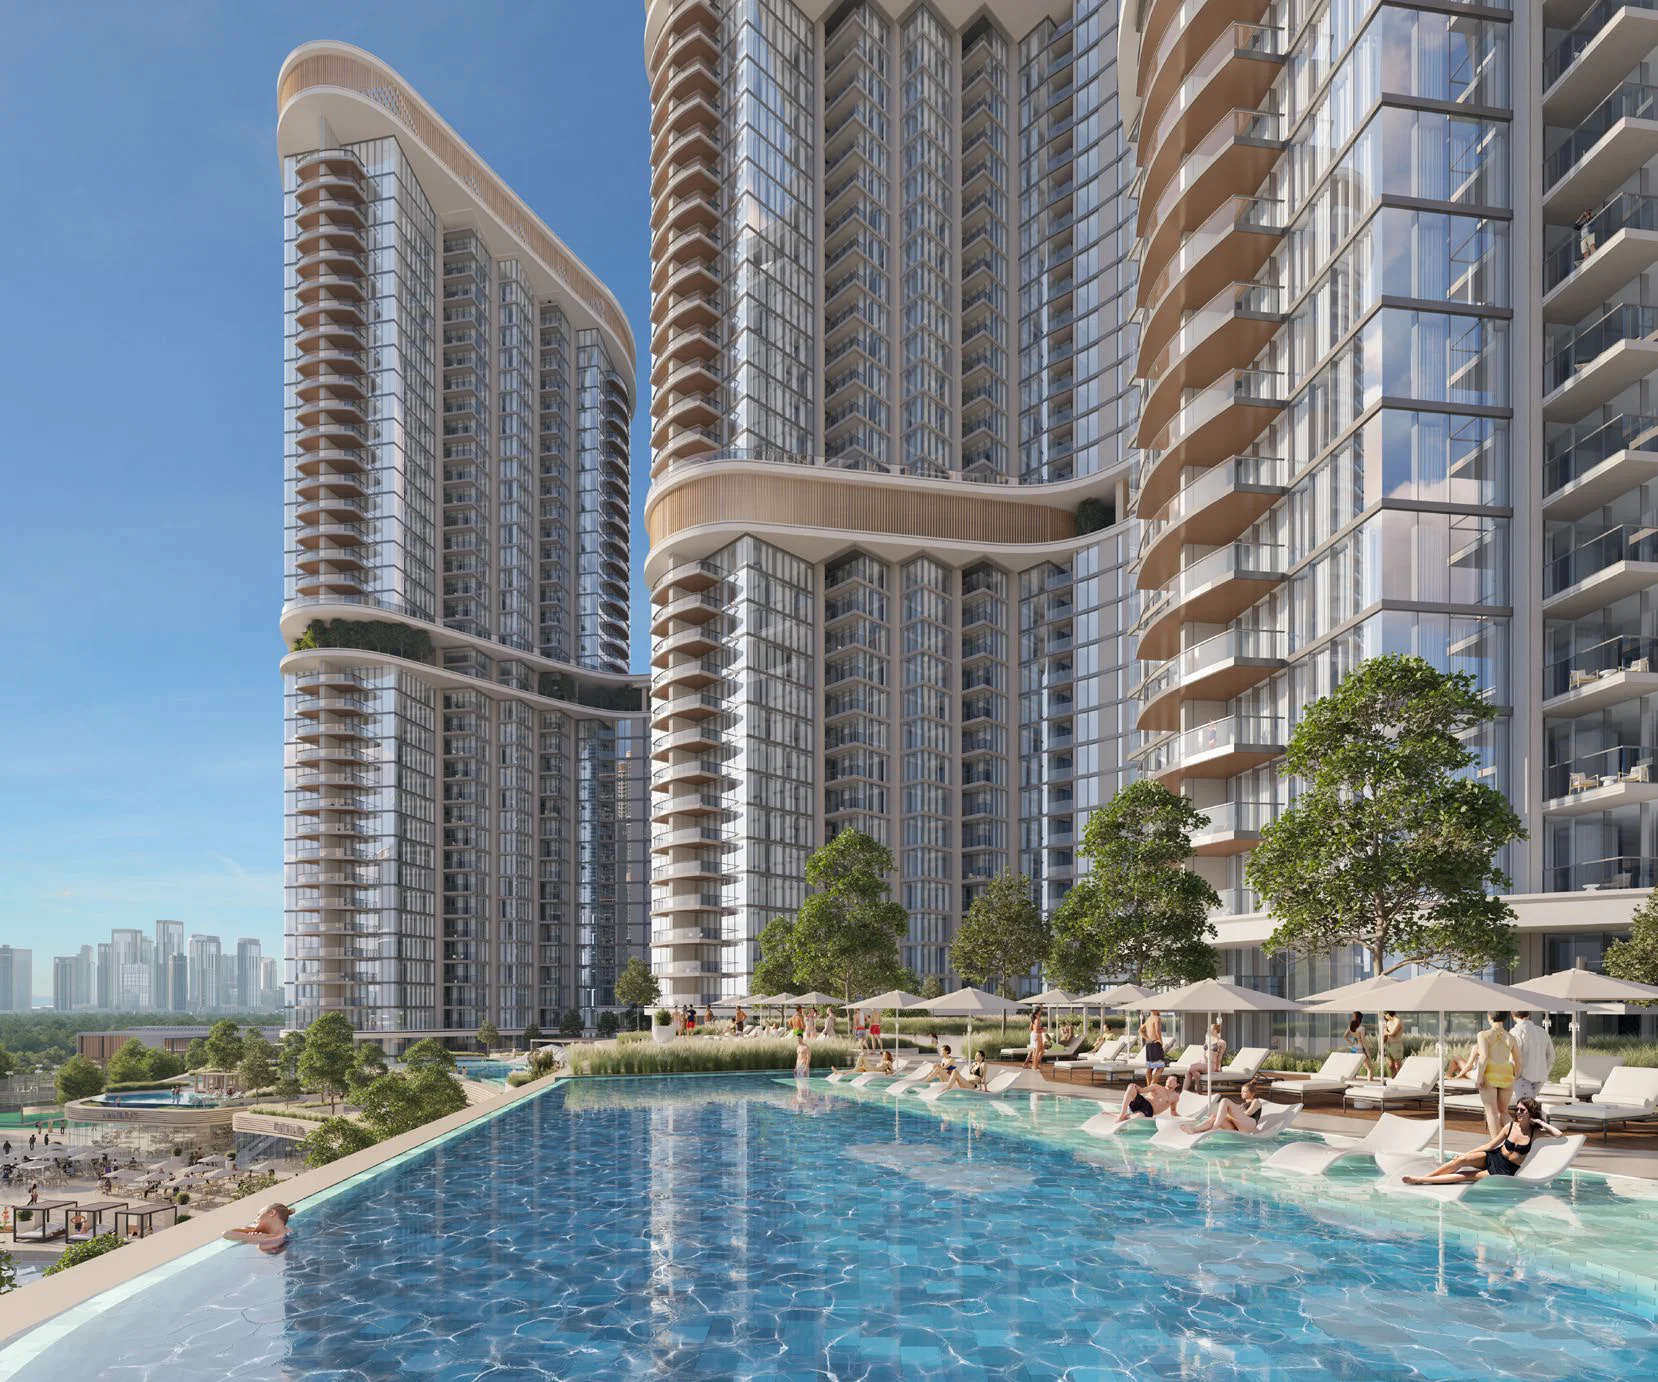
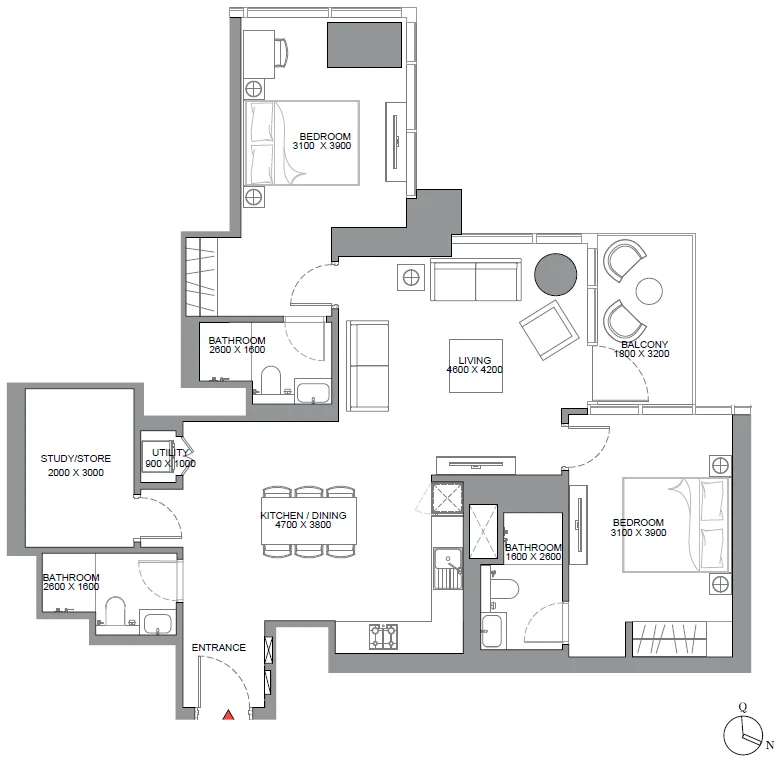
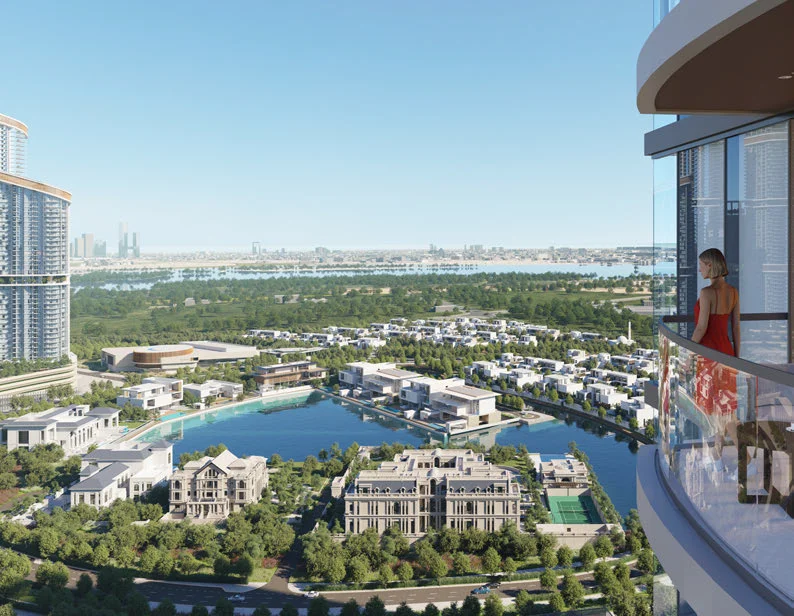
The property is a two-bedroom apartment in Skyscape Altius, a Sobha development in Sobha Hartland II. It has a stated size of 1,268 sq.ft, sits within the 10-15 floor band and looks over the lagoon, and it has a balcony. Handover is scheduled for Q4 2028. The asking price is AED 2,700,000 against an original price plus DLD of AED 3,315,430, a reduction of AED 615,430 or 18.6% below original price. On the stated size the price works out at AED 2,129 per sq.ft. The buyer pays AED 976,760 at transfer, of which AED 787,253 goes to the seller, and then carries AED 1,912,747 of remaining payment plan, giving a total cost of AED 2,889,507. The payment to the seller and the remaining plan together make up the AED 2,700,000 asking price.
Sobha · Sobha Hartland II
DISTRESS DEAL: 2-BR IN SKYSCAPE ALTIUS
Asking priceAED 2,700,000AED 2,129 per sq.ft
Original price + DLDAED 3,315,430
DiscountAED 615,43018.6% below original price
- Unit
- 2-BR
- Size
- 1,268 sq.ft
- Developer
- Sobha
- Handover
- Q4 2028
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
Available
Listed 7 October 2026
Available when we last checked. The asking price shown is the one published when the listing was added on 7 October 2026, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.
On this page
Quick navigation
The numbers
Payment breakdown
Total cost for buyerAED 2,889,507The unit price plus the transfer fees and commission — the whole commitment, not the headline.
Unit priceAED 2,700,000
Fees and commissionAED 189,507
Step 01Due at transferAED 976,760Payable when the unit transfers to the buyer.
- Payment to sellerAED 787,253
- DLD Transfer fee (4% of OP + 40 AED)AED 127,557
- Trustee Office FeeAED 5,250
- Buyer's Agency Commission (2% + VAT)AED 56,700
- Total on transferAED 976,760
Step 02Payable to Sobha after transferAED 1,912,747The balance of the payment plan, which the buyer takes over.
- 23-JAN-2027AED 318,791
- 22-JUL-2027AED 318,791
- On HandoverAED 1,275,165
- Total remaining payment planAED 1,912,747
Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.
Ask about these termsUnit details
- Property type
- Apartment
- Floor
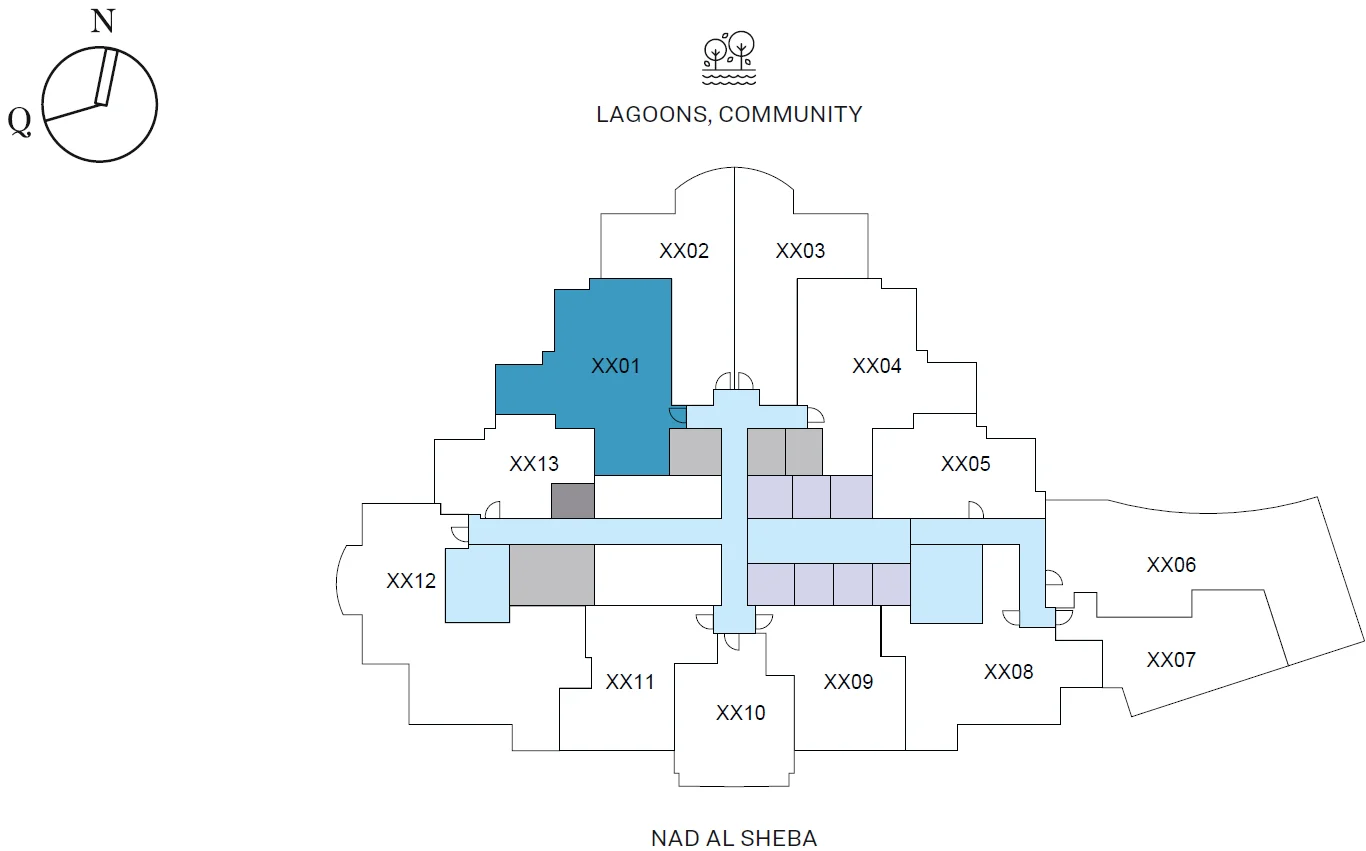
- 10-15
- View
- Lagoon
- Balcony
- Yes
Photography
Gallery
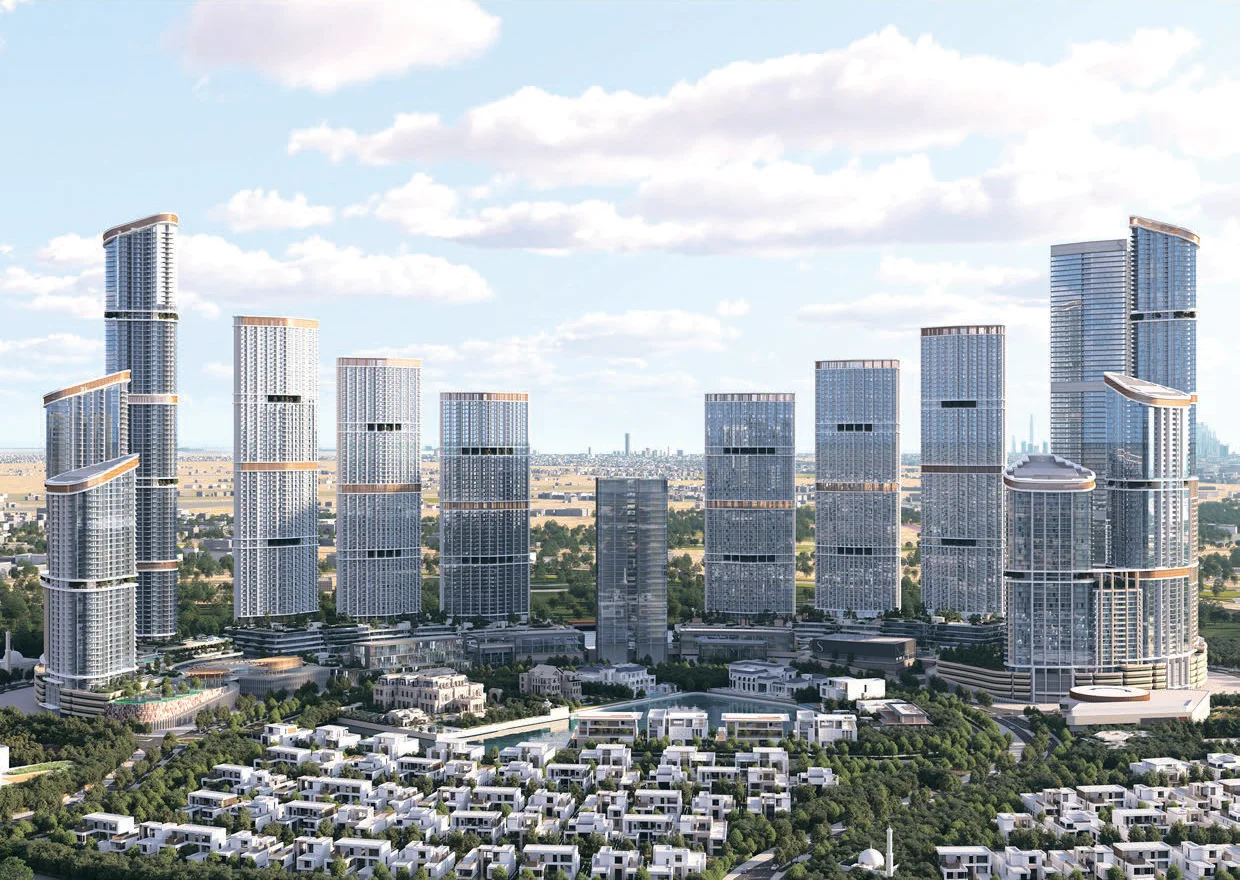
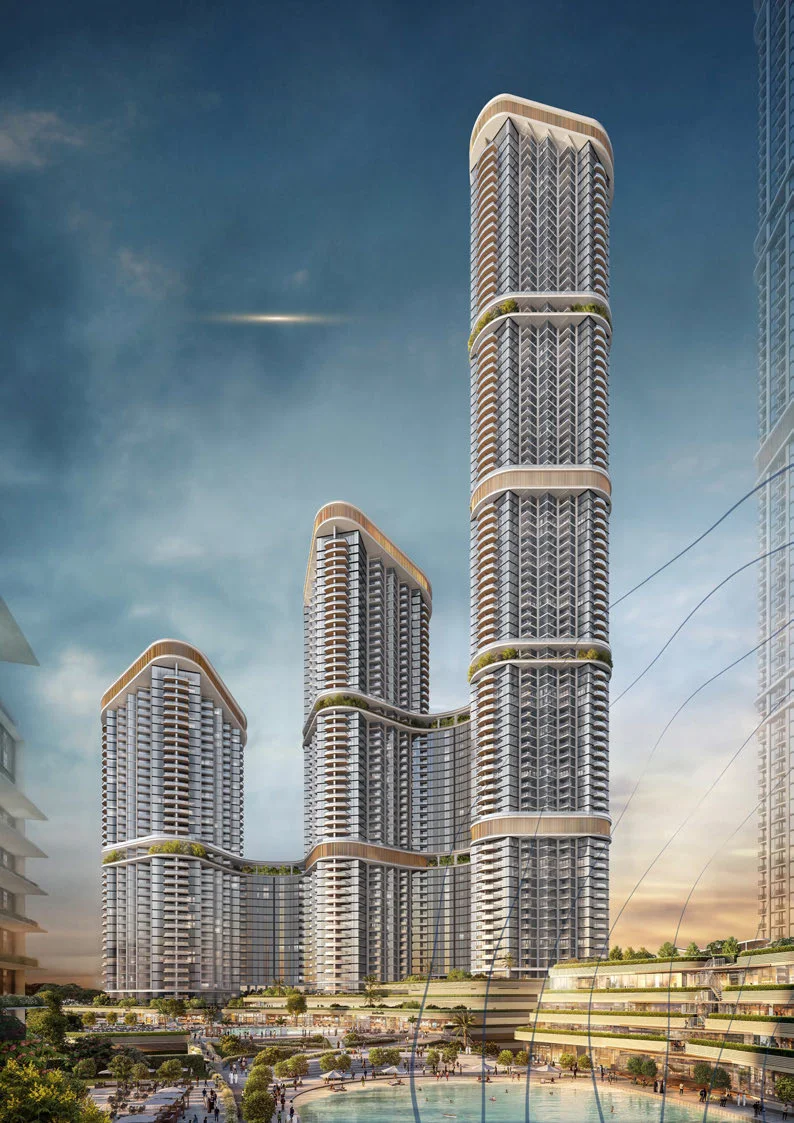
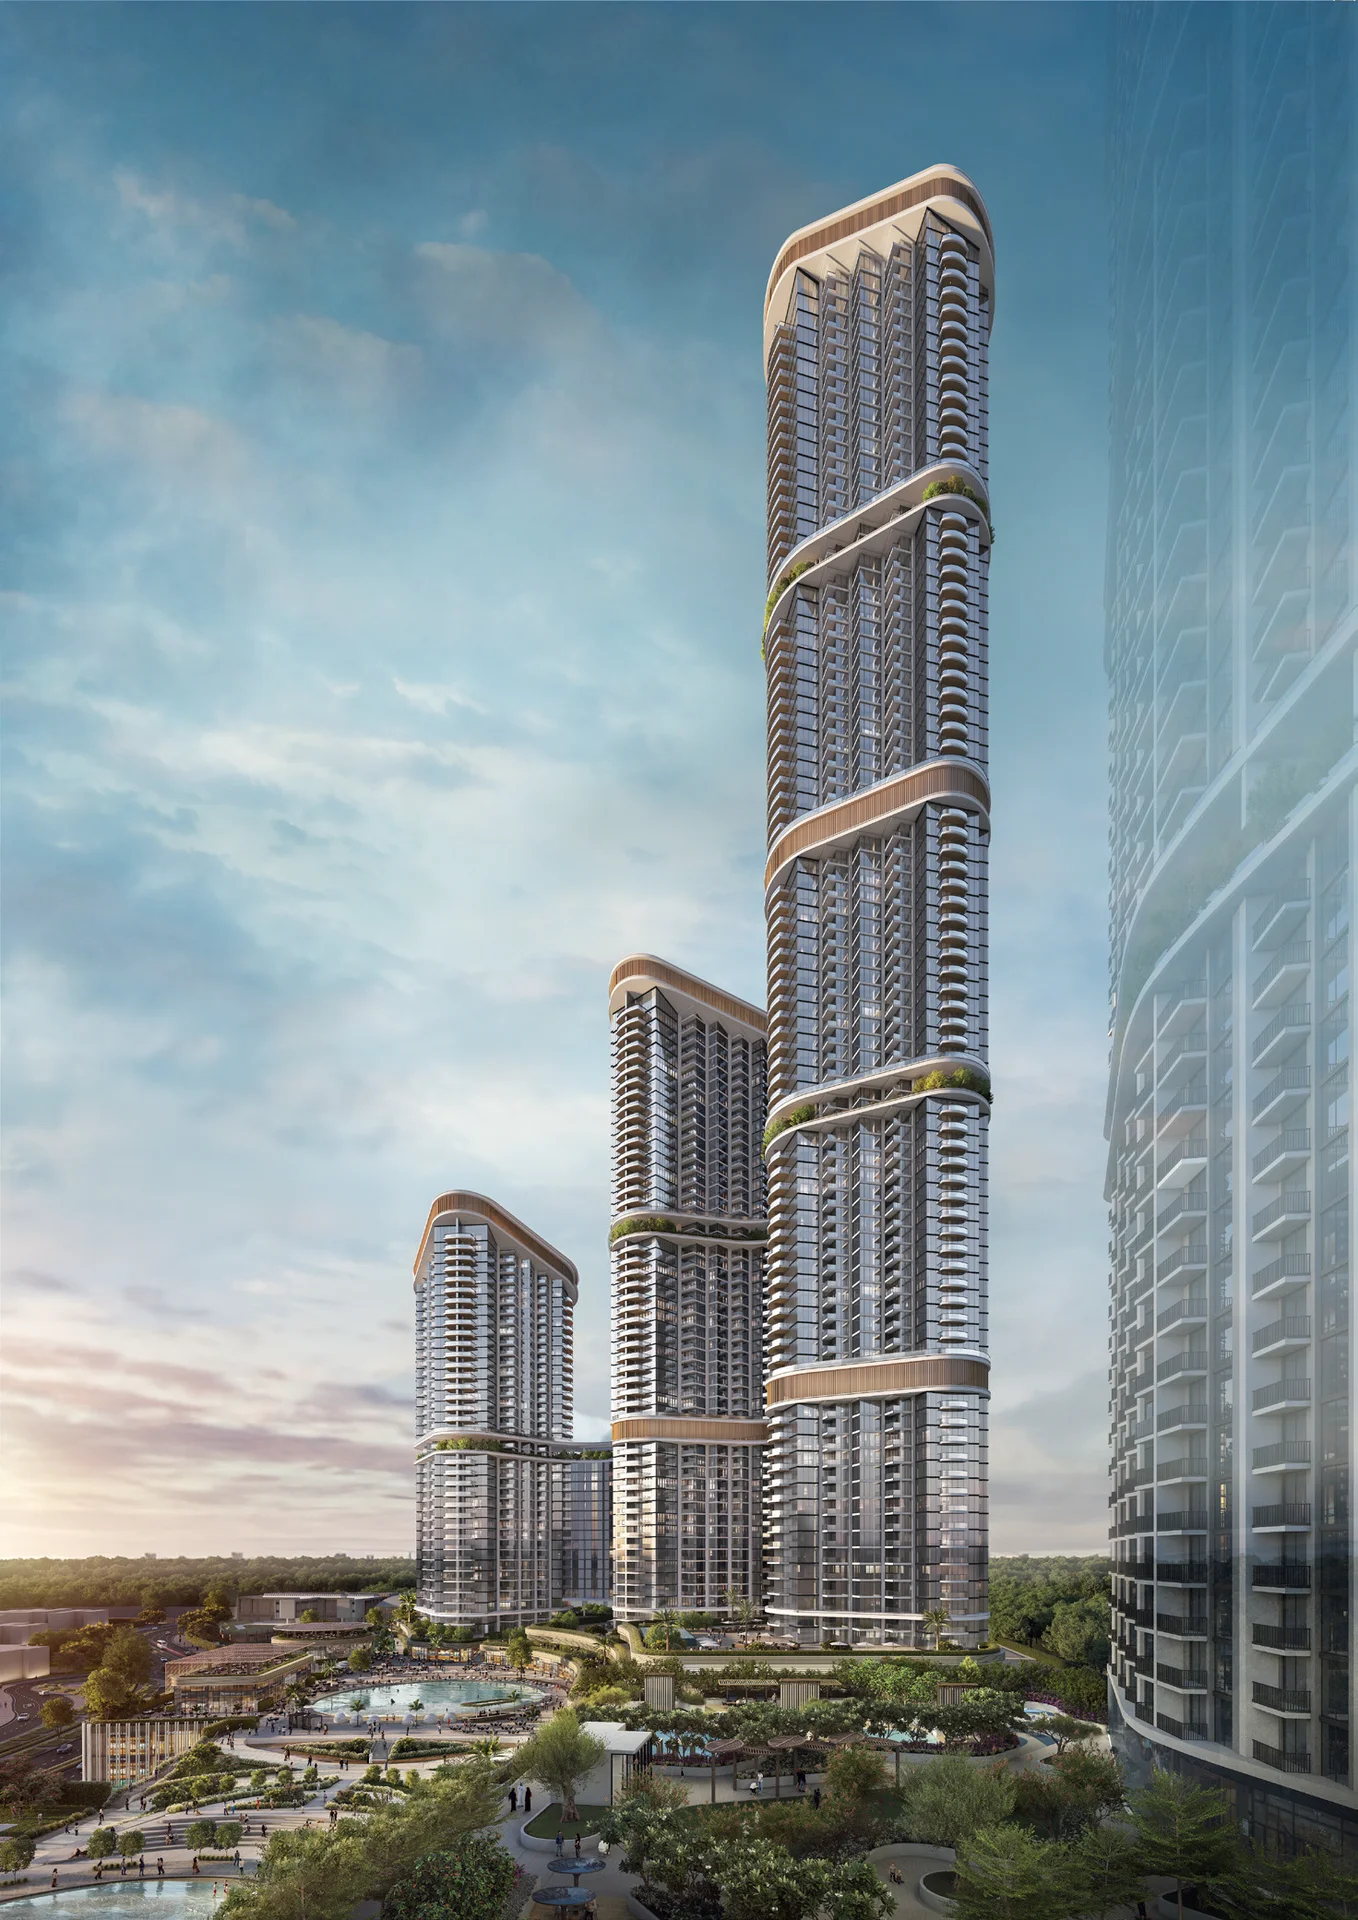
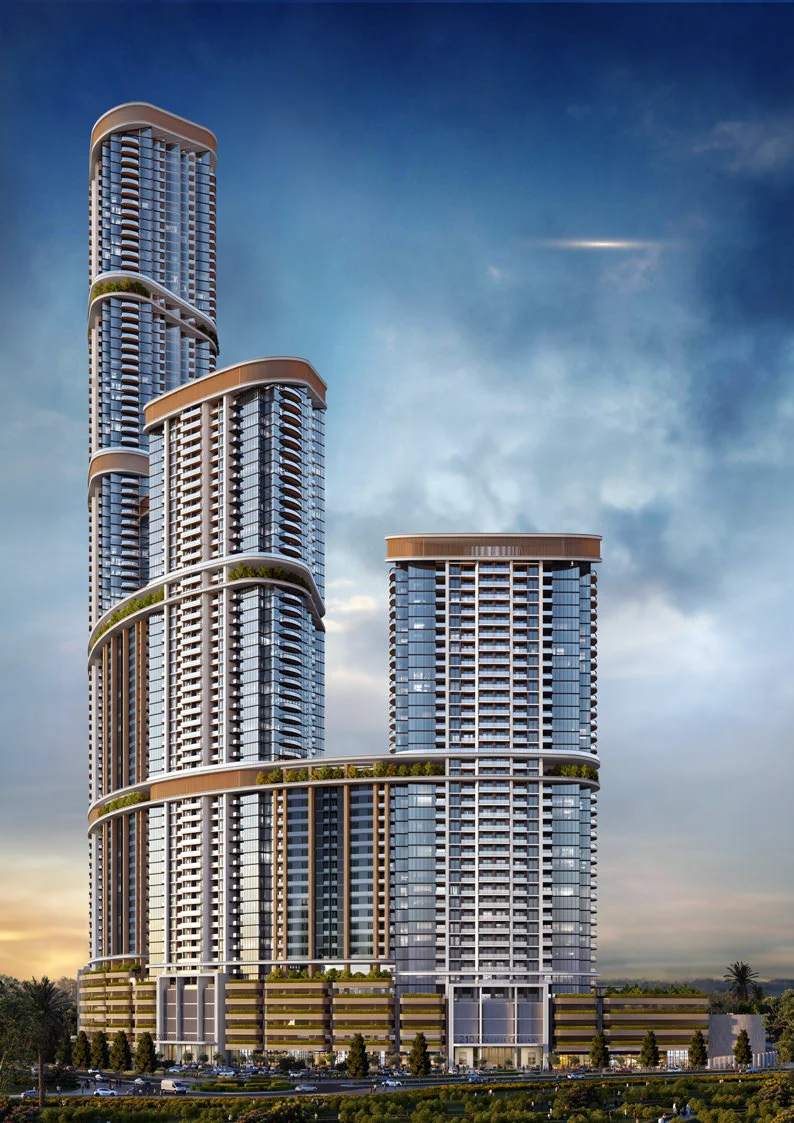
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
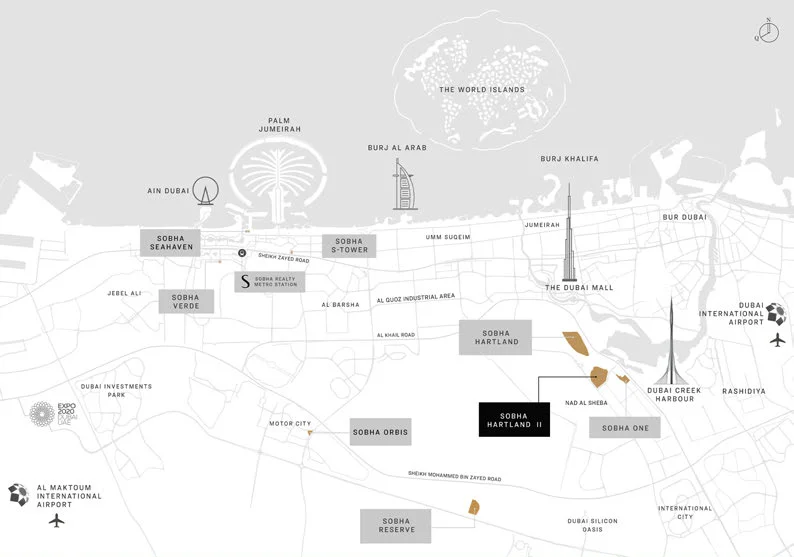
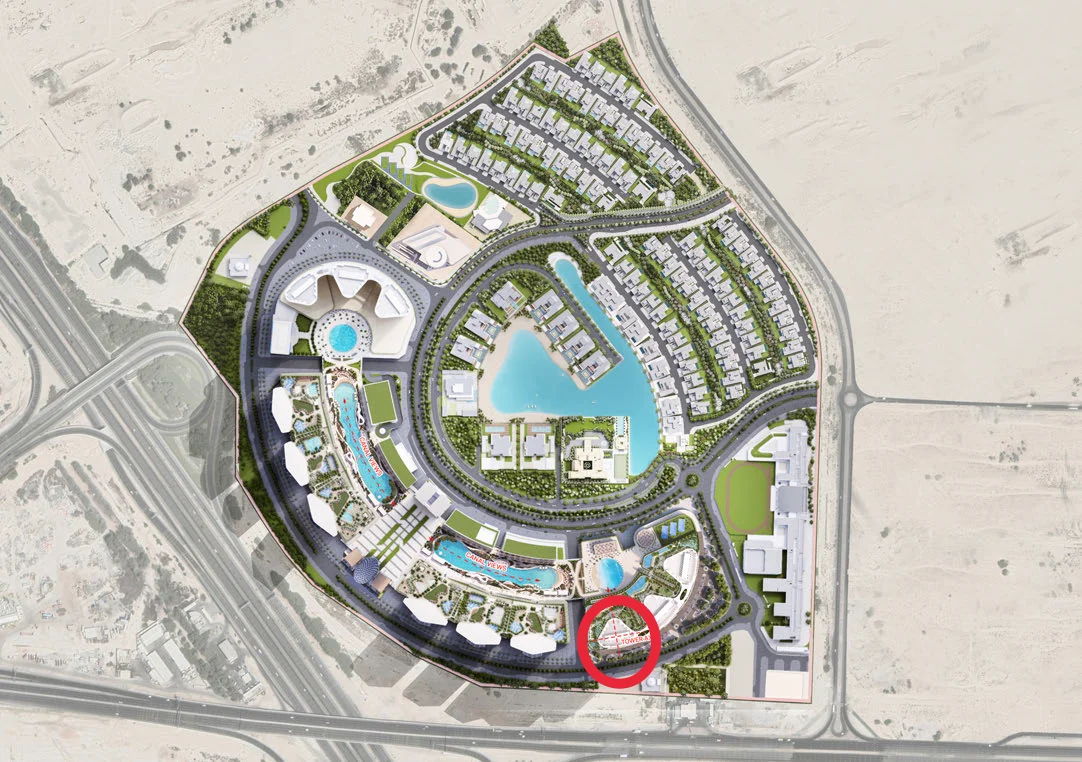
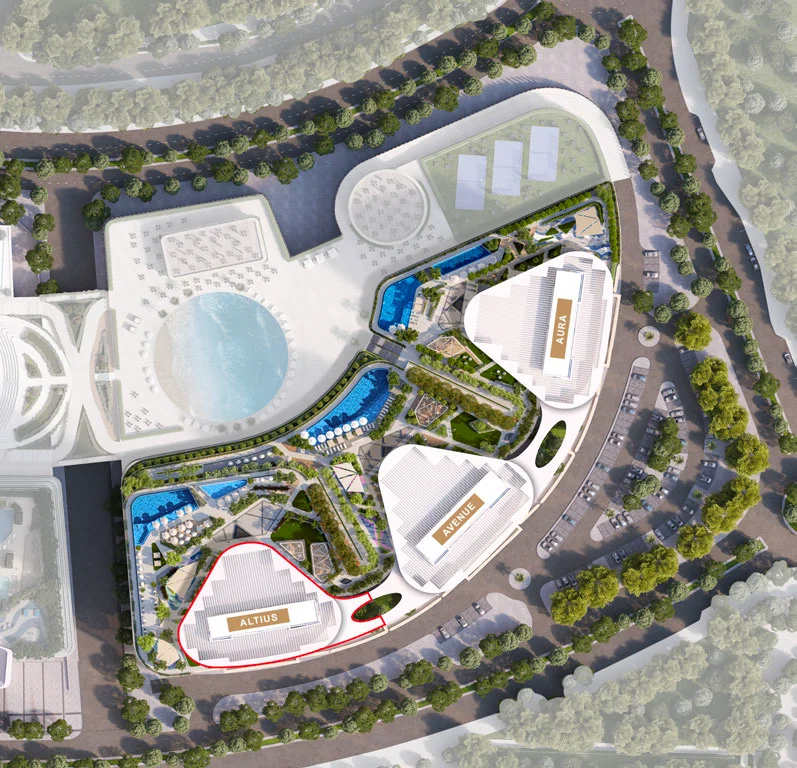
Sobha Hartland II is a Sobha community, and Skyscape Altius is one of its residential towers. The apartment sits in the 10-15 floor band, and its view is of the lagoon. A master-planned community of this kind organises daily life around its own streets and open spaces, with car journeys connecting it to the rest of the city. Handover is scheduled for Q4 2028, so the roads and neighbouring plots around the tower continue to develop until completion. A visit to the community in person gives a clearer picture of the setting than any plan can, and the lagoon frontage and the neighbouring buildings can be seen at the hours that matter to the future occupants.
AMENITIES & SURROUNDING
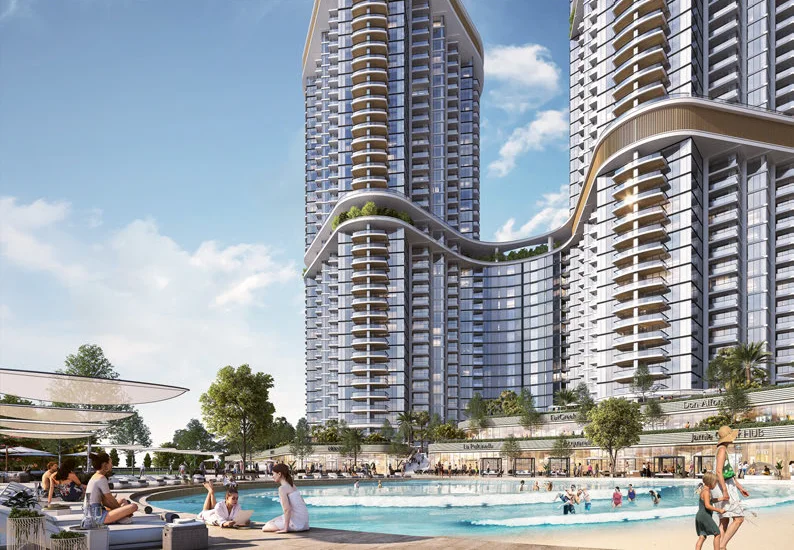
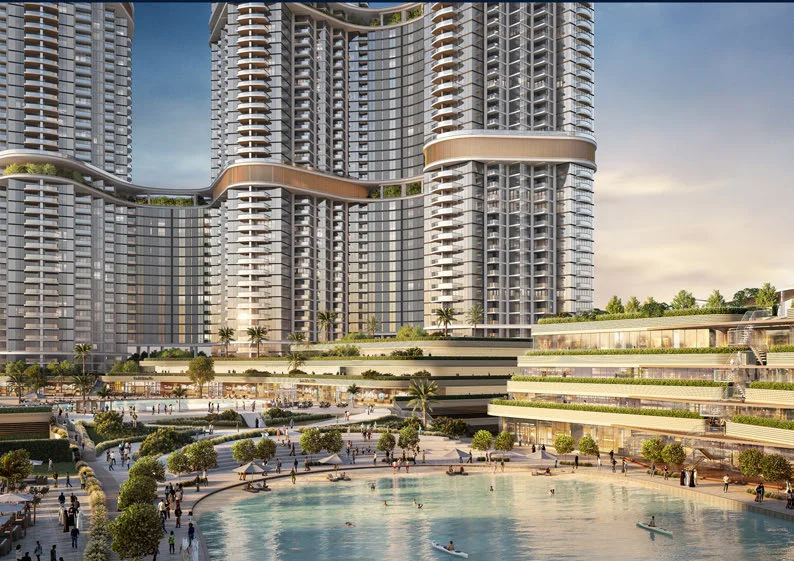
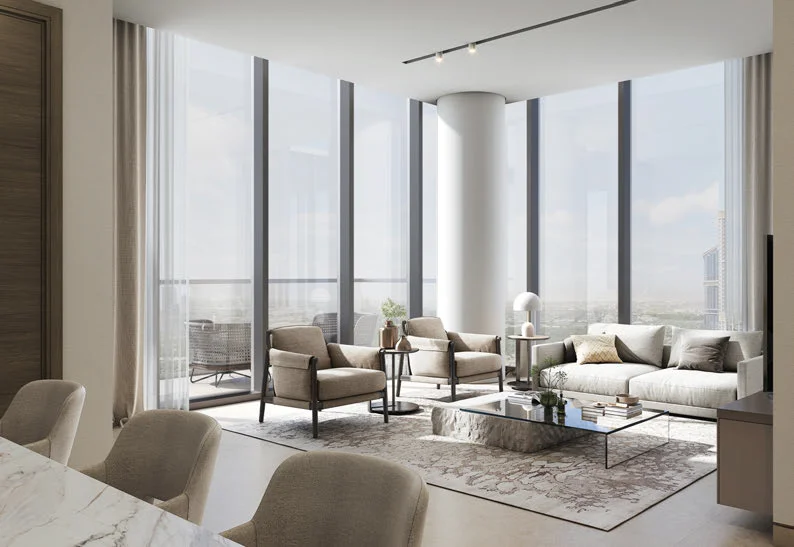
The apartment has two bedrooms within 1,268 sq.ft of stated size, with a balcony and a lagoon view, set within the 10-15 floor band. The shared facilities of Sobha Hartland II follow the developer's community plan, and their delivery follows the handover timetable for Q4 2028. A two-bedroom apartment of this size suits a couple, a small family or an investor looking for a unit with a lagoon outlook. The price per sq.ft on the stated size is AED 2,129. Sobha is the developer and Sobha Hartland II is the sub-community. The apartment, the balcony and the lagoon view make up the full description of the accommodation, and the 10-15 floor band is the floor detail recorded for the unit.
MARKET
The 18.6% reduction is measured against the original price plus the 4% DLD fee, which is the amount the first buyer committed to the developer, and it reads on that basis. At AED 2,129 per sq.ft on the stated size, the price reflects a two-bedroom lagoon-view apartment bought in the construction phase. The structure has three stages. At transfer the buyer pays AED 976,760, made up of AED 787,253 to the seller, the DLD fee of AED 127,557, the trustee office fee of AED 5,250 and the buyer's agency commission of AED 56,700. Two instalments of AED 318,791 follow, on 23 January 2027 and 22 July 2027, a total of AED 637,582. The final AED 1,275,165 falls due on handover, and the three payments together make up the remaining plan of AED 1,912,747. The DLD fee is calculated on the original price excluding DLD, because the unit is selling below that price. The payment to the seller and the remaining plan together make up the AED 2,700,000 asking price. The discount of AED 615,430 is the difference between the original price plus DLD of AED 3,315,430 and the selling price of AED 2,700,000, and it equals 18.6% of the original figure. The total of AED 2,889,507 includes every transfer cost.
CONCLUSION
The apartment suits a buyer who wants two bedrooms, a lagoon view and a balcony in Sobha Hartland II, and who can meet two instalments in 2027 and a final payment on handover in Q4 2028. It also suits an investor comfortable holding through construction. The reduction is 18.6% below original price, and the total cost including every transfer fee is AED 2,889,507. The unit sits in the 10 to 15 floor band and measures 1,268 sq.ft. Sobha is the developer, and the two instalments of AED 318,791 fall in January and July 2027 before the balance on handover.
Location
SKYSCAPE ALTIUS — Sobha Hartland II, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 2-BR IN SKYSCAPE ALTIUS behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Listed
7 October 2026
The date this listing was added to our records. The asking price below is the one published then, and is not re-checked against the market automatically — confirm it with us before relying on it.
Below original price
18.6%
As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.
Handover
Q4 2028
As stated on this listing. Rent cannot start before handover, so on an incomplete unit the early years of the schedule below are holding cost only.
Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 2.86M
Price plus every acquisition cost
Illustrative exit price
AED 2.70M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
—
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
—
Set a gross annual rent
Cash out, and cash back over 5 years
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
Cash required at completion
Purchase priceAED 2,700,000
DLD transfer fee (4%)AED 108,000
Agency fee (2%)AED 54,000
VAT on agency fee (5%)AED 2,700
Conveyancing, trustee & adminAED 0
Total cash investedAED 2,864,700
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)—
Maintenance & management (not set)—
Service charge (1,268 sq ft at a rate not yet set)—
Net operating income—
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 2,864,700 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 2,643,300 | AED 2,643,300 |
| Years 1–5 | AED 0 | AED 2,643,300 | AED 2,643,300 |
| Less the year-0 outflow of AED 2,864,700 → total profit | −AED 221,400 | ||
Exit at year 5: illustrative sale price AED 2,700,000 less selling costs AED 56,700 = AED 2,643,300 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 2.09M | — | — | — |
| −3% p.a. | AED 2.32M | — | — | — |
| 0% p.a.your figure | AED 2.70M | — | — | — |
| 3% p.a. | AED 3.13M | — | — | — |
| 5% p.a. | AED 3.45M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Rashid Yachts and Marina
DISTRESS DEAL: 1-BR IN OCEAN POINT - TOWER 2
AED 1,868,764AED 1,536,000Asking price
17.8%Below O.P.
- Price / sq.ft
- AED 1,908
- Developer
- Emaar
Emaar Beachfront
DISTRESS DEAL: 1-BR IN SEAPOINT - TOWER 2
AED 3,065,804AED 2,630,000,Asking price
14.2%Below O.P.
- Size
- 764 sq.ft
- Price / sq.ft
- AED 3,442
- Developer
- Emaar
- Handover
- Q2 2028
Bluewaters Island
DISTRESS DEAL: 2-BR + Maid's IN BLUEWATERS BAY - BUILDING 1
AED 6,362,000AED 5,252,000Asking price
17.4%Below O.P.
- Size
- 1,670 sq.ft
- Price / sq.ft
- AED 3,145
- Developer
- Meraas
- Handover
- Q3 2027
Emaar Beachfront
DISTRESS DEAL: BULK DEAL - 9 APARTMENTS IN BAYVIEW - TOWER 1
AED 58,416,792AED 47,000,000Asking price
19.5%Below O.P.
- Size
- 10,041 sq.ft
- Price / sq.ft
- AED 4,681
- Developer
- Emaar
- Handover
- Q2 2027
Dubai Harbour
DISTRESS DEAL: 1-BR IN PALACE BEACH RESIDENCE - TOWER 2
AED 1,950,000Asking price
- Size
- 796 sq.ft
- Price / sq.ft
- AED 2,450
- Developer
- Emaar
Damac Islands
DISTRESS DEAL: 6-BR IN BORA BORA 4
AED 6,578,000AED 6,100,000Asking price
7.3%Below O.P.
- Size
- 4,440 sq.ft
- Price / sq.ft
- AED 1,374
- Developer
- Damac
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.