Palm JumeirahAED 3,594/sqftDubai Maritime CityAED 3,132/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,760/sqftDubai Creek HarbourAED 2,565/sqftBusiness BayAED 2,549/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,444/sqftJumeirah Lakes TowersAED 2,285/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,047/sqftJumeirah Village TriangleAED 1,664/sqftDubai SouthAED 1,647/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,500/sqftDubai Sports CityAED 1,329/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm JumeirahAED 3,594/sqftDubai Maritime CityAED 3,132/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,760/sqftDubai Creek HarbourAED 2,565/sqftBusiness BayAED 2,549/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,444/sqftJumeirah Lakes TowersAED 2,285/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,047/sqftJumeirah Village TriangleAED 1,664/sqftDubai SouthAED 1,647/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,500/sqftDubai Sports CityAED 1,329/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO SEP 2026
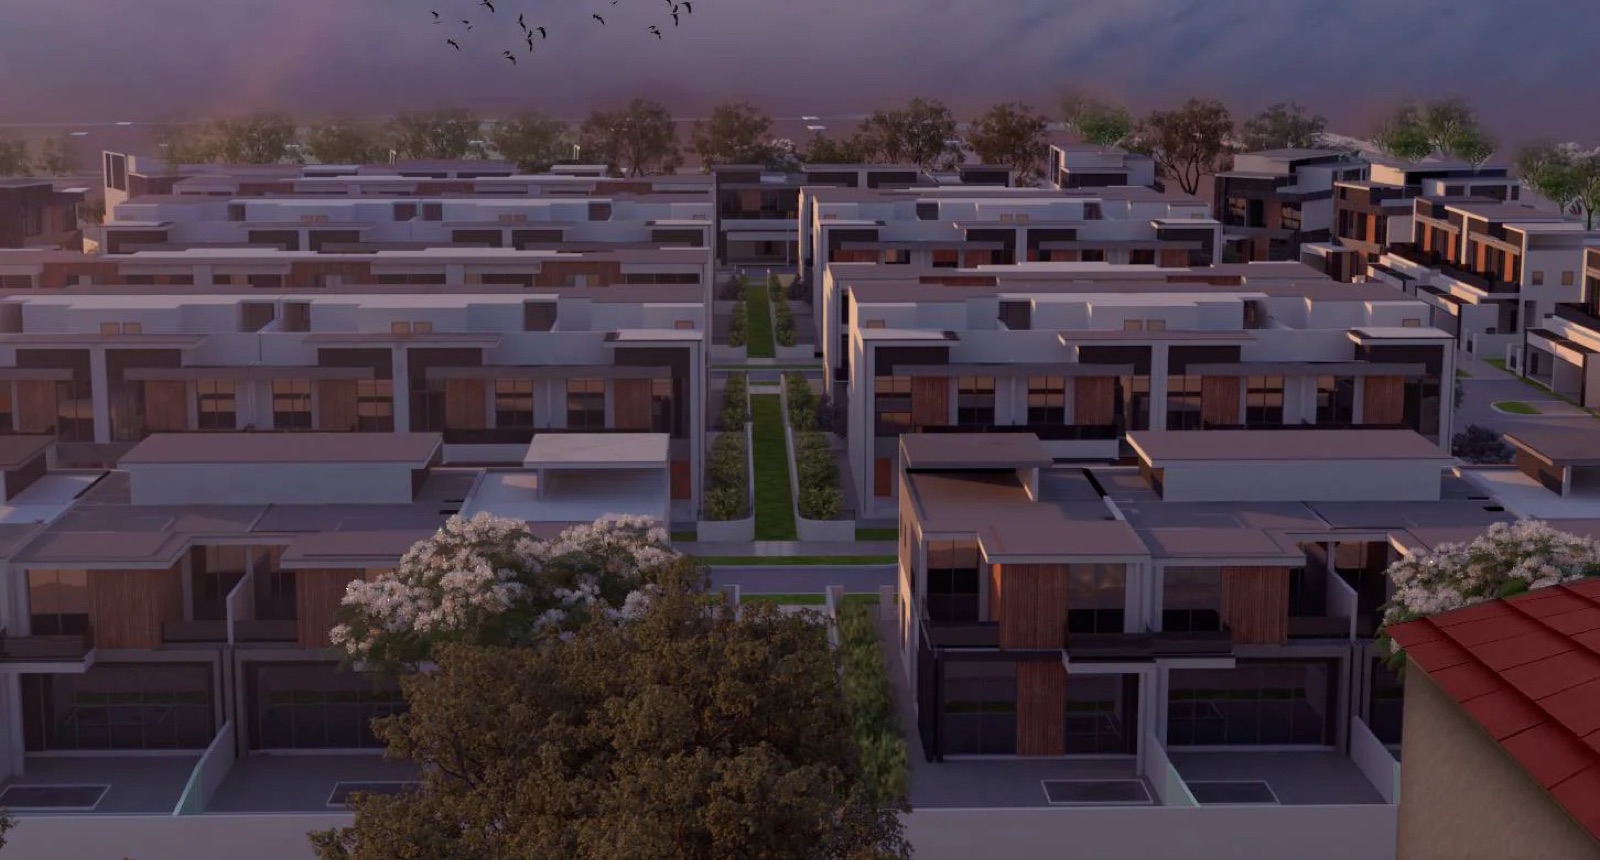
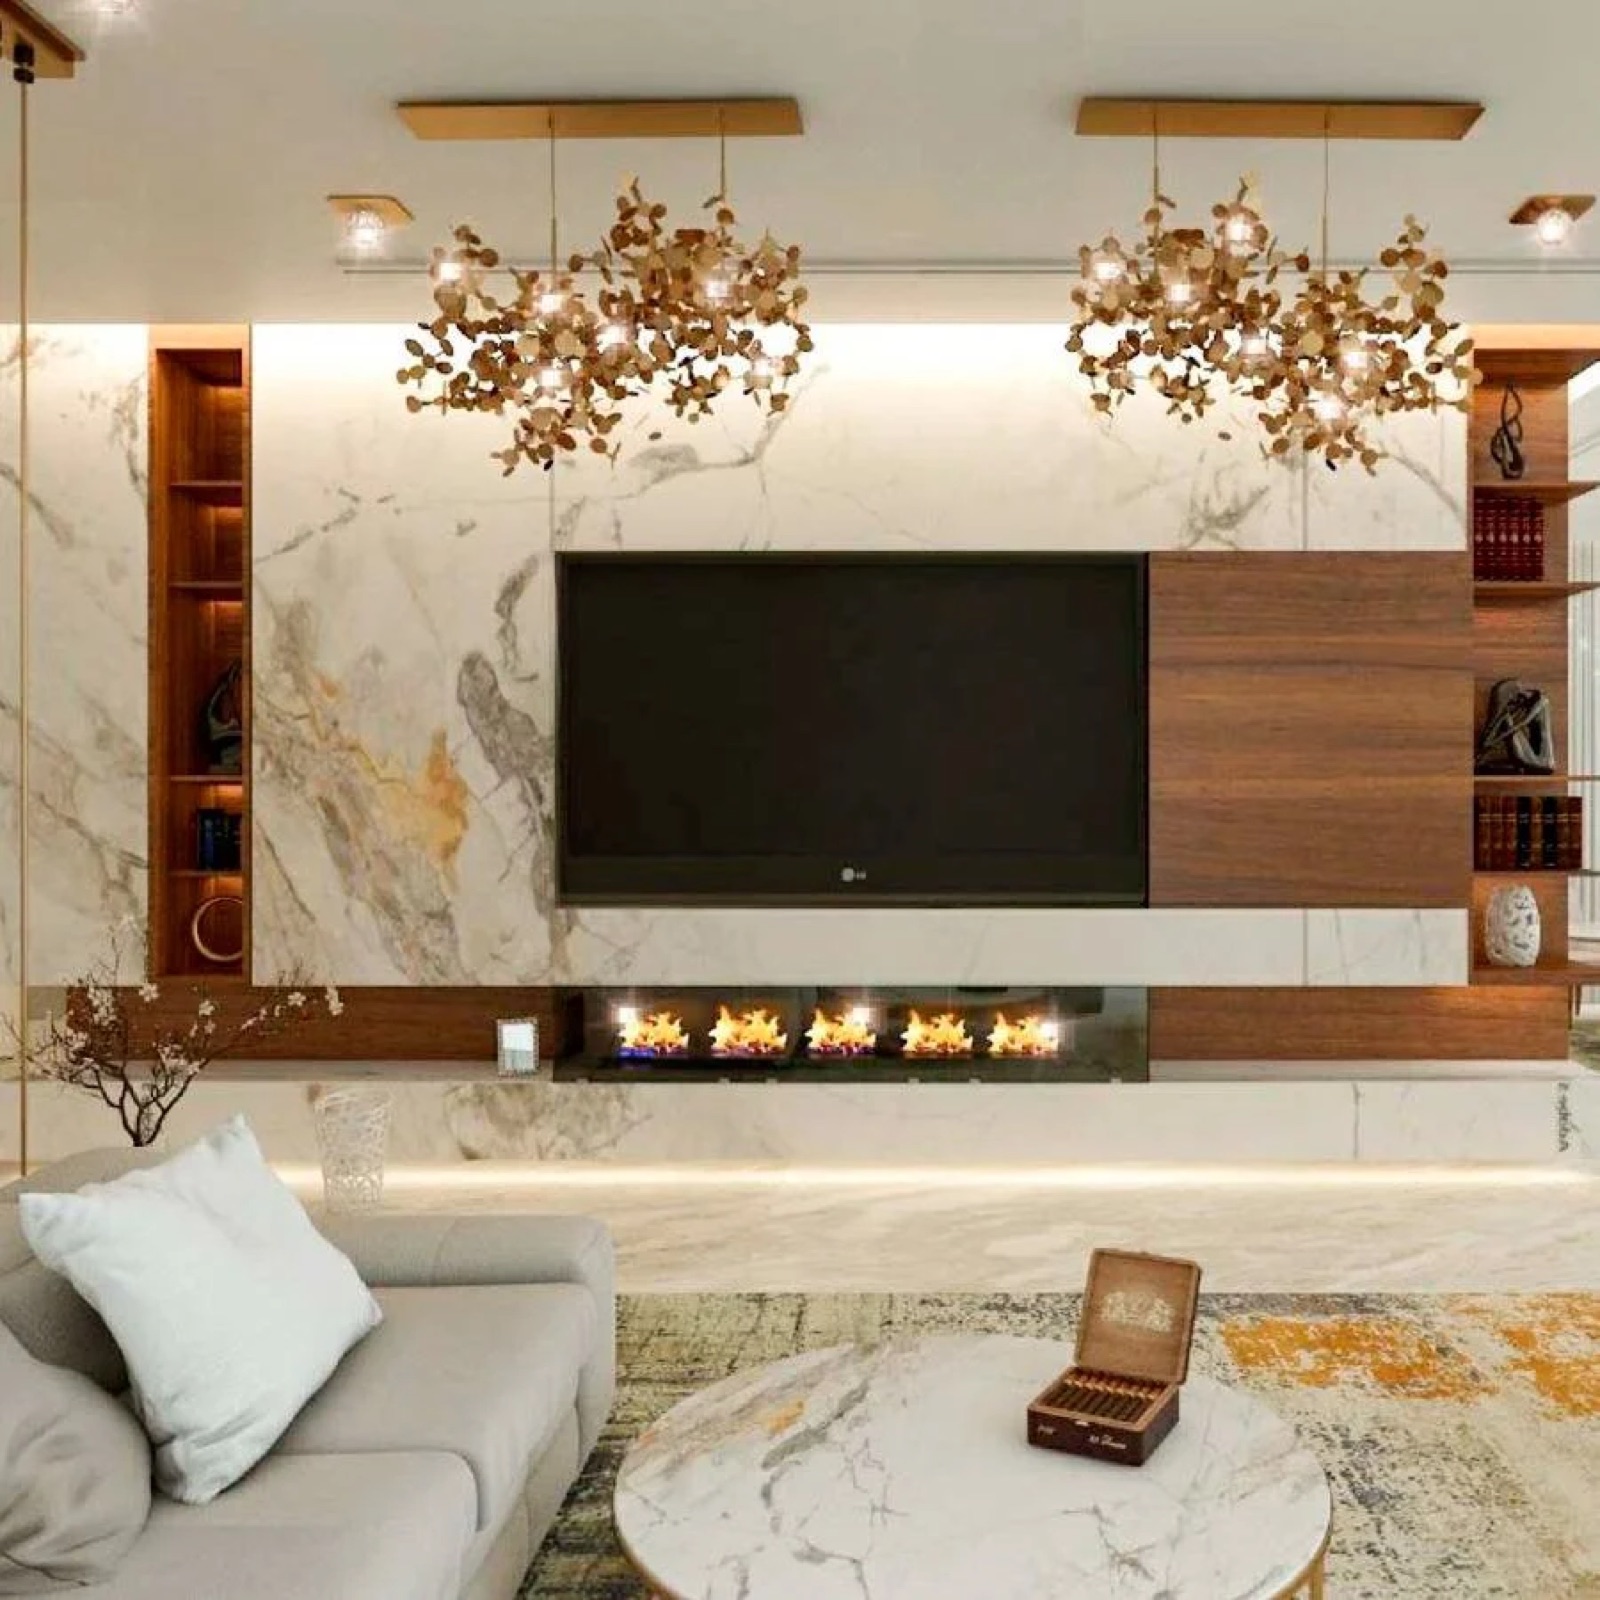
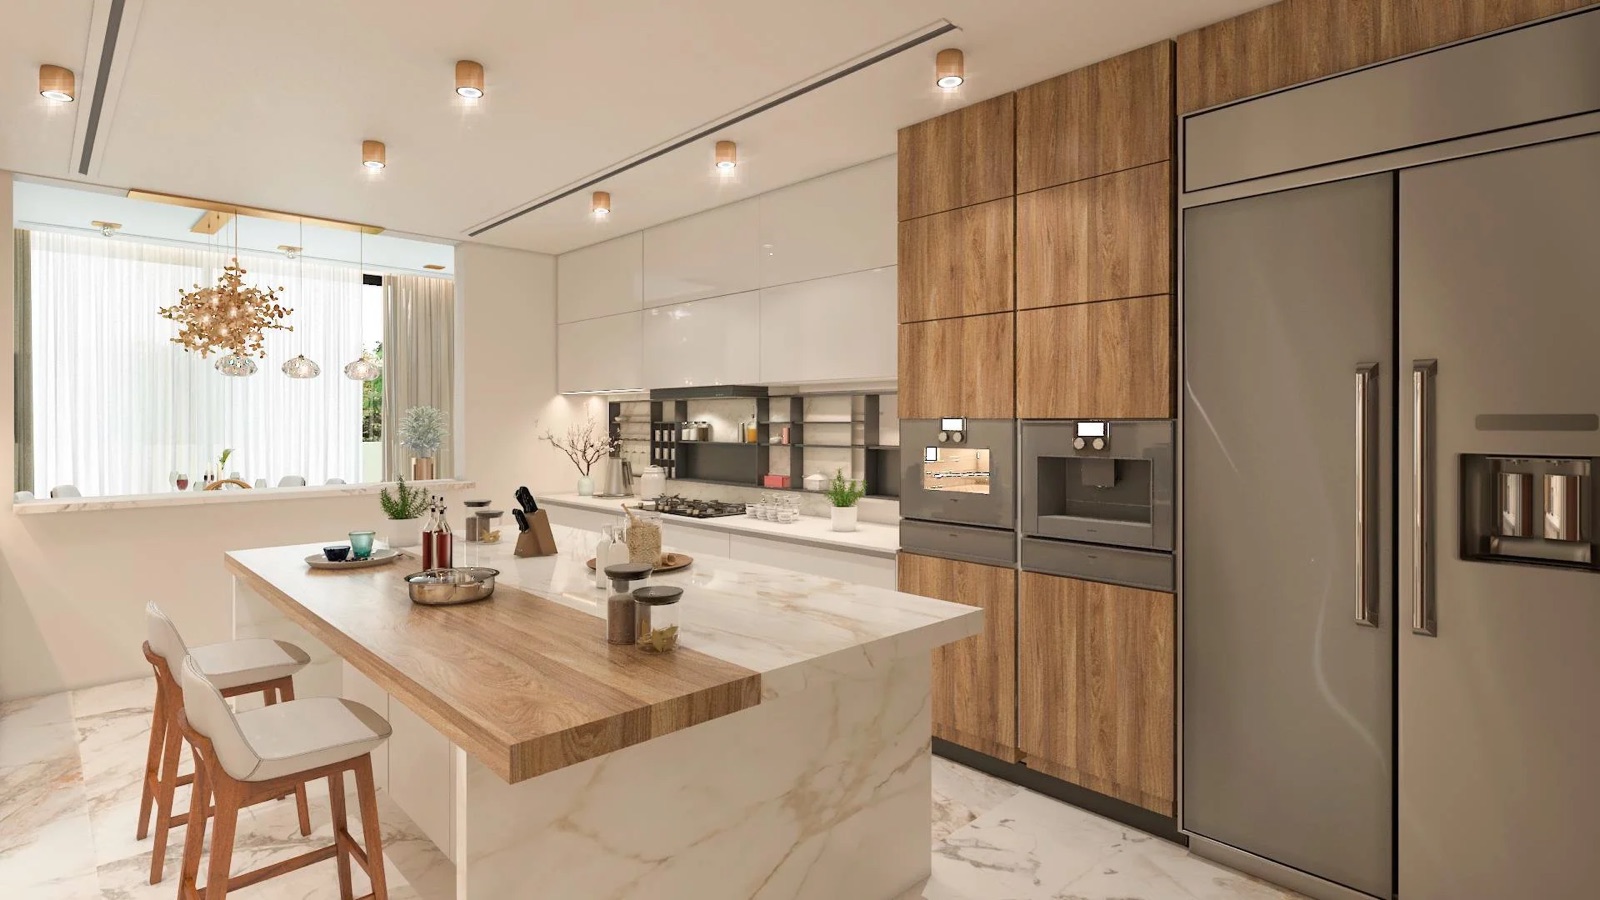
AvailableDISTRESS DEAL: 5-BR + Maid's IN PARADISE HILLS — distress deal in Golf City from Mitchell's Commercial Real EstatePARADISE HILLS · Golf City1 / 10

Gulf Land · Golf City

DISTRESS DEAL: 5-BR + Maid's IN PARADISE HILLS

Asking priceAED 8,550,000
Market priceAED 9,500,000
DiscountAED 950,00010.0% below market
Unit
5-BR + Maid's
Size
4,900 sq.ft
Developer
Gulf Land
Handover
Q4 2026

The discount is measured against the market price recorded for this unit, not against a valuation.

Available
Listed 19 September 2026Status confirmed 17 September 2026

Available when we last checked on 17 September 2026. The asking price shown is the one published when the listing was added on 19 September 2026, -2 days before that check, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.

Interested in distressed property deals?

Ask us anything about this one — the asking price, the payment terms, the running costs, or how it compares with what else is trading nearby. A member of the Mitchell's team will come back with a straight answer and a clear next step. It takes under a minute, and there's no obligation.

Choose one — the next questions adapt to your answer.

Scan or tap to message Mitchell's on WhatsAppScan or tap to chat

Prefer to connect directly?

On this page

Quick navigation

The numbers

Payment breakdown

UNIT PRICE AED 8,550,000

PAYMENTS ON TRANSFER

Payment to seller AED 8,550,000
DLD Transfer fee 4% + 40 AED AED 342,040
DLD Registration Trustee fee + 5% VAT AED 5,250
Buyer's agent commission 2% + 5% VAT AED 179,550

SUMMARY

Total on Transfer AED 9,076,840
TOTAL COST FOR BUYER AED 9,076,840

KEY FACTS

Market price AED 9,500,000
Asking price AED 8,550,000
Discount AED 950,000 (10.0% below market)
Developer Gulf Land
Sub-community Golf City
Property type Villa
Plot 4,900 sq.ft
Structure G+1+R
Bedrooms 5 plus maid's room
Handover Q4 2026

Distress Deal

PROJECT DESCRIPTION

OVERVIEW

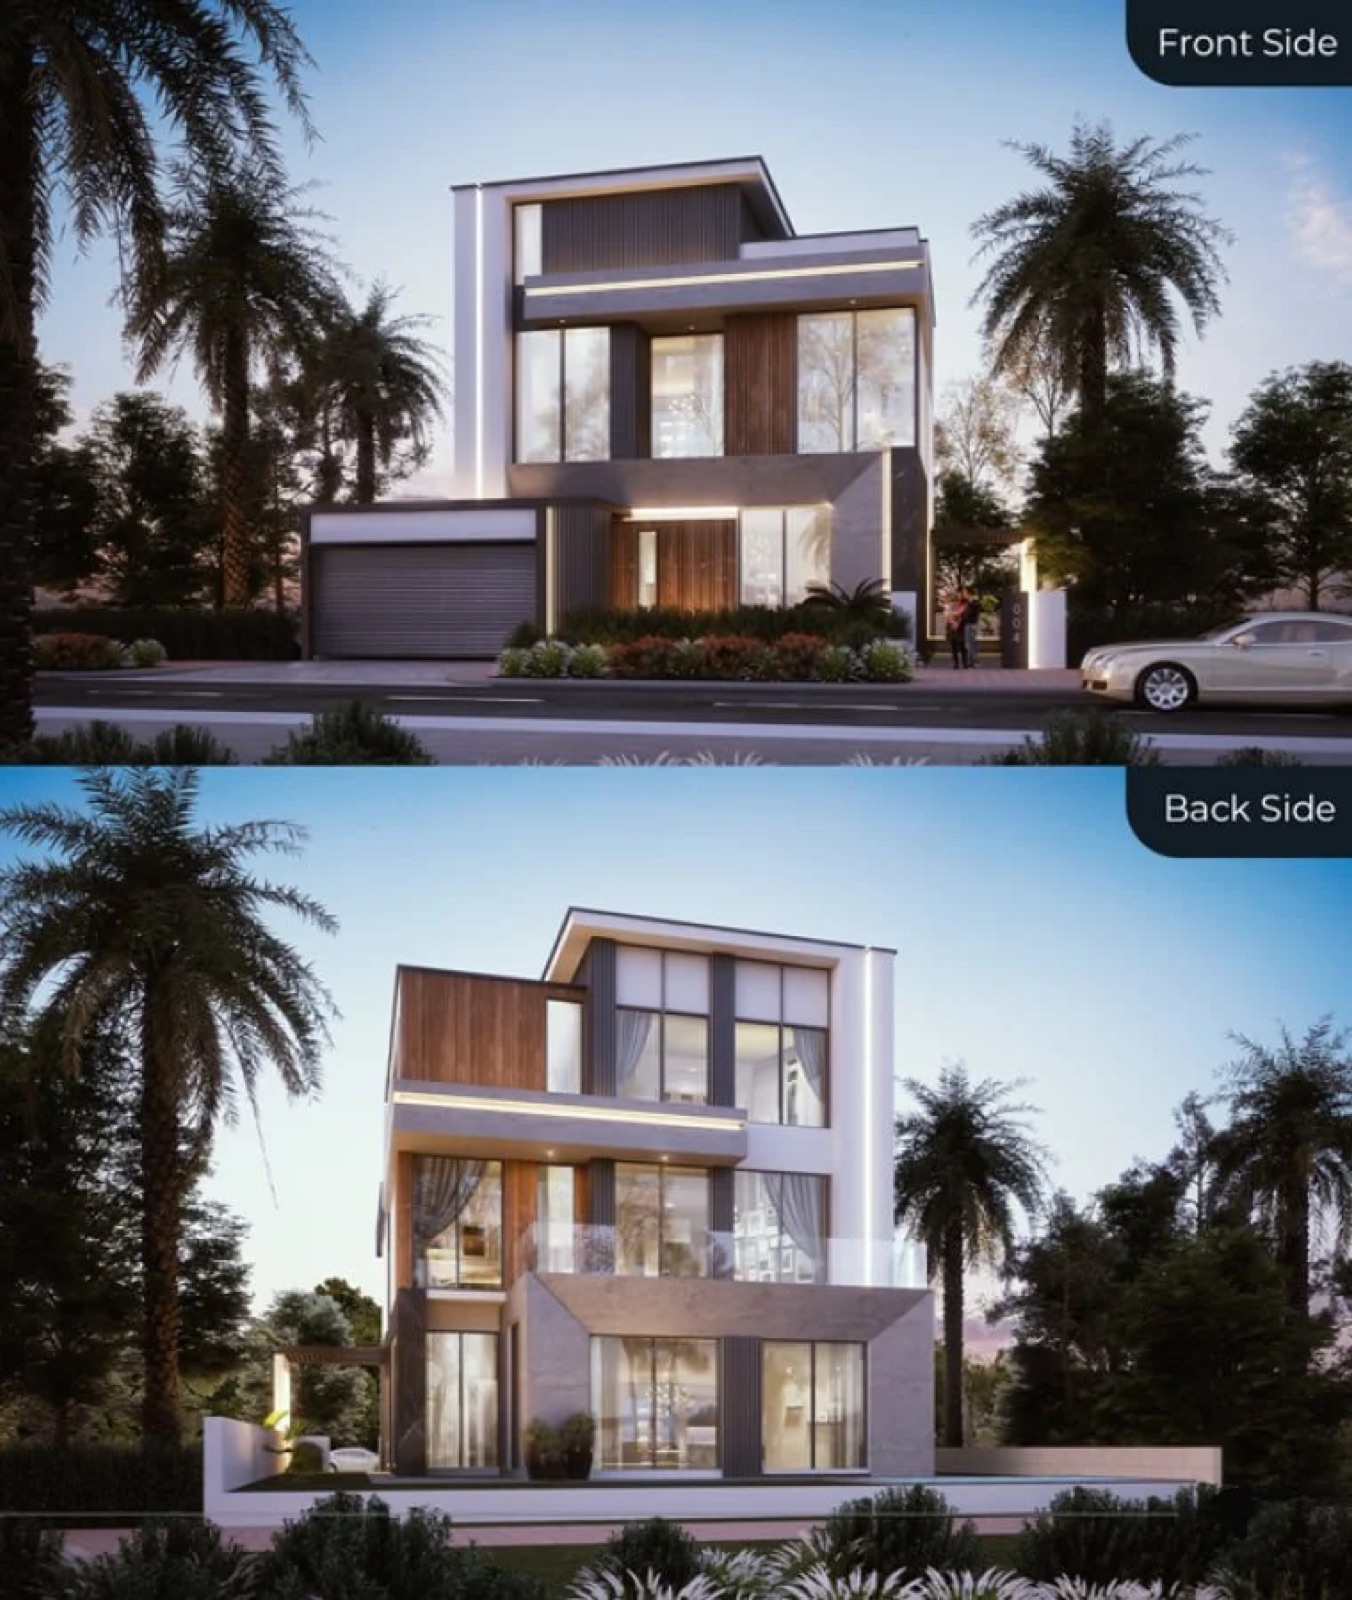
This five-bedroom villa with a maid's room at Paradise Hills, Golf City, is offered at AED 8,550,000 against a market price of AED 9,500,000 — AED 950,000, or 10.0%, below market. The plot is 4,900 sq.ft and the villa is arranged over ground, first floor and roof. The payment structure is the simplest on our books: the full AED 8,550,000 goes to the seller at transfer, there is no developer balance and no instalment plan to inherit, and with DLD, trustee and agency fees the total cost to the buyer is AED 9,076,840. Handover is stated as Q4 2026. The discount is quoted against market rather than an original developer price, which is the appropriate basis where the reference figure is a comparable rather than a first buyer's contract.
LOCATION & TRANSPORT

Golf City sits in the Dubailand corridor in the south-west of the city, part of the belt of low-density villa communities that has expanded steadily along Emirates Road and Sheikh Mohammed Bin Zayed Road. The defining characteristics of this corridor are space and price: plots and built areas are substantially larger for the money than anything comparable closer to the coast, and the trade is journey time. Access is by road, with Emirates Road giving a route north towards Sharjah and south towards Dubai South and the Expo district, and Sheikh Mohammed Bin Zayed Road running parallel closer to the city. There is no metro service in this part of Dubailand and there is unlikely to be one soon, so households here are car-dependent by design. The buyer profile is accordingly an end-user family rather than a yield-focused investor.

AMENITIES & SURROUNDING

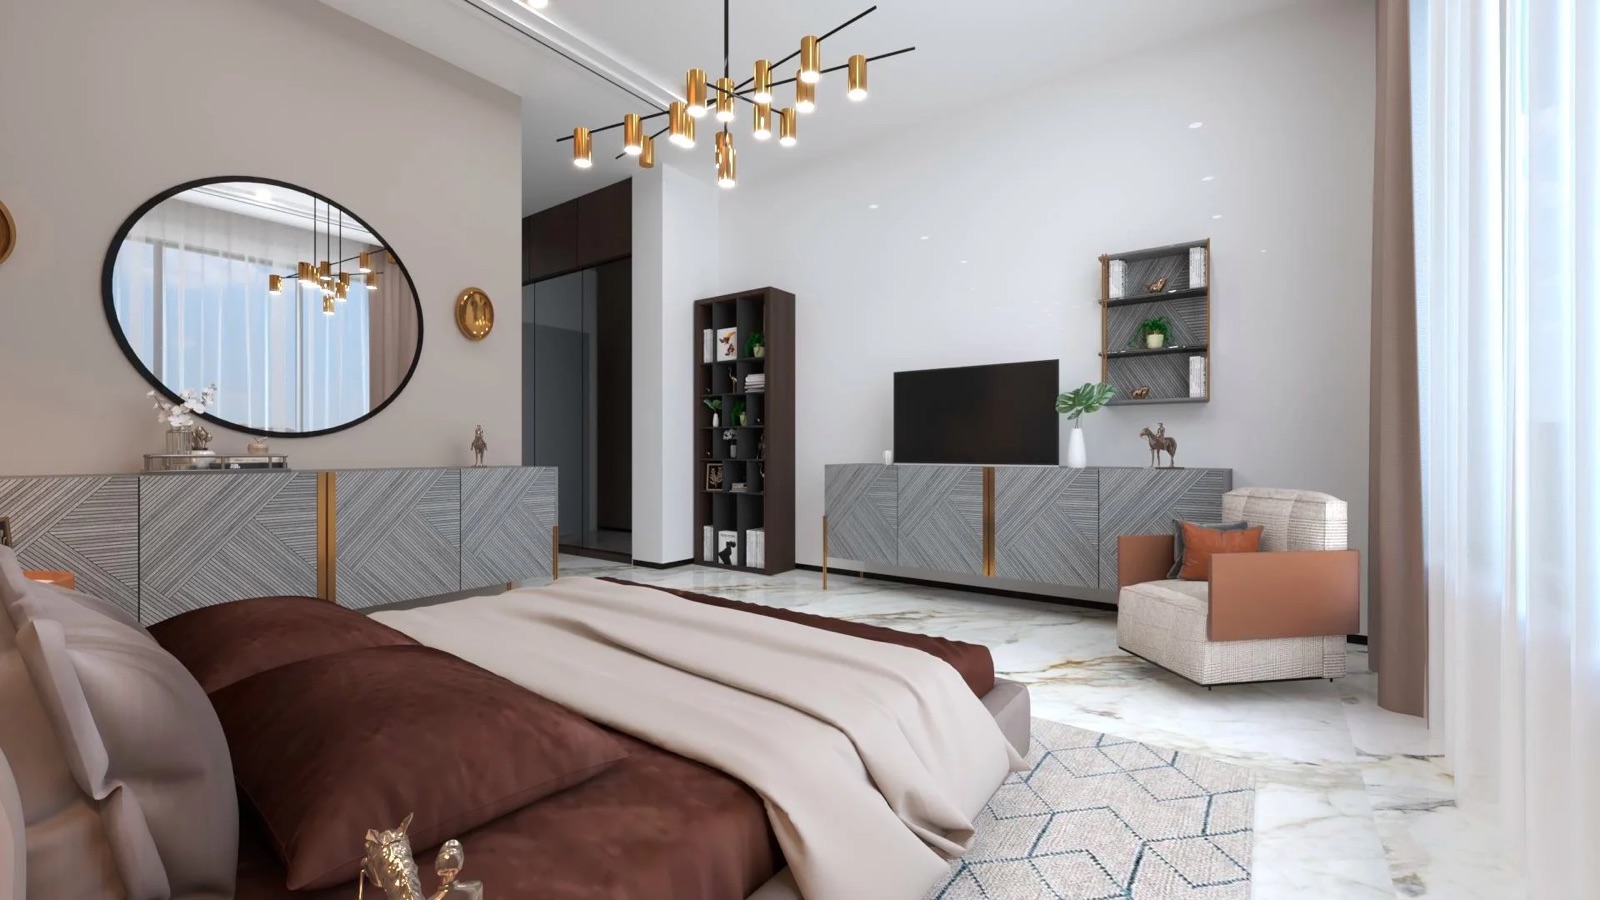
Paradise Hills is a Gulf Land development, and the community is built around the golf-oriented positioning the district's name signals. A G+1+R configuration on a 4,900 sq.ft plot gives a substantial internal area across three levels, with the roof typically delivered as usable terrace, and the maid's room indicates the villa is specified for a family running staff rather than as a downsized product. The wider Dubailand villa belt has matured considerably over the past few years, with schools, clinics and retail arriving behind the housing rather than ahead of it, and a buyer should verify what is actually open today against what the masterplan promises. For a family, the practical questions are school catchment and the state of the internal road network at handover.

MARKET

The source gives a plot area of 4,900 sq.ft but does not state a built-up area, so we have published no price per square foot for this villa. That is deliberate: our rule is that a rate per square foot is calculated on built-up area, never on the plot, and computing one on the plot here would produce AED 1,745 per sq.ft — a figure that looks precise and would be measured on the wrong basis. A buyer wanting a per-foot comparison should obtain the BUA from the developer. On the headline figures, a five-bedroom villa with a maid's room under AED 9m in a completing Dubailand community is competitively positioned against the established villa districts closer in, where the same accommodation carries a materially higher entry. The risks are the district's supply pipeline, which is substantial across the Dubailand villa belt, and the dependence on private transport for every journey a household makes.

CONCLUSION

This suits an end-user family wanting space and a villa footprint at a Dubailand price, completing at the end of 2026. The AED 950,000 reduction is measured against a stated market price rather than an original contract price or our own valuation, and we have not attached one. The single figure worth obtaining before terms are agreed is the built-up area, because without it neither a rate per square foot nor a like-for-like comparison with competing villas is possible. On a villa of this size that single figure also governs the service charge. Floor plan available on request.

Location

PARADISE HILLSGolf City, Dubai

Get Directions

Illustrative model

Scenario modeller

Set your own assumptions and see how DISTRESS DEAL: 5-BR + Maid's IN PARADISE HILLS behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.

Listed
19 September 2026

The date this listing was added to our records. The asking price below is the one published then, and was still -2 days old when we last checked this listing on 17 September 2026. It is not re-checked against the market automatically, so confirm it with us before relying on it.

Handover
Q4 2026

As stated on this listing. Rent cannot start before handover, so on an incomplete unit the early years of the schedule below are holding cost only.

Purchase

Seeded from this page — change it to your figure.

Drives the service charge only.

Rent and service charge both start here.

Holding & income

Your figure — we have not assumed one.

0% holds rent flat. It may be negative.

Your figure — we publish none. A month vacant plus re-letting time is roughly 8%, if that fits your building.

Your figure — we publish none. Letting fees and routine repairs.

Your figure — we publish none. Look your building up on Mollak — rates run AED 3 to AED 30+.

Acquisition costs

4% is the Dubai standard.

Buyer-side. 5% VAT added.

Your figure — we publish none. The trustee tariff is tiered and the admin lines vary by office; ask your trustee office for the total, and add your NOC and any legal quote.

Exit

1 to 40 years.

0% by default: we publish no price forecasts.

5% VAT added automatically.

Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 9.07M
Price plus every acquisition cost
Illustrative exit price
AED 8.55M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
Set a gross annual rent
Cash out, and cash back over 5 years
Cash out at t0AED 9,071,550
Cash back, years 1–5

Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.

Cash required at completion
Purchase priceAED 8,550,000
DLD transfer fee (4%)AED 342,000
Agency fee (2%)AED 171,000
VAT on agency fee (5%)AED 8,550
Conveyancing, trustee & adminAED 0
Total cash investedAED 9,071,550

This is the ROI and IRR denominator: the price plus every cost of getting the keys, not the price alone.

No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.

Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)
Maintenance & management (not set)
Service charge (4,900 sq ft at AED — not set)
Net operating income

Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.

Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete — see note)
YearNet operating incomeSale proceeds, netNet cash flow
0 · today−AED 9,071,550
1AED 0AED 0
2AED 0AED 0
3AED 0AED 0
4AED 0AED 0
5AED 0AED 8,370,450AED 8,370,450
Years 1–5AED 0AED 8,370,450AED 8,370,450
Less the year-0 outflow of AED 9,071,550 → total profit−AED 701,100

Exit at year 5: illustrative sale price AED 8,550,000 less selling costs AED 179,550 = AED 8,370,450 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.

Sensitivity — the same purchase at −5% to +5% exit growth
Exit growthExit priceTotal profitROIIRR
−5% p.a.AED 6.62M
−3% p.a.AED 7.34M
0% p.a.your figureAED 8.55M
3% p.a.AED 9.91M
5% p.a.AED 10.9M

Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.

How each figure is calculated
Handover
The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
Gross yield
Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
Net yield
(Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
Rent growth
Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
ROI
Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
ROE
Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
Cash-on-cash return
Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
IRR
The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.

Email my results

We’ll send this scenario — your assumptions and the figures they produce — to your inbox.

Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.

An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.

Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.

Got questions?

Get Answers!

Read next

A discounted unit is bought the same way any other is — the questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase actually costs.

The gold rule under an entry is its length, against the longest piece here.

Guides

Articles

Need help?