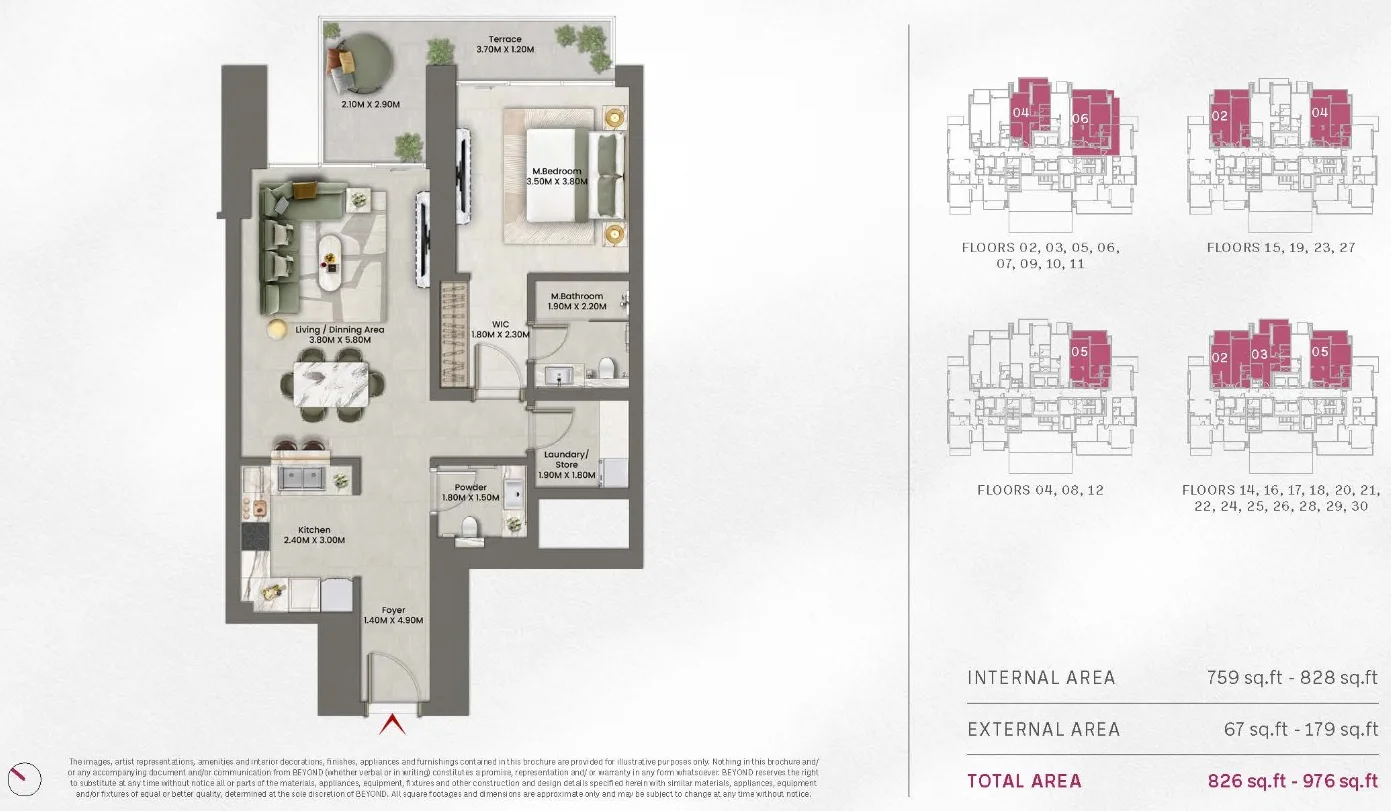
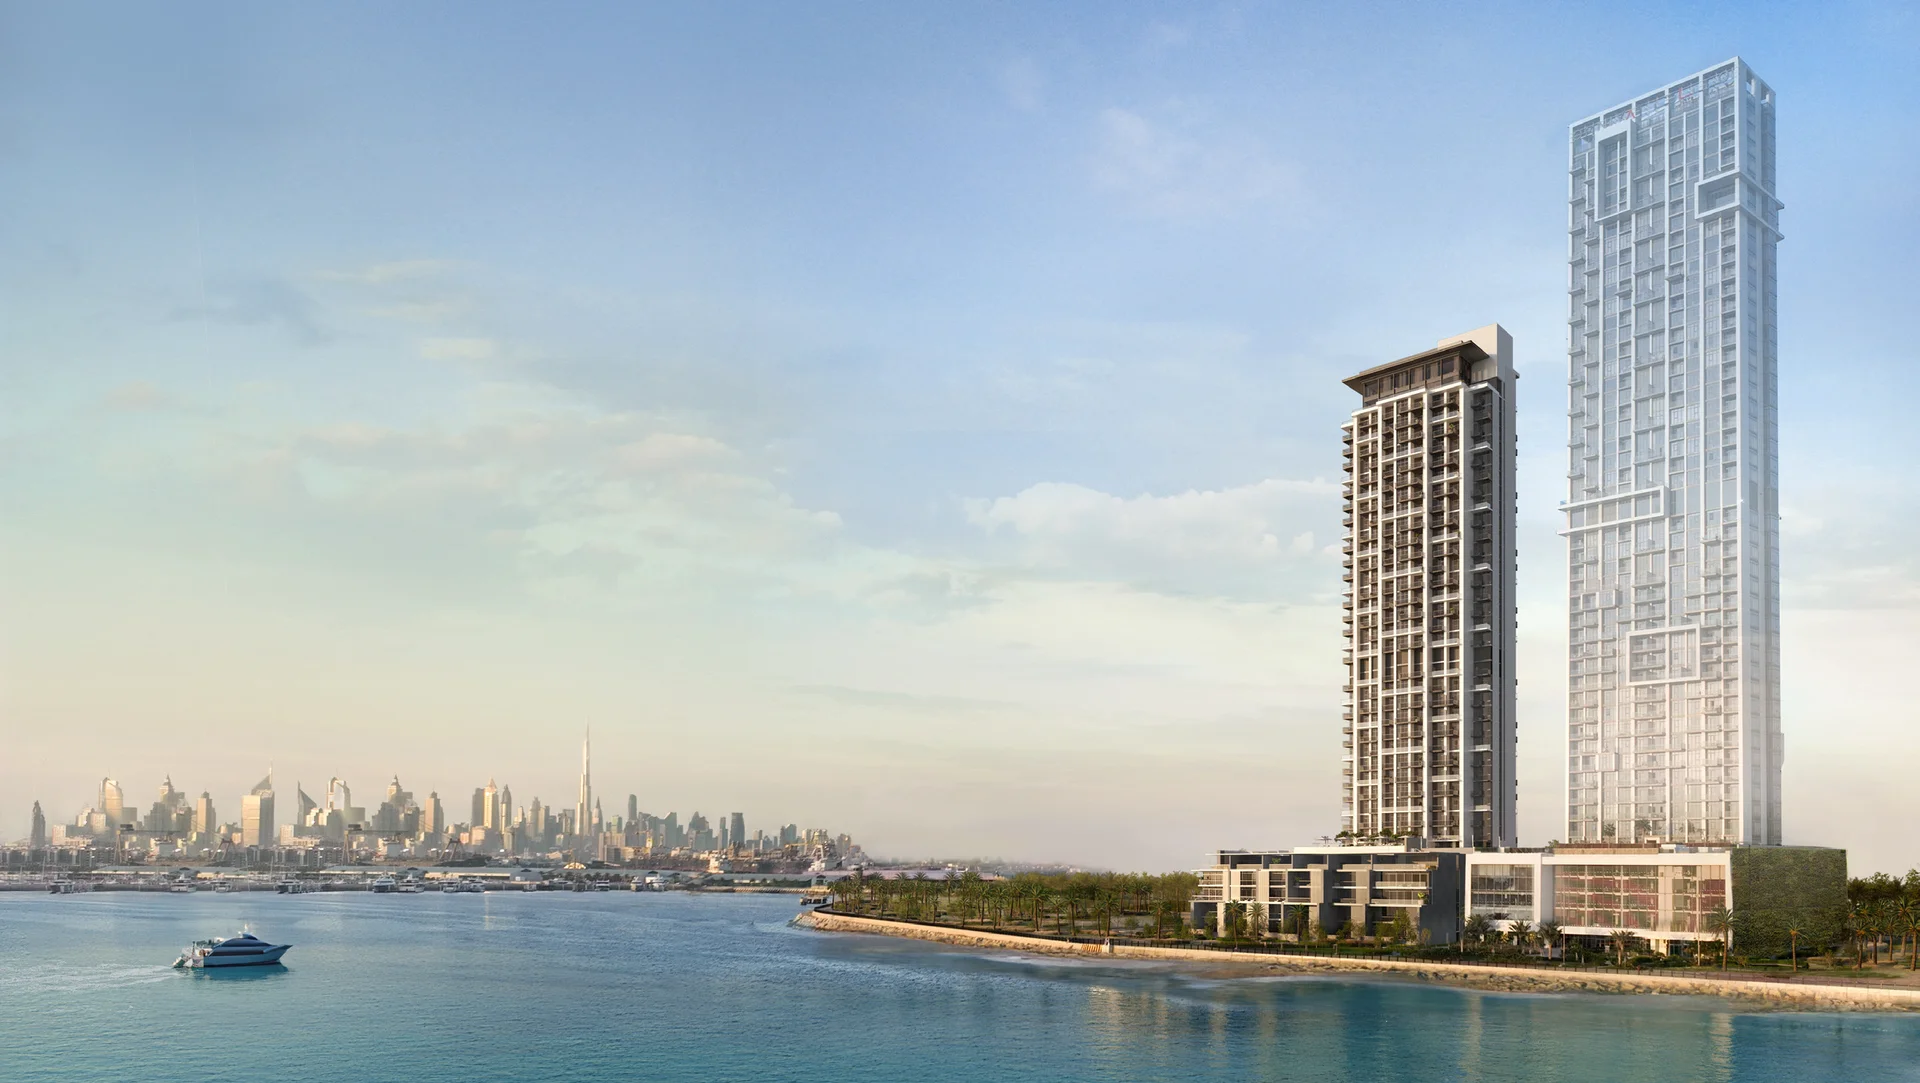
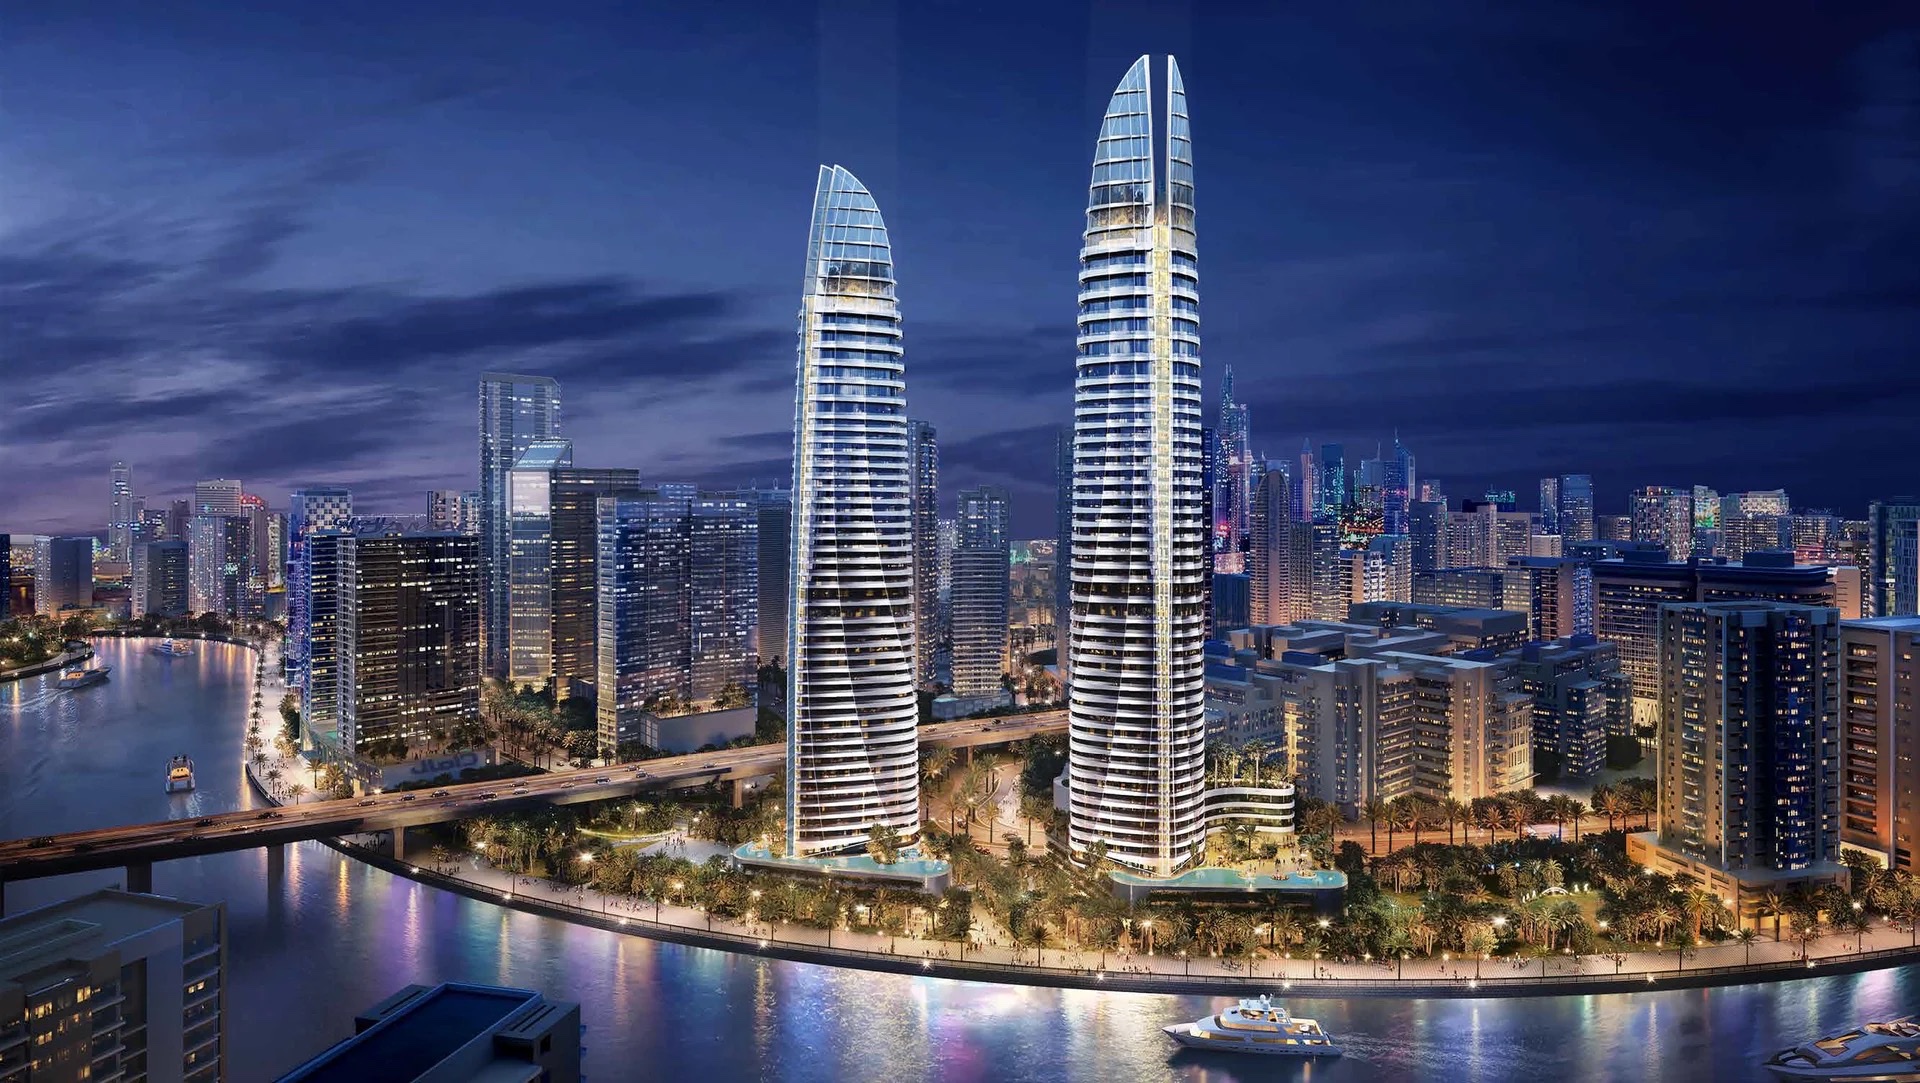
This is a one-bedroom apartment in Anwa Aria, Omniyat's tower in Dubai Maritime City, measuring 826 sq.ft between the 20th and 30th floors with a full sea view and a balcony. The asking price is AED 2,000,000 against an original price plus DLD of AED 2,248,243, a reduction of AED 248,243 or 11.0% below original price. On 826 sq.ft of built-up area that is AED 2,421 per square foot. The payment structure here is unusual for an off-plan resale: the buyer settles AED 944,786 at transfer, of which AED 811,025 goes to the seller, and then carries AED 1,188,975 across five further instalments running from October 2026 to 360 days after completion. Total cost to the buyer is AED 2,133,761, with handover scheduled for Q1 2027.
Available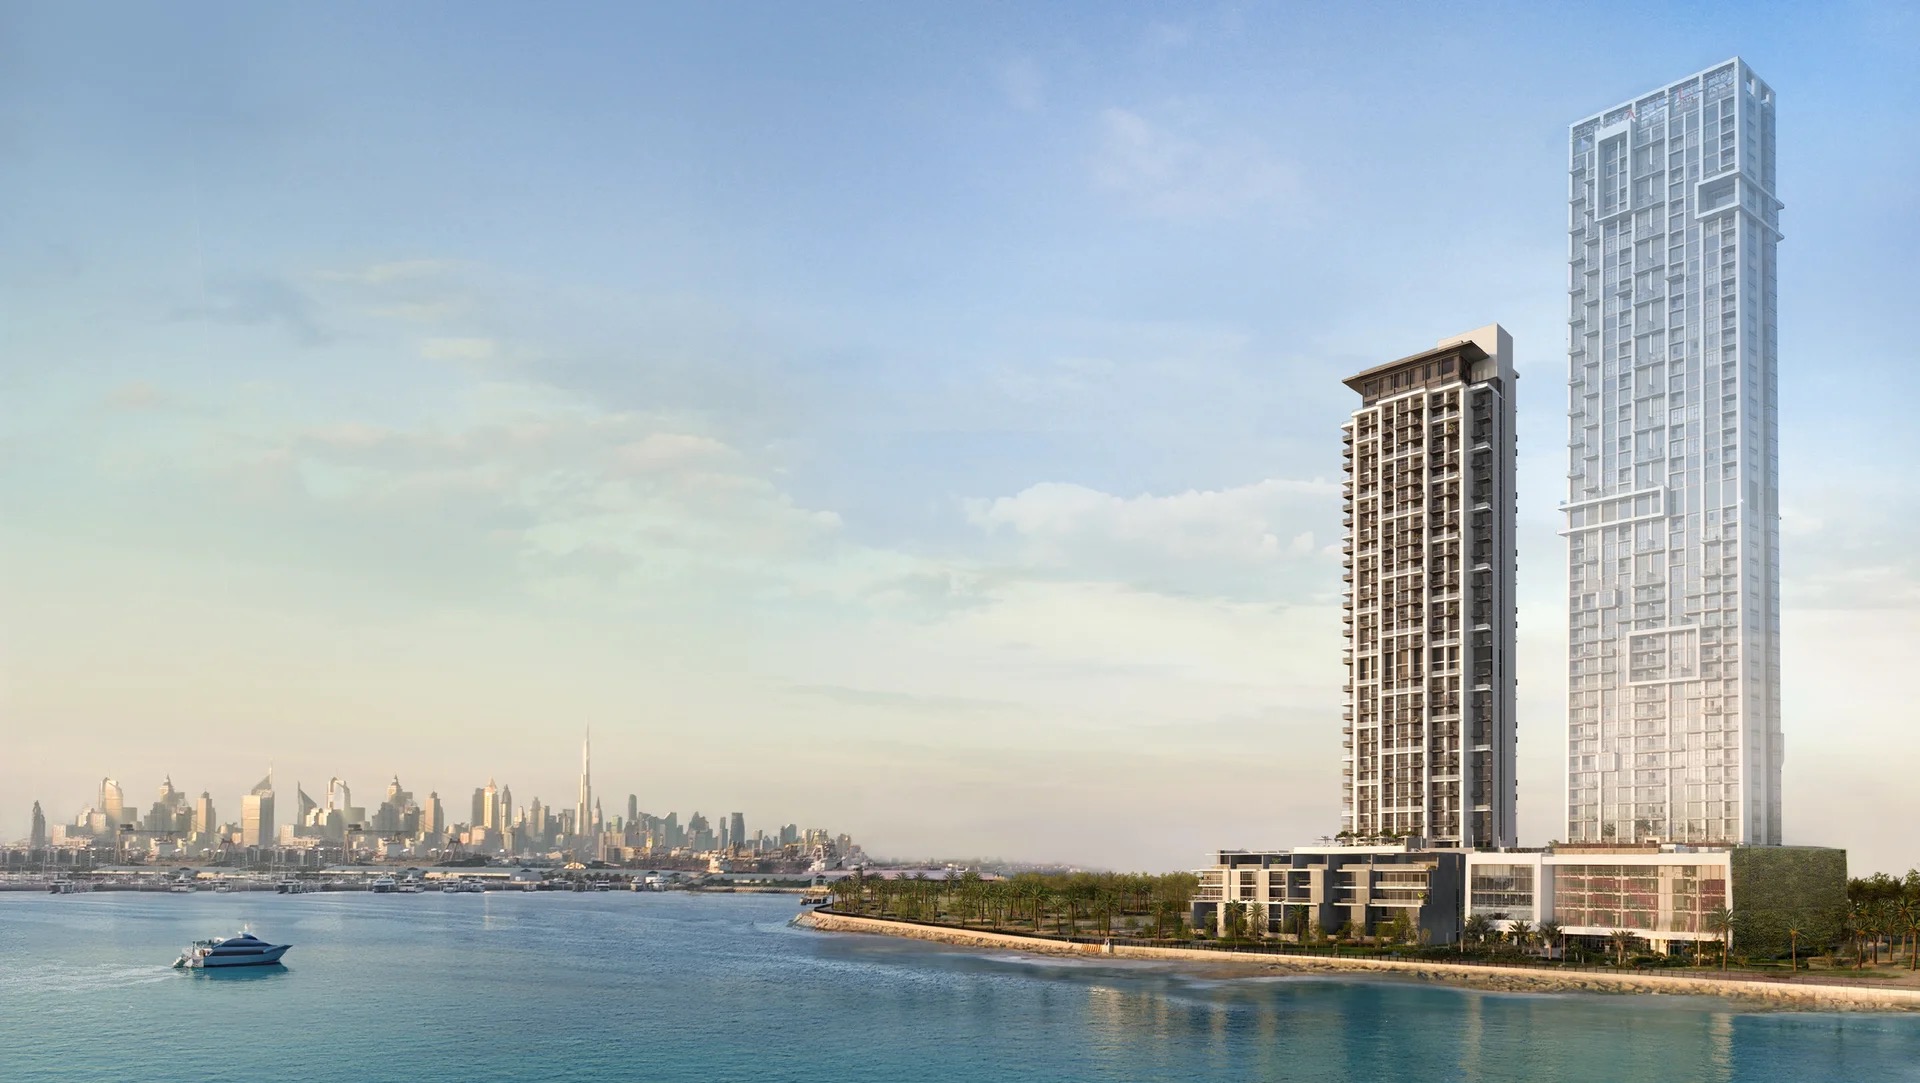 ANWA ARIA (826 SQ FT) · Maritime City1 / 2
Omniyat · Maritime City
DISTRESS DEAL: 1-BR IN ANWA ARIA (826 SQ FT)
Asking priceAED 2,000,000AED 2,421 per sq.ft
Original price + DLDAED 2,248,243
DiscountAED 248,24311.0% below original price
- Unit
- 1-BR
- Size
- 826 sq.ft
- Developer
- Omniyat
- Handover
- Q1 2027
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
Available
Listed 17 September 2026Status confirmed 17 September 2026
Available when we last checked on 17 September 2026. The asking price shown is the one published when the listing was added on 17 September 2026, 0 days before that check, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.
On this page
Quick navigation
The numbers
Payment breakdown
Total cost for buyerAED 2,133,761The unit price plus the transfer fees and commission — the whole commitment, not the headline.
Unit priceAED 2,000,000
Fees and commissionAED 133,761
Step 01Due at transferAED 944,786Payable when the unit transfers to the buyer.
- Payment to sellerAED 811,025
- DLD Transfer fee (4% of OP + 40 AED)AED 86,511
- Trustee Office FeeAED 5,250
- Buyer's Agency Commission (2% + VAT)AED 42,000
- Total on transferAED 944,786
Step 02Payable to Omniyat after transferAED 1,188,975The balance of the payment plan, which the buyer takes over.
- 16-OCT-2026AED 216,177
- 16-APR-2027AED 108,089
- On HandoverAED 432,355
- 180 days post completionAED 216,177
- 360 days post completionAED 216,177
- Total remaining payment planAED 1,188,975
Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.
Ask about these termsPhotography
Gallery
Layout
Floor plan
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
Dubai Maritime City is a reclaimed peninsula set between Port Rashid and the Dubai Drydocks, surrounded by water on three sides. Al Mina Road and Sheikh Rashid Road connect the district into the city network, with Downtown Dubai and DIFC a short drive south-east and Jumeirah immediately west. The Green Line metro stations at Al Ghubaiba and Al Fahidi serve the adjoining Bur Dubai districts, and the creek abras, Dubai Museum and the Al Fahidi historic quarter are minutes away. Dubai International Airport is around twenty minutes by car outside peak hours. The district remains under construction, and buyers here are taking a position in a waterfront address ahead of the masterplan's completion rather than after it.
AMENITIES & SURROUNDING
Anwa Aria is an Omniyat tower, and the unit's principal attribute is its outlook: a full sea view from the 20th to 30th floor band, with a balcony. That is a materially better aspect than a partial or community view and it is the reason this 826 sq.ft unit prices close to the larger 935 sq.ft apartment in the same building. Residential towers in Maritime City are typically built with pool decks, gymnasiums and landscaped podium levels, with the waterfront itself the defining feature. The surrounding masterplan is planned around a marina, promenades and mixed-use retail. Mina Rashid and its marina development sit immediately adjacent, and the established retail, schooling and dining of Bur Dubai and Jumeirah are both a short drive away. Service charge levels in new Maritime City towers are not yet established over a full cycle, which is worth allowing for in any yield calculation.
MARKET
Two units in the same tower are currently listed, and the comparison is instructive: this one is smaller at 826 sq.ft but carries a full sea view, and prices at AED 2,421 per square foot against AED 2,317 for the 935 sq.ft apartment. The aspect is carrying the premium. An 11.0% reduction against original price plus DLD is a solid discount, but the payment shape is the thing to weigh. Unlike most units here, this one has instalments extending 360 days beyond completion, so a buyer is still paying into 2028 on a unit handing over in Q1 2027. That can be an advantage for a buyer intending to let the apartment and service the tail from rent, and a disadvantage for one intending to resell at handover. It is also worth noting that both Anwa Aria units on the market come from separate sellers rather than from the developer, so the discounts reflect individual circumstances rather than a project-wide repricing. That is usually a better sign for the underlying asset than a developer-led reduction.
CONCLUSION
This unit suits a buyer who values the full sea aspect and prefers to spread the cost rather than settle it in a lump. The post-completion instalments mean less capital is required at transfer than for most comparable units, and an apartment let from Q1 2027 could service part of the remaining schedule from rent. Against that, the discount is smaller than on the larger unit in the same tower, the district is unfinished, and the payment tail restricts a quick resale. Every figure is taken from the seller's published listing and should be confirmed with us. We can provide the floor plan, the full instalment schedule and an introduction to the seller's agent. We can also confirm whether the outstanding instalments can be settled early without penalty.
Location
ANWA ARIA (826 SQ FT) — Maritime City, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 1-BR IN ANWA ARIA (826 SQ FT) behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Listed
17 September 2026
The date this listing was added to our records. The asking price below is the one published then, and was still 0 days old when we last checked this listing on 17 September 2026. It is not re-checked against the market automatically, so confirm it with us before relying on it.
Below original price
11.0%
As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.
Asking price per sq.ft
AED 2,421/sqft
The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.
Handover
Q1 2027
As stated on this listing. Rent cannot start before handover, so on an incomplete unit the early years of the schedule below are holding cost only.
Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 2.12M
Price plus every acquisition cost
Illustrative exit price
AED 2M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
—
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
—
Set a gross annual rent
Cash out, and cash back over 5 years
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
Cash required at completion
Purchase priceAED 2,000,000
DLD transfer fee (4%)AED 80,000
Agency fee (2%)AED 40,000
VAT on agency fee (5%)AED 2,000
Conveyancing, trustee & adminAED 0
Total cash investedAED 2,122,000
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)—
Maintenance & management (not set)—
Service charge (826 sq ft at a rate not yet set)—
Net operating income—
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 2,122,000 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 1,958,000 | AED 1,958,000 |
| Years 1–5 | AED 0 | AED 1,958,000 | AED 1,958,000 |
| Less the year-0 outflow of AED 2,122,000 → total profit | −AED 164,000 | ||
Exit at year 5: illustrative sale price AED 2,000,000 less selling costs AED 42,000 = AED 1,958,000 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 1.55M | — | — | — |
| −3% p.a. | AED 1.72M | — | — | — |
| 0% p.a.your figure | AED 2M | — | — | — |
| 3% p.a. | AED 2.32M | — | — | — |
| 5% p.a. | AED 2.55M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Damac Islands
DISTRESS DEAL: 6-BR IN BORA BORA 4
AED 6,578,000AED 6,100,000Asking price
7.3%Below O.P.
- Size
- 4,440 sq.ft
- Price / sq.ft
- AED 1,374
- Developer
- Damac
Bluewaters Island
DISTRESS DEAL: 1-BR + STORAGE IN BLUEWATERS BAY - BUILDING 2
AED 3,390,400AED 3,160,000Asking price
6.8%Below O.P.
- Price / sq.ft
- AED 3,450
- Developer
- Meraas
Business Bay
DISTRESS DEAL: 1-BR IN CANAL HEIGHTS
AED 2,263,683AED 2,050,000Asking price
9.4%Below O.P.
- Size
- 736 sq.ft
- Price / sq.ft
- AED 2,785
- Developer
- DAMAC
- Handover
- Q2 2027
Bluewaters Island
DISTRESS DEAL: 2-BR + Maid's IN BLUEWATERS BAY - BUILDING 2
AED 5,677,360AED 5,359,000Asking price
5.6%Below O.P.
- Size
- 1,670 sq.ft
- Price / sq.ft
- AED 3,209
- Developer
- Meraas
Rashid Yachts & Marina
DISTRESS DEAL: 2-BR IN MARINA PLACE PHASE 2
AED 5,080,284AED 4,350,000,Asking price
14.4%Below O.P.
- Size
- 1,323 sq.ft
- Price / sq.ft
- AED 3,288
- Developer
- Emaar
- Handover
- Q4 2028
Emaar South
DISTRESS DEAL: 4-BR + Maid's IN GREENRIDGE
AED 3,649,244AED 3,250,000Asking price
10.9%Below O.P.
- Size
- 2,700 sq.ft
- Price / sq.ft
- AED 1,204
- Developer
- Emaar
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.