Palm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO SEP 2026
DISTRESS DEAL: 2-BR IN VELA VIENTO

Distress Deal

DISTRESS DEAL: 2-BR IN VELA VIENTO

Asking PriceAED 16,300,000
Below Original Price17.4%
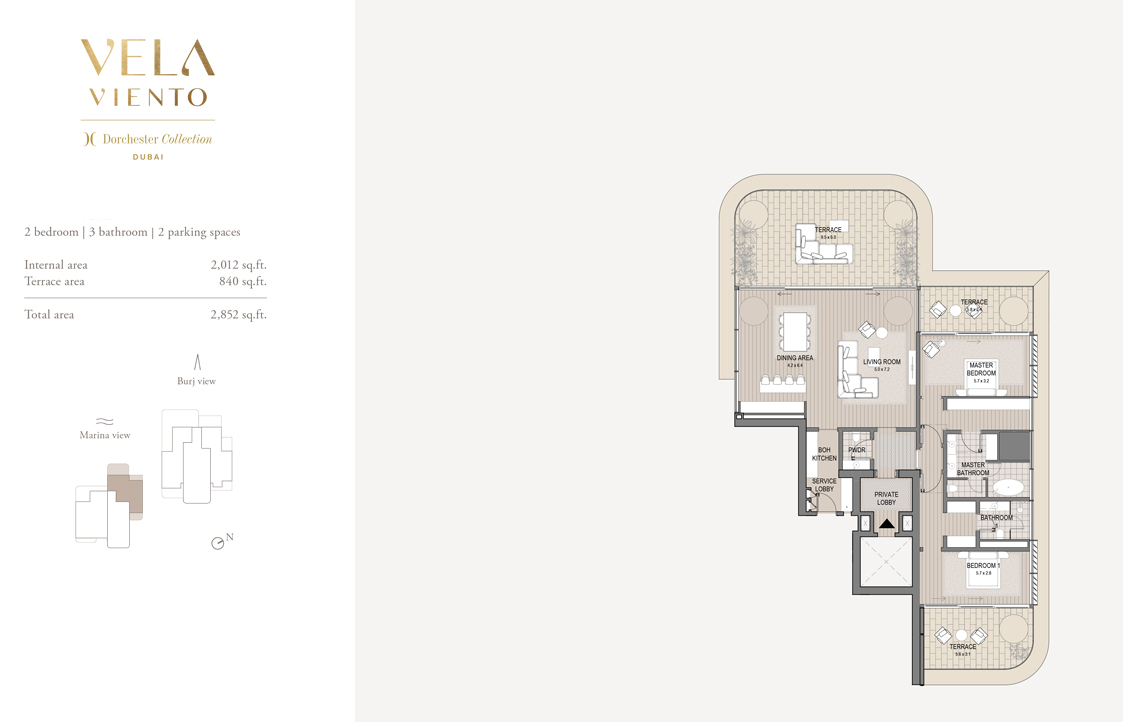
Size2,852 sq.ft
Bedrooms2
Price / Sq.FtAED 5,715
Available
Listed 17 June 2026Status confirmed 3 August 2026

Available when we last checked on 3 August 2026. The asking price shown is the one published when the listing was added on 17 June 2026, 47 days before that check, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.

Interested in DISTRESS DEAL: 2-BR IN VELA VIENTO?

Ask us anything about this one — the asking price, the payment terms, the running costs, or how it compares with what else is trading nearby. A member of the Mitchell's team will come back with a straight answer and a clear next step. It takes under a minute, and there's no obligation.

Choose one — the next questions adapt to your answer.

Scan or tap to message Mitchell's on WhatsAppScan or tap to chat

Prefer to connect directly?

On this page

Quick navigation

The numbers

Payment breakdown

UNIT PRICE AED 16,300,000

PAYMENTS ON TRANSFER

Payment to seller AED 6,236,415
DLD Transfer fee 4% + 40 AED AED 652,040
DLD Registration Trustee fee + 5%VAT AED 5,250
Buyer's agent comission 2% + 5%VAT AED 342,300

PAYMENT PLAN SCHEDULE

20/10/2026 AED 914,871
On Completion (31/03/2028) AED 9,148,714

SUMMARY

Total on Transfer AED 7,236,005
Total remaining Payment Plan AED 10,063,585
TOTAL COST FOR BUYER AED 17,299,590

Layout

Floor plan

Floor plan for DISTRESS DEAL: 2-BR IN VELA VIENTOFloor planView full size

Floor plan

Floor plan for DISTRESS DEAL: 2-BR IN VELA VIENTO

Distress Deal

PROJECT DESCRIPTION

OVERVIEW

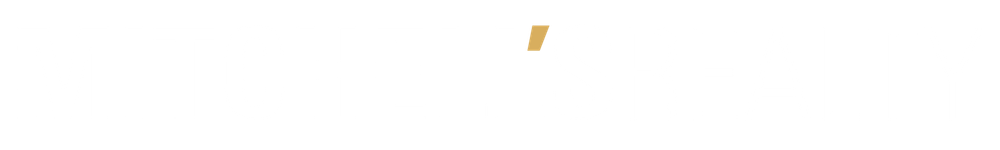
This 2-bedroom apartment in Vela Viento, Business Bay, is being offered as a distress deal at AED 16,300,000. The original price, including DLD fees, was AED 19,727,430, reflecting a 17.4% discount or AED 3,427,430 below the original position. With a generous size of 2,852 sq.ft, the entry basis stands at AED 5,715 per sq.ft. The apartment is situated on a mid-level floor (10-15) and offers direct views of the Burj Khalifa and Dubai Canal, with a balcony included. Handover is scheduled for May 2027, and the payment plan is structured with an initial payment on transfer and further instalments leading up to completion. The immediate investment case is a significant discount to the original price in a high-profile, design-led project by Omniyat, with a large-format 2-bedroom layout and prime views, in a market segment where new supply is tightly held and branded residences are in demand.
LOCATION & TRANSPORT

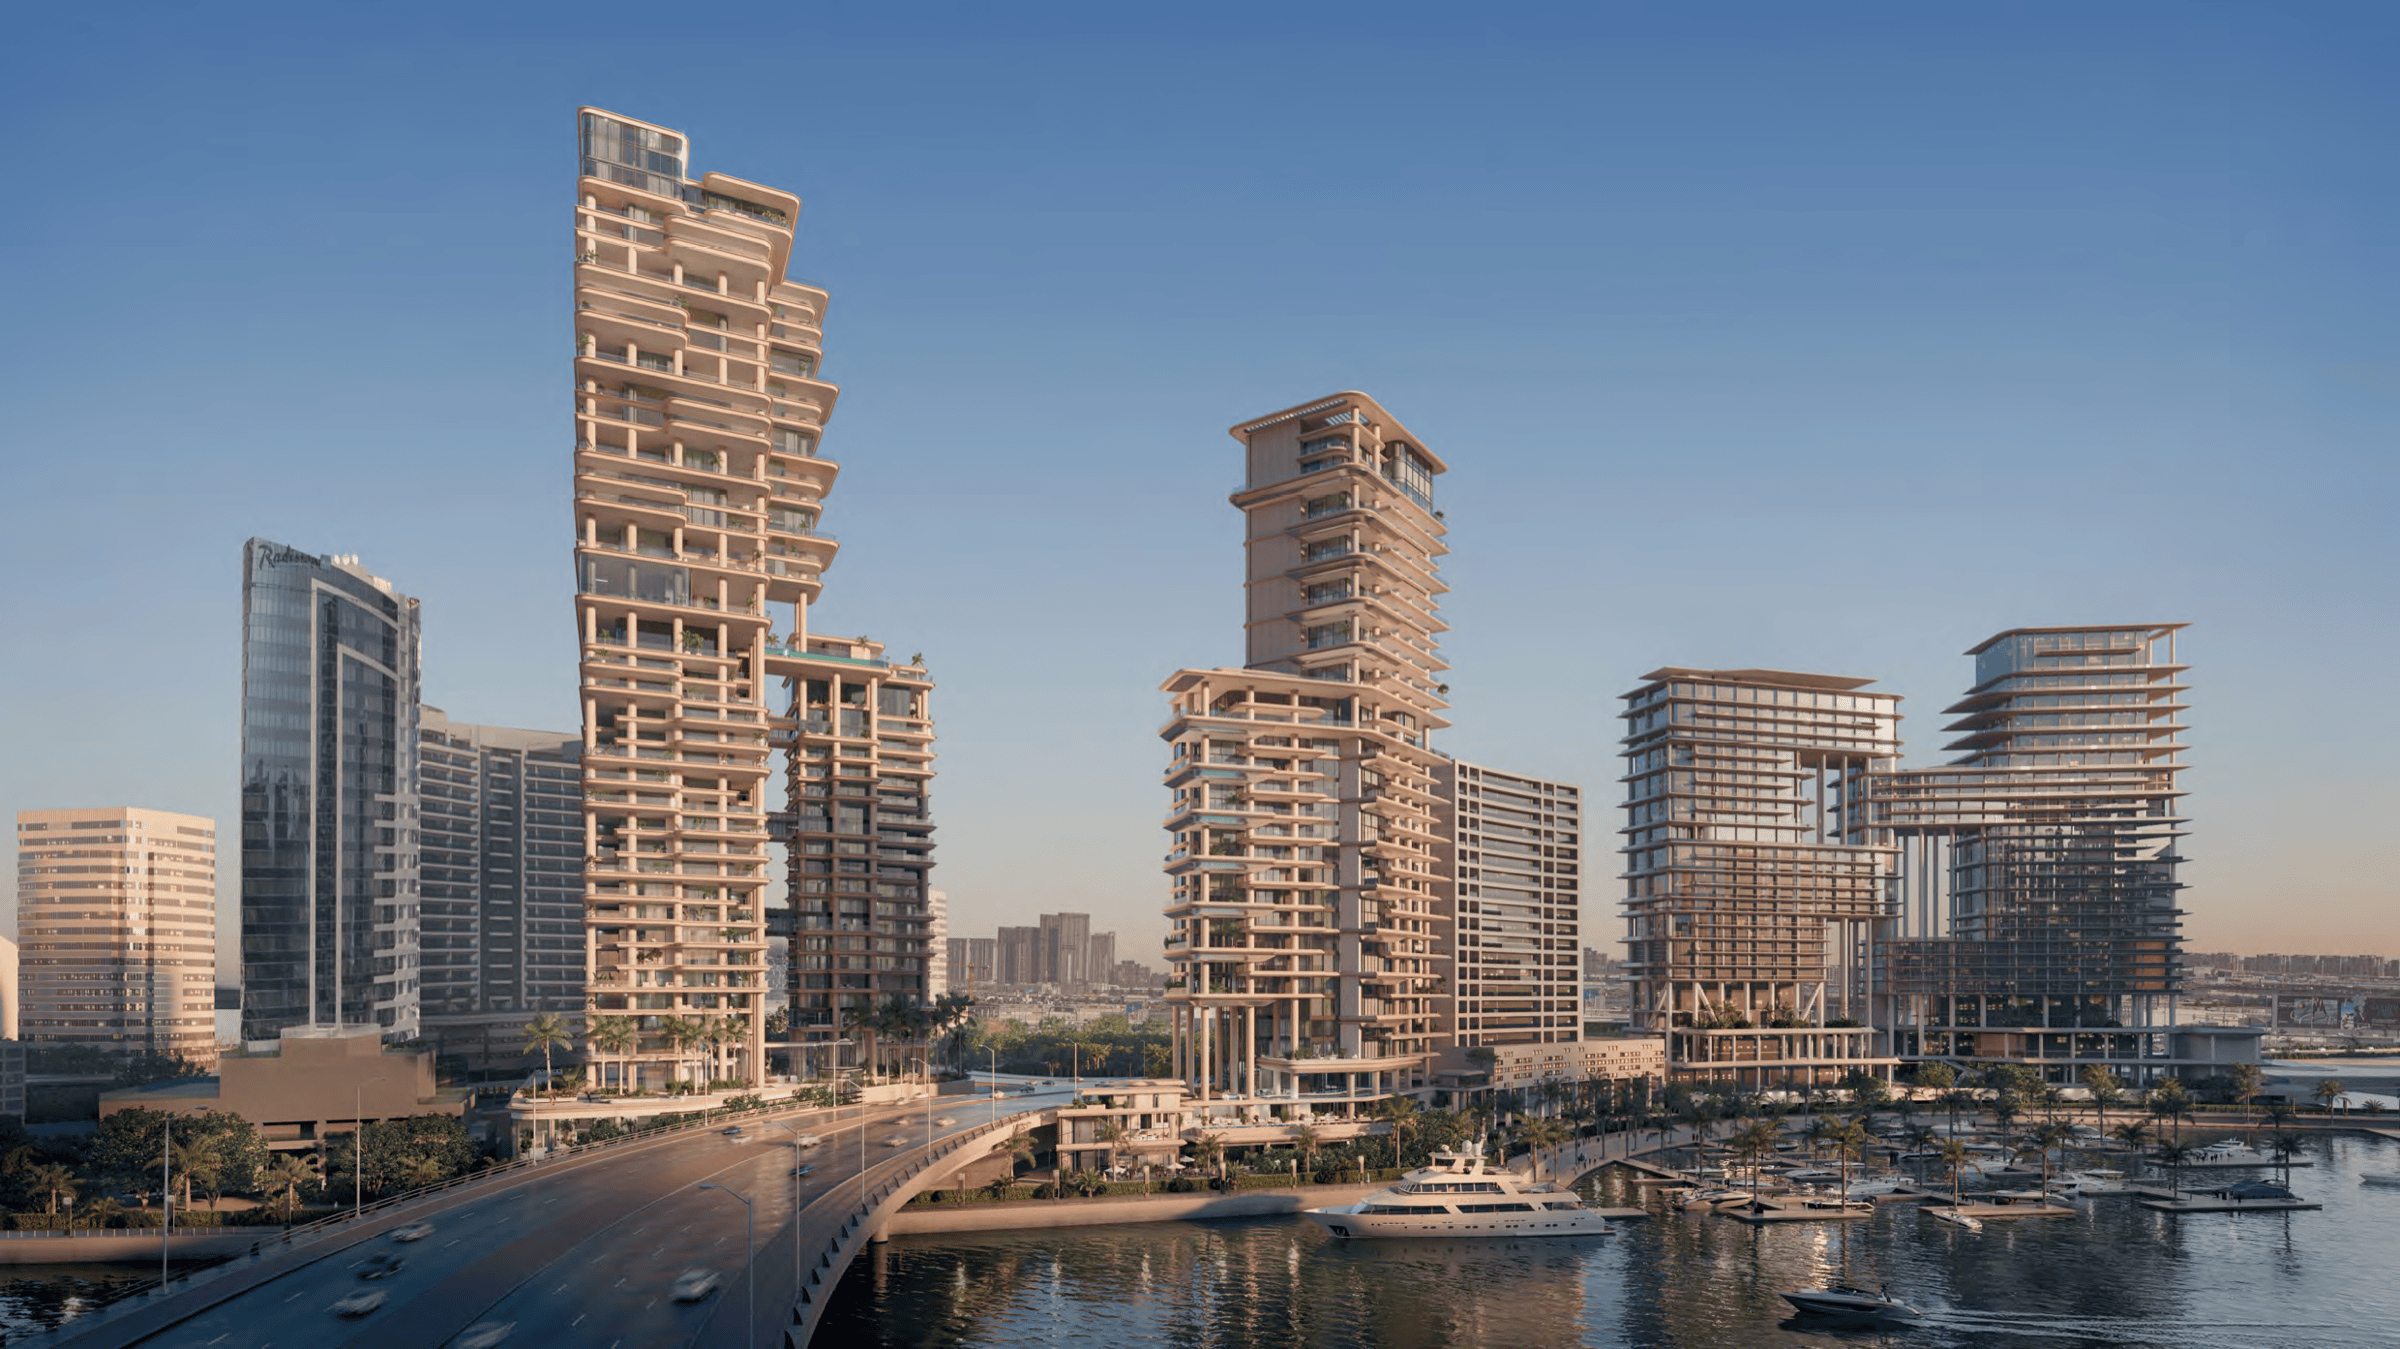
Vela Viento occupies a prominent position in Business Bay, directly on the Marasi Bay waterfront. This location is central to Dubai’s business and leisure districts, with direct road access to Sheikh Zayed Road and Al Khail Road, and proximity to Downtown Dubai, DIFC, and Dubai Mall. The area is well served by taxis, ride-hailing services, and public transport, with the Business Bay Metro Station within reach. The waterfront promenade provides pedestrian connectivity, and residents benefit from the evolving Marasi Bay masterplan, which is set to enhance the area’s walkability and lifestyle offering. For investors, this means a tenant pool that spans professionals, executives, and international residents seeking a central, well-connected address with both city and waterfront appeal.

AMENITIES & SURROUNDING

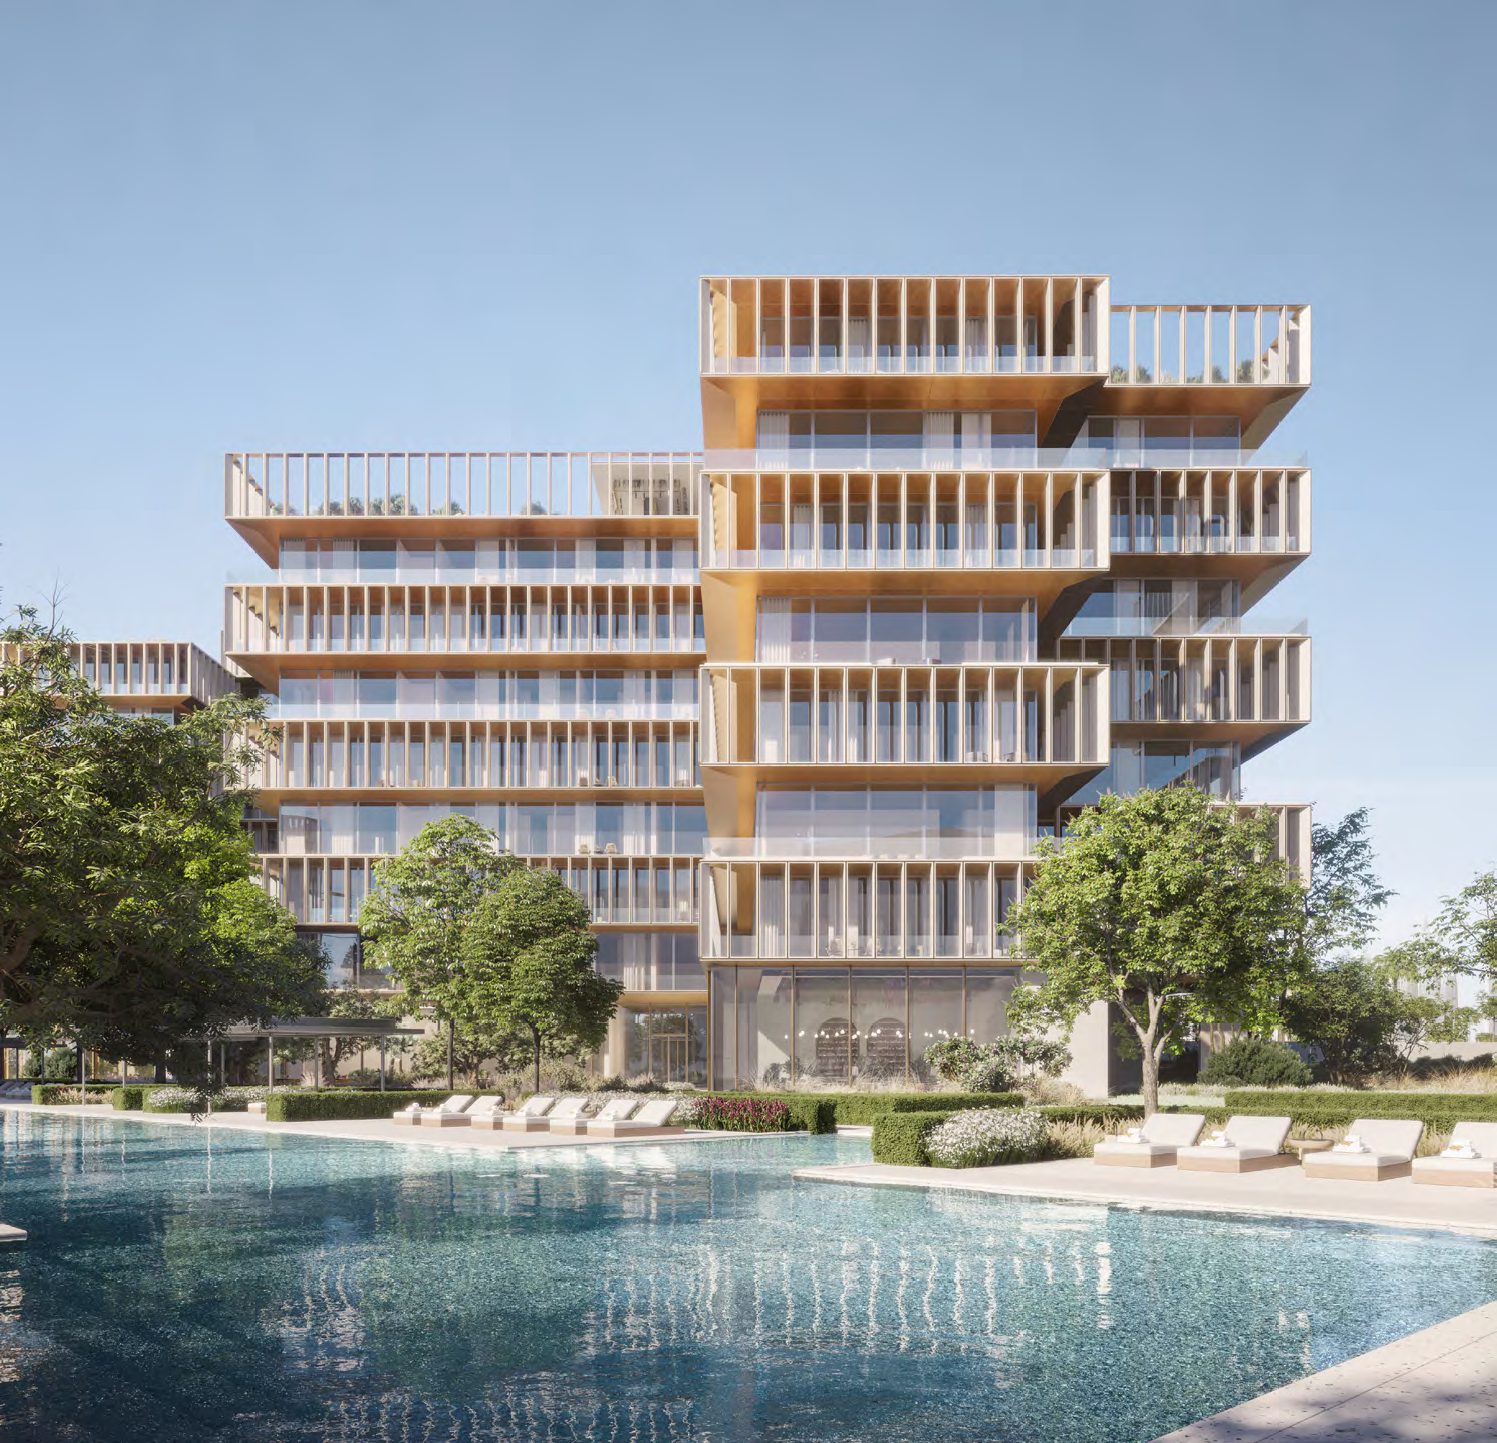
Vela Viento is a 42-storey residential tower developed by Omniyat, with architecture by Foster + Partners and interiors by Gilles & Boissier. The building is designed as a high-amenity, service-led environment, featuring a Sky Amenities Deck 100 metres above ground with an infinity pool, double-height gym, yoga studio, and lounge areas. Residents enjoy 24/7 concierge, doorman, porter, valet parking, and round-the-clock security. There is direct access to the neighbouring Vela and The Lana Hotel amenities via the waterfront promenade, with a golf-buggy service for local transport. Additional à la carte services such as housekeeping, laundry, and maintenance are available, and residents can access selected amenities across other Omniyat properties. The surrounding area includes retail, dining, and leisure options along the canal, with further infrastructure planned as part of the Marasi Bay redevelopment. The building’s amenities and service profile are positioned to attract both end-users and tenants seeking a branded, hospitality-influenced living experience.

MARKET

At AED 5,715 per sq.ft, this unit sits within the upper tier of Dubai’s off-plan branded residence market. Recent transactions in Vela Viento have ranged from AED 5,039 to AED 5,978 per sq.ft, depending on unit size, view, and floor. The 2-bedroom layout at 2,852 sq.ft is notably larger than typical Dubai apartments, appealing to buyers who prioritise space and views. The branded, fully serviced positioning by Omniyat, combined with the architectural pedigree and waterfront location, supports both rentability and resale liquidity. The main buyer profile includes international investors, end-users seeking a central Dubai address, and those looking for a design-led, service-rich environment. Risks to consider include construction and handover timing, service charge levels, and the evolving competitive landscape as more branded projects are delivered in Business Bay and Downtown. However, the discount to original price provides a buffer against short-term market volatility, and the payment plan structure allows for staged capital deployment.

CONCLUSION

This distress deal in Vela Viento offers an investor a meaningful entry discount into one of Business Bay’s most design-forward, amenity-rich developments. The large-format 2-bedroom layout, Burj Khalifa and canal views, and branded service environment position the asset for both rental and resale demand, particularly among international buyers and tenants. The main considerations are the project’s delivery timeline, ongoing service charge commitments, and the broader supply pipeline in the area. If those factors are managed, the case is a disciplined acquisition at a below-market entry point, with the potential for both capital appreciation and income generation as the Marasi Bay area matures. For investors seeking exposure to Dubai’s branded residence segment with a clear discount and a staged payment plan, this opportunity stands out for its scale, views, and service offering.

Illustrative model

Scenario modeller

Set your own assumptions and see how DISTRESS DEAL: 2-BR IN VELA VIENTO behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.

Listed
17 June 2026

The date this listing was added to our records. The asking price below is the one published then, and was still 47 days old when we last checked this listing on 3 August 2026. It is not re-checked against the market automatically, so confirm it with us before relying on it.

Below original price
17.4%

As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.

Asking price per sq.ft
AED 5,715/sqft

The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.

Purchase

Seeded from this page — change it to your figure.

Drives the service charge only.

Rent and service charge both start here.

Holding & income

Your figure — we have not assumed one.

0% holds rent flat. It may be negative.

Your figure — we publish none. A month vacant plus re-letting time is roughly 8%, if that fits your building.

Your figure — we publish none. Letting fees and routine repairs.

Your figure — we publish none. Look your building up on Mollak — rates run AED 3 to AED 30+.

Acquisition costs

4% is the Dubai standard.

Buyer-side. 5% VAT added.

Your figure — we publish none. The trustee tariff is tiered and the admin lines vary by office; ask your trustee office for the total, and add your NOC and any legal quote.

Exit

1 to 40 years.

0% by default: we publish no price forecasts.

5% VAT added automatically.

Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 17.3M
Price plus every acquisition cost
Illustrative exit price
AED 16.3M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
Set a gross annual rent
Cash out, and cash back over 5 years
Cash out at t0AED 17,294,300
Cash back, years 1–5

Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.

Cash required at completion
Purchase priceAED 16,300,000
DLD transfer fee (4%)AED 652,000
Agency fee (2%)AED 326,000
VAT on agency fee (5%)AED 16,300
Conveyancing, trustee & adminAED 0
Total cash investedAED 17,294,300

This is the ROI and IRR denominator: the price plus every cost of getting the keys, not the price alone.

No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.

Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)
Maintenance & management (not set)
Service charge (2,852 sq ft at AED — not set)
Net operating income

Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.

Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete — see note)
YearNet operating incomeSale proceeds, netNet cash flow
0 · today−AED 17,294,300
1AED 0AED 0
2AED 0AED 0
3AED 0AED 0
4AED 0AED 0
5AED 0AED 15,957,700AED 15,957,700
Years 1–5AED 0AED 15,957,700AED 15,957,700
Less the year-0 outflow of AED 17,294,300 → total profit−AED 1,336,600

Exit at year 5: illustrative sale price AED 16,300,000 less selling costs AED 342,300 = AED 15,957,700 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.

Sensitivity — the same purchase at −5% to +5% exit growth
Exit growthExit priceTotal profitROIIRR
−5% p.a.AED 12.6M
−3% p.a.AED 14M
0% p.a.your figureAED 16.3M
3% p.a.AED 18.9M
5% p.a.AED 20.8M

Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.

How each figure is calculated
Handover
The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
Gross yield
Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
Net yield
(Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
Rent growth
Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
ROI
Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
ROE
Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
Cash-on-cash return
Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
IRR
The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.

Email my results

We’ll send this scenario — your assumptions and the figures they produce — to your inbox.

Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.

An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.

Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.

Location

VELA VIENTOBusiness Bay, Dubai

Get Directions

Got questions?

Get Answers!

Read next

A discounted unit is bought the same way any other is — the questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase actually costs.

The gold rule under an entry is its length, against the longest piece here.

Guides

Articles

Need help?