

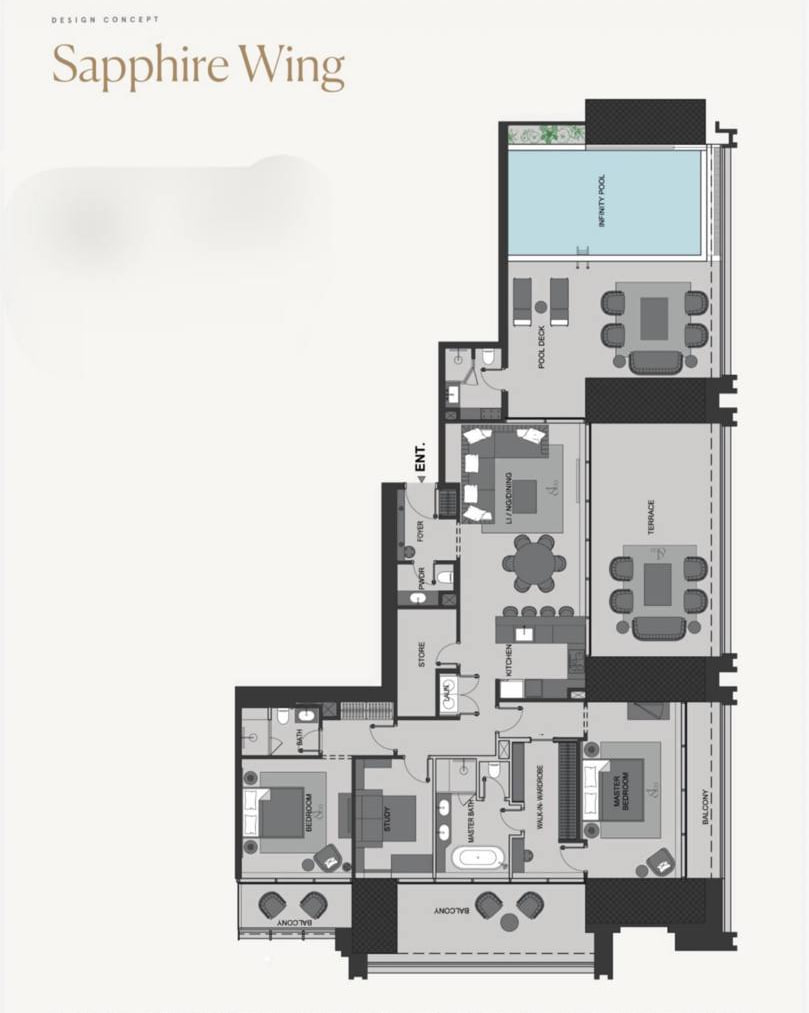
This is a distress deal for a 2-bedroom, 3-bathroom apartment in Burj Binghatti Jacob & Co Residences, Business Bay, offered at AED 7,800,000. The original price was AED 9,172,800, reflecting a 15% discount and an entry point of AED 2,438 per sq.ft for a substantial 3,200 sq.ft layout. The unit is positioned on a mid-level floor and features a creek view, with the added benefit of an infinity pool on the balcony and two parking spaces. Handover is scheduled for Q4 2026, and the payment plan allows for staged payments through to completion. The immediate investment thesis is clear: this is a large, branded residence in a landmark tower, offered below original pricing, with the potential to capture value both from the discount and from the building’s positioning as a future icon in Dubai’s skyline. The buyer is not exposed to early-stage construction risk, as the project is well underway, and the payment plan structure provides flexibility ahead of handover.
 BURJ BINGHATTI JACOB & CO RESIDENCES · Business Bay
Binghatti · Business Bay
DISTRESS DEAL: 2-BR - BURJ BINGHATTI JACOB & CO RESIDENCES
- Unit
- 2-BR
- Size
- 3,200 sq.ft
- Developer
- Binghatti
- Handover
- Q4 2026
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
This unit has sold. The page is kept as a record of a deal we transacted. Every figure on it — the asking price, the discount to original price and the payment schedule — is the position as listed on 15 March 2026 and is historic. It is not an indication of what the same unit, or a comparable one, would cost today.
On this page
Quick navigation
The numbers
Payment breakdown
- Payment to sellerAED 4,889,400
- DLD Transfer fee 4% + 40 AEDAED 312,040
- DLD Registration Trustee fee + 5% VATAED 5,250
- Buyer's agent commission 2% + 5% VATAED 163,800
- Total on transferAED 5,370,490
- Mar-2026AED 88,200
- Apr-2026AED 88,200
- May-2026AED 88,200
- On HandoverAED 2,646,000
- Total remaining payment planAED 2,910,600
This unit has sold. Tell us what you are looking for and we will send the deals that are open now.
Show me deals like this oneLayout
Floor plan
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
Burj Binghatti Jacob & Co Residences is located in Business Bay, one of Dubai’s most central and connected districts. The tower’s site benefits from direct access to the main Business Bay road network, with Sheikh Zayed Road and Al Khail Road both within a short drive, providing fast routes to Downtown Dubai, DIFC, and Dubai International Airport. Public transport options include nearby metro stations and regular taxi and ride-hailing services, supporting both resident and tenant mobility. The Business Bay area is known for its mixed-use character, combining residential, commercial, and hospitality offerings, which broadens the appeal for both end-users and investors. The central location underpins both rental demand and resale liquidity, as Business Bay continues to mature as a core urban district in Dubai’s property landscape.
AMENITIES & SURROUNDING
The Burj Binghatti Jacob & Co Residences project is designed as a supertall, 104-storey residential tower, developed in partnership with Binghatti and luxury jeweller Jacob & Co. Amenities are positioned at the high end of the Dubai market and include a bodyguard service, butler and chauffeur services, concierge and lounge facilities, a day care centre, gymnasium, housekeeping, an infinity pool, lobby lounge, and spa and sauna. The building’s design and interiors are inspired by Jacob & Co’s signature style, with the illuminated crown referencing the brand’s iconic diamonds. Residents will benefit from a high level of service and security, as well as access to communal and private leisure facilities. The surrounding Business Bay area offers a full suite of urban infrastructure, including retail, dining, and entertainment options, as well as proximity to Dubai Mall, Bay Avenue, and the Dubai Canal promenade.
MARKET
At an entry basis of AED 2,438 per sq.ft, this apartment sits below the original launch pricing for the project and is competitive for branded, large-format apartments in central Dubai. The branded residence sector has seen growing demand from both local and international buyers, attracted by the combination of service, design, and perceived long-term value retention. The 3,200 sq.ft size is notably larger than typical two-bedroom stock, which may appeal to buyers seeking more space or to tenants in the executive and corporate segment. The main underwriting considerations are the project’s completion timeline, service charge levels, and the ability of the branded positioning to support premium rents and resale values. Liquidity in the branded segment can be strong, but is often more sensitive to overall market sentiment and the reputation of the developer and brand. The payment plan structure, with a significant portion due on handover, provides some flexibility for investors managing cash flow ahead of completion.
CONCLUSION
This distress deal offers an investor the opportunity to secure a large, branded apartment in a landmark Business Bay tower at a clear discount to original pricing. The combination of size, branded amenities, and central location positions the asset well for both rental and resale strategies, particularly as the branded residence sector continues to attract attention in Dubai. The main risks are tied to project delivery, service charge levels, and the ability of the brand to sustain premium pricing over time. For buyers comfortable with off-plan exposure and seeking a differentiated product in a maturing urban district, this deal provides a balanced entry point with both immediate discount and long-term positioning potential.
Location
BURJ BINGHATTI JACOB & CO RESIDENCES — Business Bay, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 2-BR - BURJ BINGHATTI JACOB & CO RESIDENCES behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Enter the asking price to run the model.
Every figure recalculates as you type. Use the price you are considering.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Emaar Beachfront
DISTRESS DEAL: 1-BR IN DAMAC BAY - TOWER C
- Price / sq.ft
- AED 3,378
- Developer
- Damac
- Handover
- Q4 2027
Rashid Yachts and Marina
DISTRESS DEAL: 1-BR IN OCEAN POINT - TOWER 2
- Price / sq.ft
- AED 1,908
- Developer
- Emaar
Emaar Beachfront
DISTRESS DEAL: 1-BR IN SEAPOINT - TOWER 2
- Size
- 764 sq.ft
- Price / sq.ft
- AED 3,442
- Developer
- Emaar
- Handover
- Q2 2028
Bluewaters Island
DISTRESS DEAL: 2-BR + Maid's IN BLUEWATERS BAY - BUILDING 1
- Size
- 1,670 sq.ft
- Price / sq.ft
- AED 3,145
- Developer
- Meraas
- Handover
- Q3 2027
Sobha Hartland II
DISTRESS DEAL: 2-BR IN SKYSCAPE ALTIUS
- Size
- 1,268 sq.ft
- Price / sq.ft
- AED 2,129
- Developer
- Sobha
- Handover
- Q4 2028
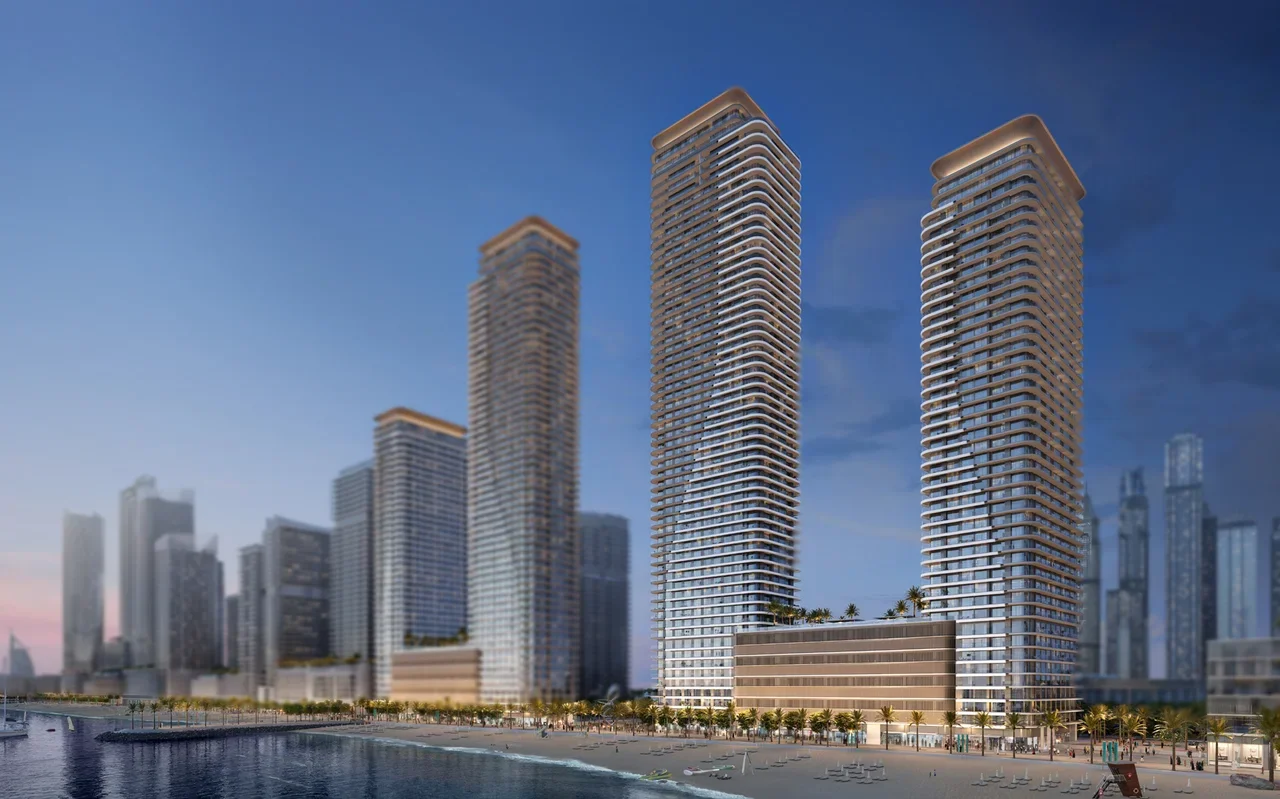
Emaar Beachfront
DISTRESS DEAL: BULK DEAL - 9 APARTMENTS IN BAYVIEW - TOWER 1
- Size
- 10,041 sq.ft
- Price / sq.ft
- AED 4,681
- Developer
- Emaar
- Handover
- Q2 2027
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.