

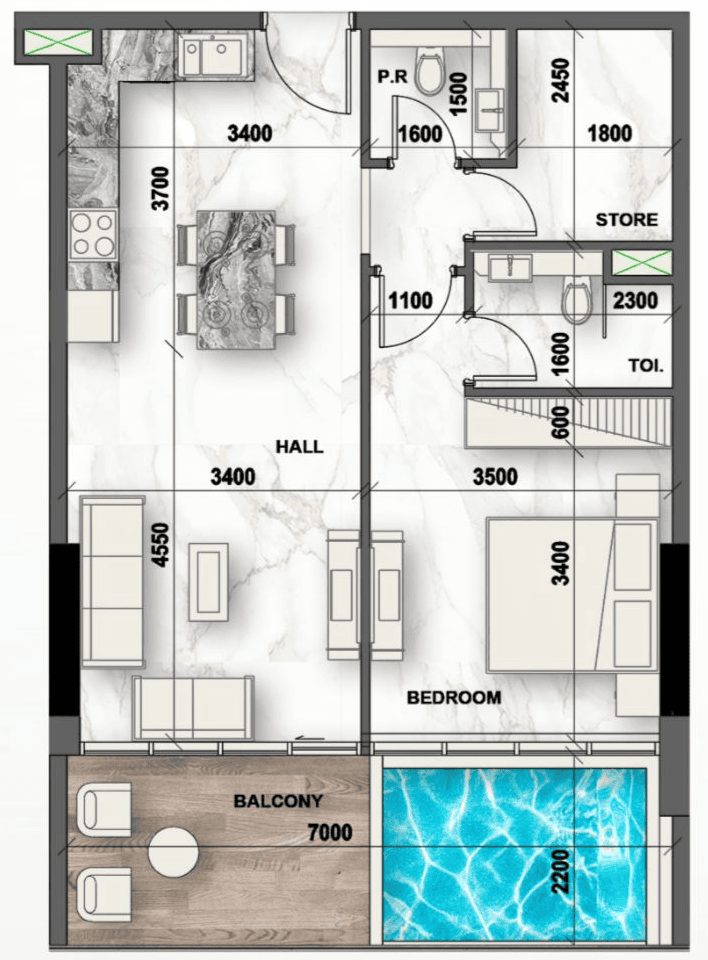
This 1-bedroom apartment in Peace Lagoons, Dubai Land Residence Complex, is offered as a distress deal at AED 850,000. The original price, including DLD fees, was AED 1,040,000, so the current entry point reflects an 18.3% discount, or AED 190,000 below the reference price. With a size of 814 sq.ft, the price per square foot stands at AED 1,044. The unit is positioned on a high floor, with lagoon views and a balcony, and is semi-furnished with built-in appliances, a designer kitchen table, and illuminated wardrobes in the bedroom. Handover is scheduled for Q1 2029, so this is an off-plan position with a payment plan structure. The immediate investment thesis is a below-market entry into a new-build, amenity-led project, with a payment schedule that reduces upfront capital outlay and provides exposure to a maturing residential corridor in Dubai Land.
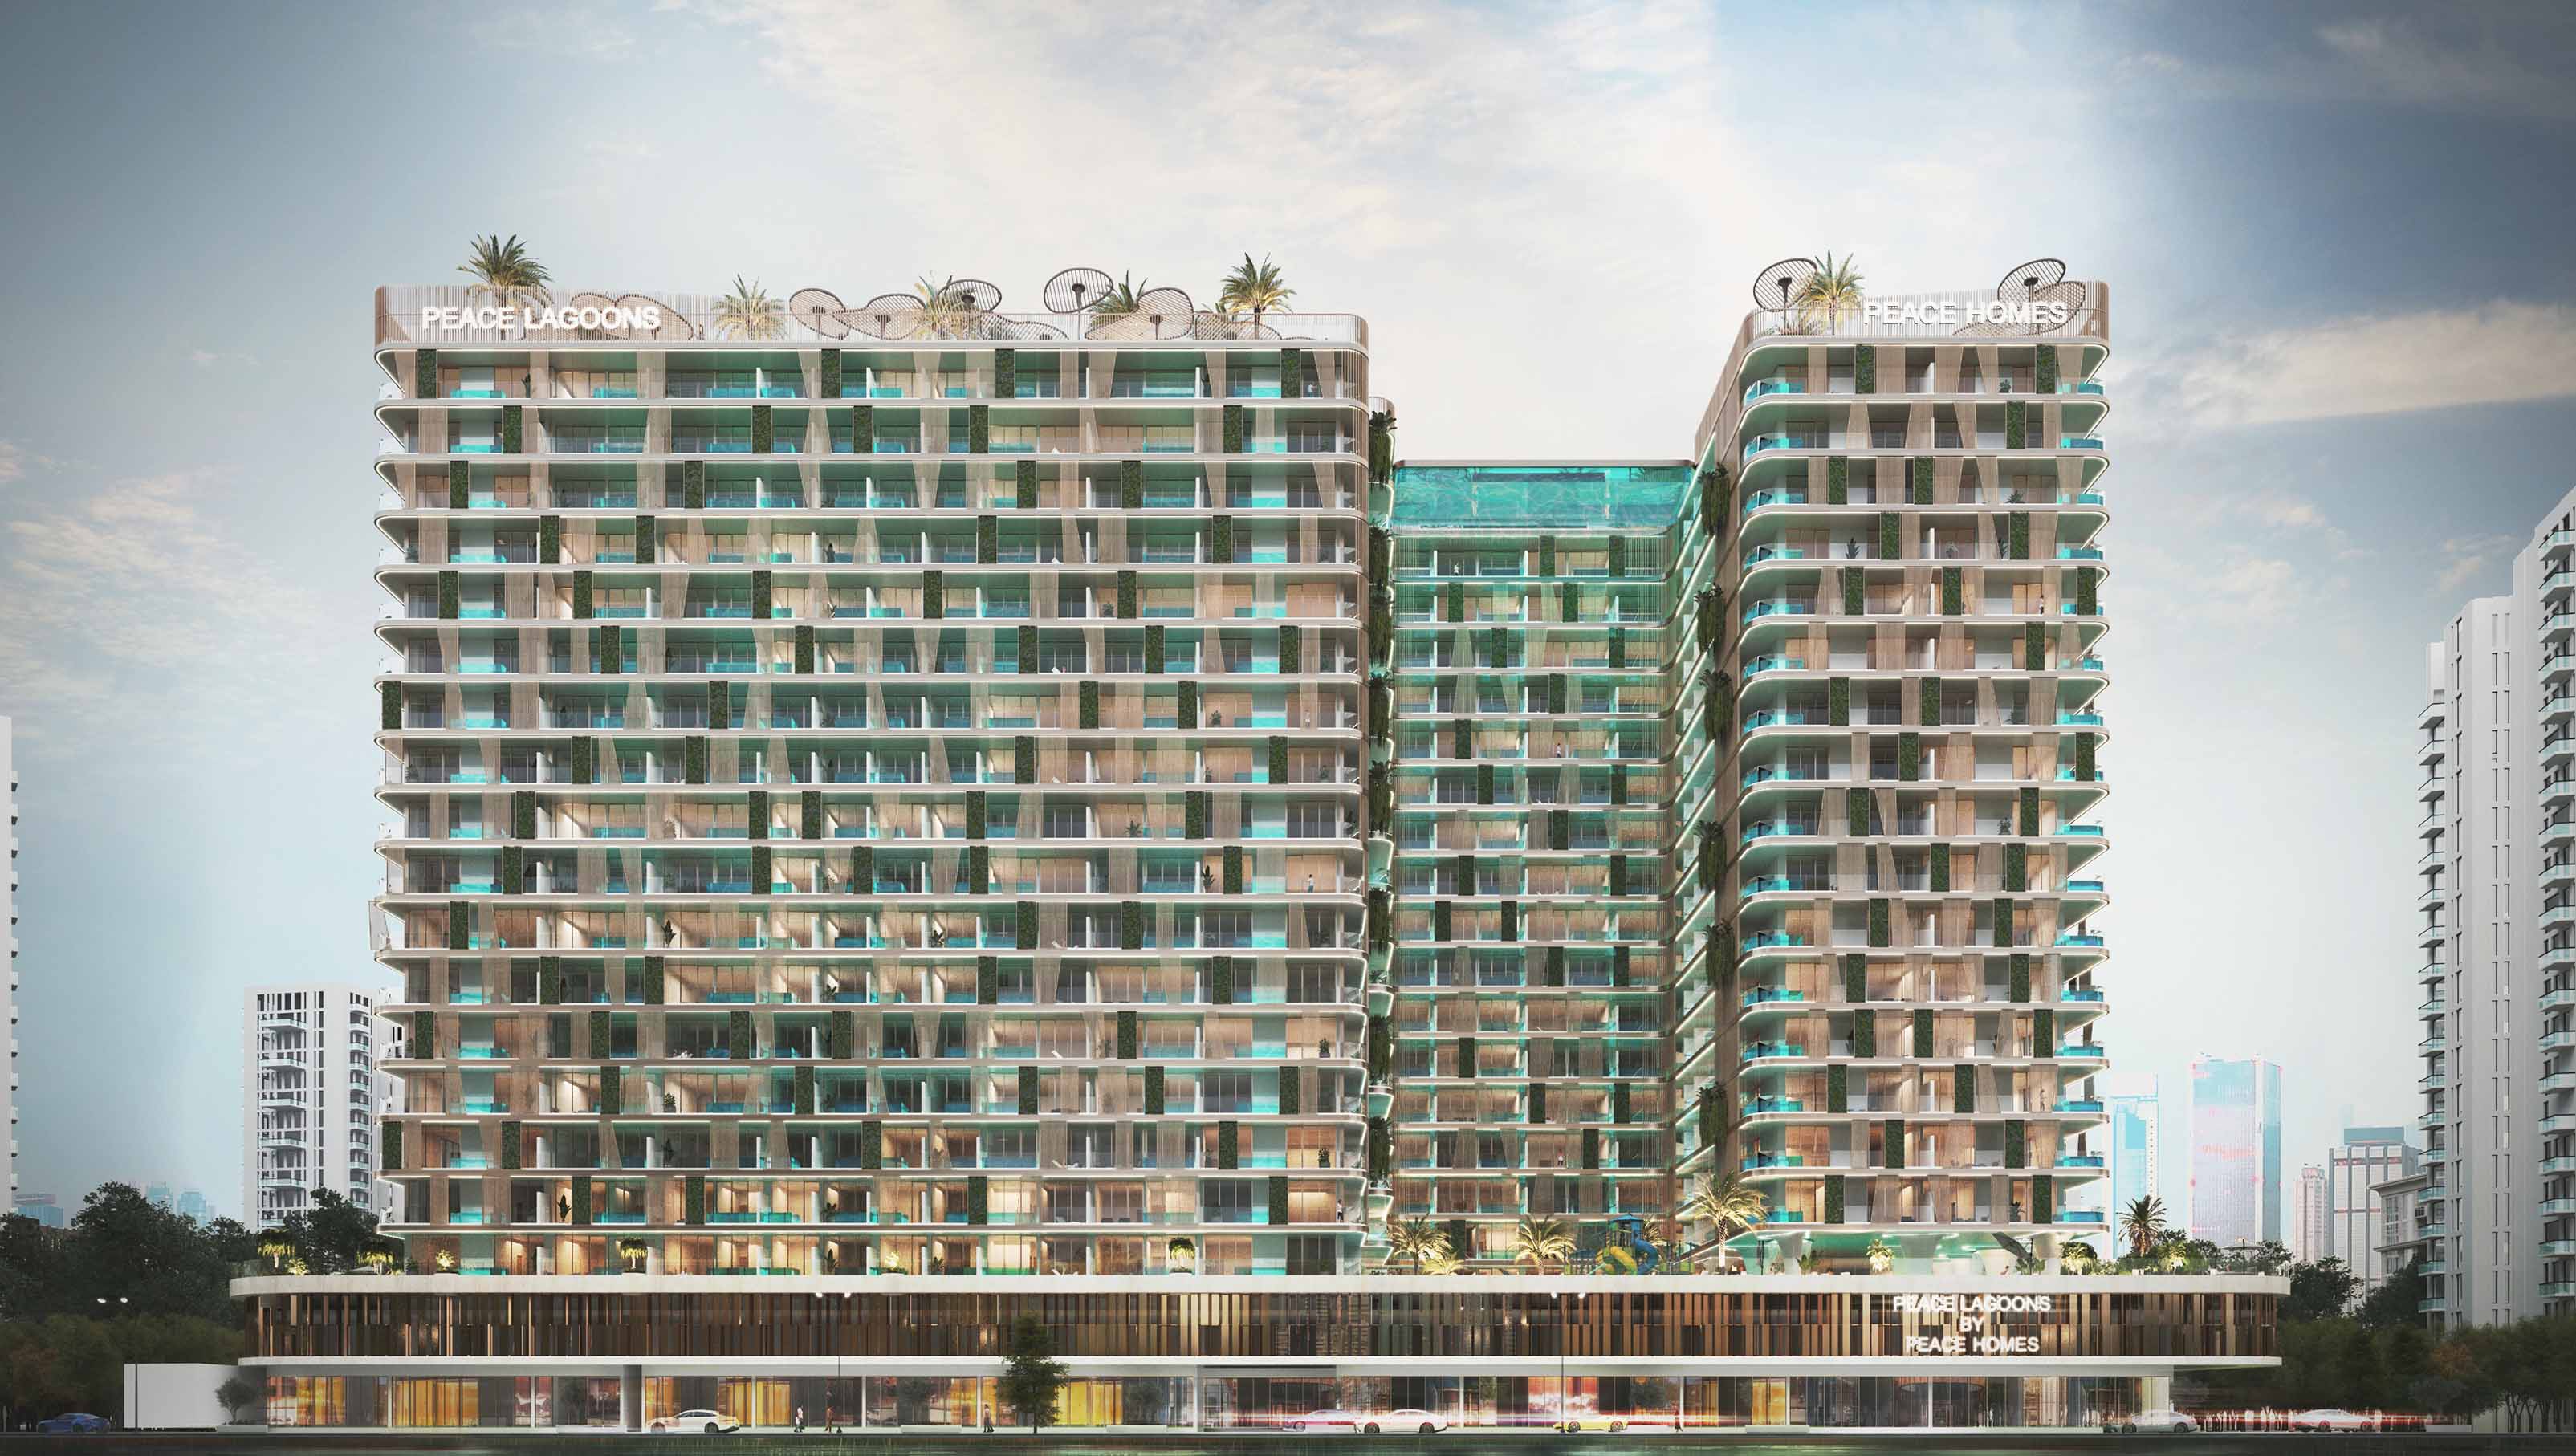 PEACE LAGOONS · Dubailand
Peace Home · Dubailand
DISTRESS DEAL: 1-BR IN PEACE LAGOONS
- Unit
- 1-BR
- Size
- 814 sq.ft
- Developer
- Peace Home
- Handover
- Q1 2029
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
Available when we last checked on 17 September 2026. The asking price shown is the one published when the listing was added on 21 May 2026, 119 days before that check, and it is not re-checked against the market automatically. A listing this old should be treated as indicative — confirm with us that it is still available and still at this price before you act on it.
On this page
Quick navigation
The numbers
Payment breakdown
- Payment to sellerAED 255,000
- DLD Transfer fee (4% of OP + 40 AED)AED 40,040
- DLD Registration Trustee fee + 5% VATAED 5,250
- Buyer's agent commission 2% + 5% VATAED 17,850
- Total on transferAED 318,140
- 30% after 6 monthsAED 255,000
- 40% after 12 monthsAED 340,000
- Total remaining payment planAED 595,000
Ask us to walk through this schedule, or to confirm the current balance with the developer before terms are agreed.
Ask about these termsLayout
Floor plan
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
Peace Lagoons is located in the Dubai Land Residence Complex, specifically in Wadi Al Safa 5. This area is part of the wider Dubai Land master development, which has seen steady infrastructure growth and increasing residential density over recent years. The location offers practical access to key Dubai arterial roads, including Sheikh Mohammed Bin Zayed Road and Al Ain Road, supporting connectivity to Business Bay, Downtown Dubai, and the wider city. Public transport options are still developing, so private car use and ride-hailing services remain the main modes of transport for residents. The area is positioned to benefit from ongoing infrastructure improvements, with new retail, education, and healthcare facilities gradually coming online. For investors, the location’s value is in its balance between affordability and access, appealing to tenants and buyers seeking newer stock without the pricing of prime central districts.
AMENITIES & SURROUNDING
Peace Lagoons is an 18-storey residential building under development by Peace Homes Development. The project is designed to offer a strong amenity profile, including a gymnasium, children’s play area, outdoor cinema, private pools for each apartment, sun loungers, a volleyball court, and yoga and meditation areas. The lagoon pool is a central feature, partially covered by first-floor balconies and enhanced with artificial rain showers. Apartments are finished with Italian ceramics, and the development includes four basement levels for parking. The immediate surroundings are evolving, with new retail and service outlets opening as the area matures. The building’s amenity deck and lagoon concept are positioned to attract residents seeking a lifestyle-oriented environment, while the broader Dubai Land Residence Complex is supported by a growing mix of residential, retail, and leisure infrastructure.
MARKET
At AED 1,044 per sq.ft, this unit is priced below the most recent Peace Lagoons transactions for studios and two-bedroom units, which have ranged from AED 1,316 to AED 1,952 per sq.ft according to Dubai Land Department records. The discount to original price and the staged payment plan create a lower entry basis compared to current developer and secondary market listings. As an off-plan asset, the main risk is construction and handover timing, with completion scheduled for Q1 2029. The Dubai Land Residence Complex attracts a mix of end-users and investors, with rental demand driven by affordability and new-build appeal. Liquidity is supported by the area’s improving infrastructure and the project’s amenity offering, but investors should be aware that off-plan resale markets can be more volatile, and yields may be sensitive to handover timing and market absorption. The buyer profile is likely to include both rental investors and end-users seeking a new, amenity-rich environment at a lower price point than central Dubai.
CONCLUSION
This distress deal in Peace Lagoons offers an 18.3% discount to the original price, a payment plan that reduces upfront capital requirements, and exposure to a new-build project in a developing residential corridor. The unit’s high-floor position, lagoon view, and semi-furnished status add to its rental and resale appeal. The main risks are linked to off-plan handover and the pace of area infrastructure development, but the entry price per square foot is competitive against recent transactions in the building. For investors seeking a balance between price, payment flexibility, and amenity-led positioning, this deal provides a practical route into Dubai’s evolving residential market. The case is strongest for buyers comfortable with off-plan risk and looking for a mid-term hold in a project with tangible lifestyle infrastructure and improving connectivity.
Location
PEACE LAGOONS — Dubailand, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 1-BR IN PEACE LAGOONS behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
The date this listing was added to our records. The asking price below is the one published then, and was still 119 days old when we last checked this listing on 17 September 2026. It is not re-checked against the market automatically, so confirm it with us before relying on it.
As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.
The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.
As stated on this listing. Rent cannot start before handover, so on an incomplete unit the early years of the schedule below are holding cost only.
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 901,850 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 832,150 | AED 832,150 |
| Years 1–5 | AED 0 | AED 832,150 | AED 832,150 |
| Less the year-0 outflow of AED 901,850 → total profit | −AED 69,700 | ||
Exit at year 5: illustrative sale price AED 850,000 less selling costs AED 17,850 = AED 832,150 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 658k | — | — | — |
| −3% p.a. | AED 730k | — | — | — |
| 0% p.a.your figure | AED 850k | — | — | — |
| 3% p.a. | AED 985k | — | — | — |
| 5% p.a. | AED 1.08M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Emaar Beachfront
DISTRESS DEAL: 1-BR IN DAMAC BAY - TOWER C
- Price / sq.ft
- AED 3,378
- Developer
- Damac
- Handover
- Q4 2027
Rashid Yachts and Marina
DISTRESS DEAL: 1-BR IN OCEAN POINT - TOWER 2
- Price / sq.ft
- AED 1,908
- Developer
- Emaar
Emaar Beachfront
DISTRESS DEAL: 1-BR IN SEAPOINT - TOWER 2
- Size
- 764 sq.ft
- Price / sq.ft
- AED 3,442
- Developer
- Emaar
- Handover
- Q2 2028
Bluewaters Island
DISTRESS DEAL: 2-BR + Maid's IN BLUEWATERS BAY - BUILDING 1
- Size
- 1,670 sq.ft
- Price / sq.ft
- AED 3,145
- Developer
- Meraas
- Handover
- Q3 2027
Sobha Hartland II
DISTRESS DEAL: 2-BR IN SKYSCAPE ALTIUS
- Size
- 1,268 sq.ft
- Price / sq.ft
- AED 2,129
- Developer
- Sobha
- Handover
- Q4 2028
Emaar Beachfront
DISTRESS DEAL: BULK DEAL - 9 APARTMENTS IN BAYVIEW - TOWER 1
- Size
- 10,041 sq.ft
- Price / sq.ft
- AED 4,681
- Developer
- Emaar
- Handover
- Q2 2027
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.