Palm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm JumeirahAED 3,627/sqftDubai Maritime CityAED 3,134/sqftDowntown DubaiAED 2,917/sqftDubai IslandsAED 2,754/sqftDubai Creek HarbourAED 2,567/sqftBusiness BayAED 2,559/sqftDubai MarinaAED 2,495/sqftDubai Hills EstateAED 2,441/sqftJumeirah Lakes TowersAED 2,283/sqftMohammed Bin Rashid CityAED 2,098/sqftAl JaddafAED 2,049/sqftJumeirah Village TriangleAED 1,662/sqftDubai SouthAED 1,648/sqftArjanAED 1,594/sqftJumeirah Village CircleAED 1,503/sqftDubai Sports CityAED 1,330/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO SEP 2026
★ Featured OpportunityOff-planBusiness Bay

Binghatti Skyrise

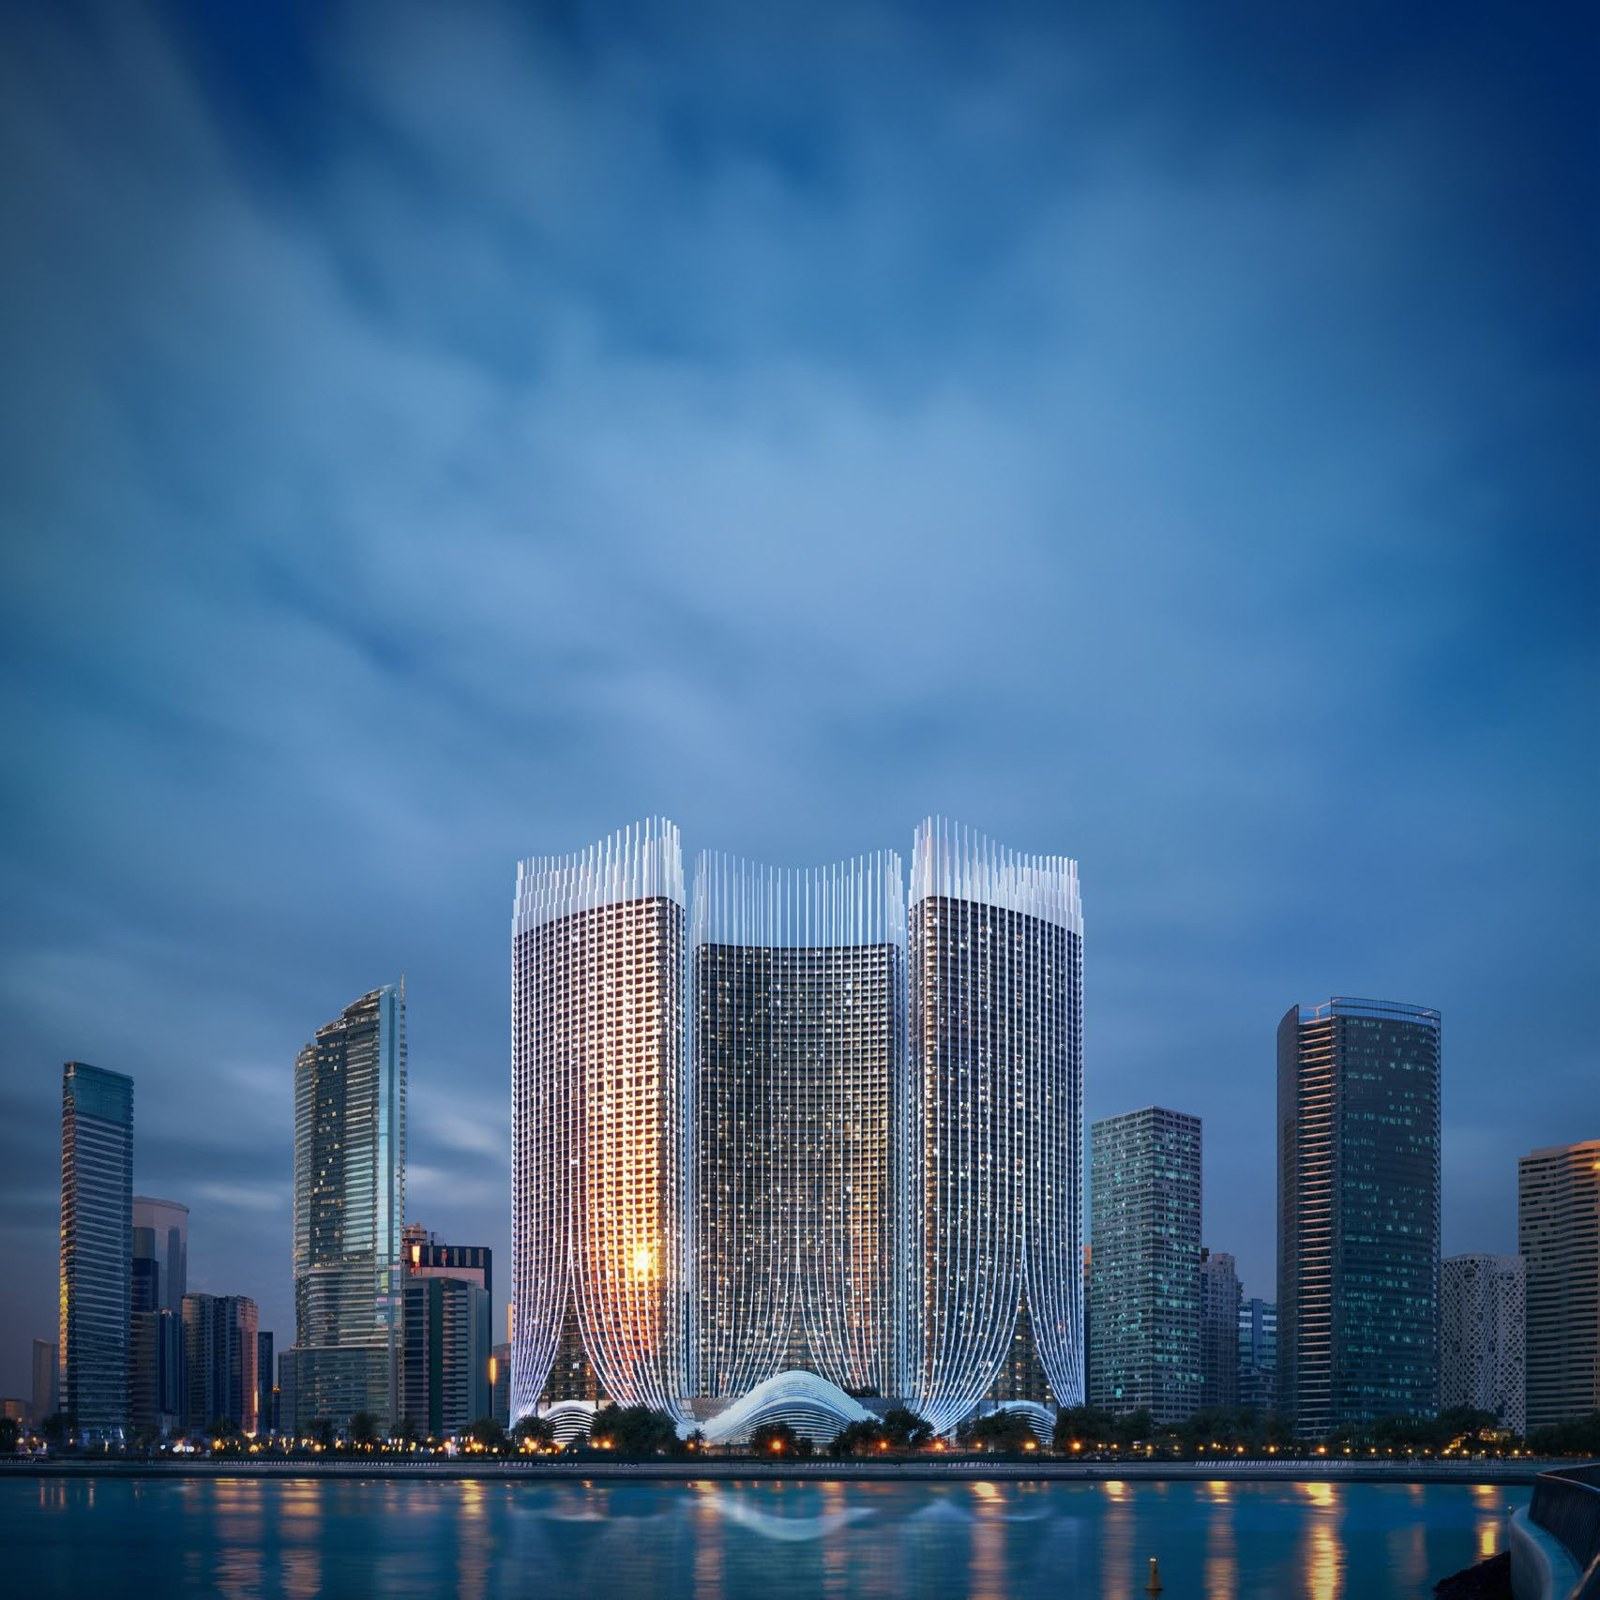
Binghatti Skyrise at Business Bay: studio to 3-bedroom apartments across a 3,302-home, three-tower development in Business Bay. Off-plan; pricing on request.

DeveloperBinghatti
Entry priceNot publishedBinghatti has not released a starting price
Median registered / sqftAED 2,752Median of 1,382 DLD sales, Apr 2025 – Sep 2026
HandoverTo be confirmedNo completion date published for this project
CommunityBusiness Bay

Overview

Project brief

A THREE-TOWER RESIDENTIAL DEVELOPMENT IN THE CENTRE OF BUSINESS BAY

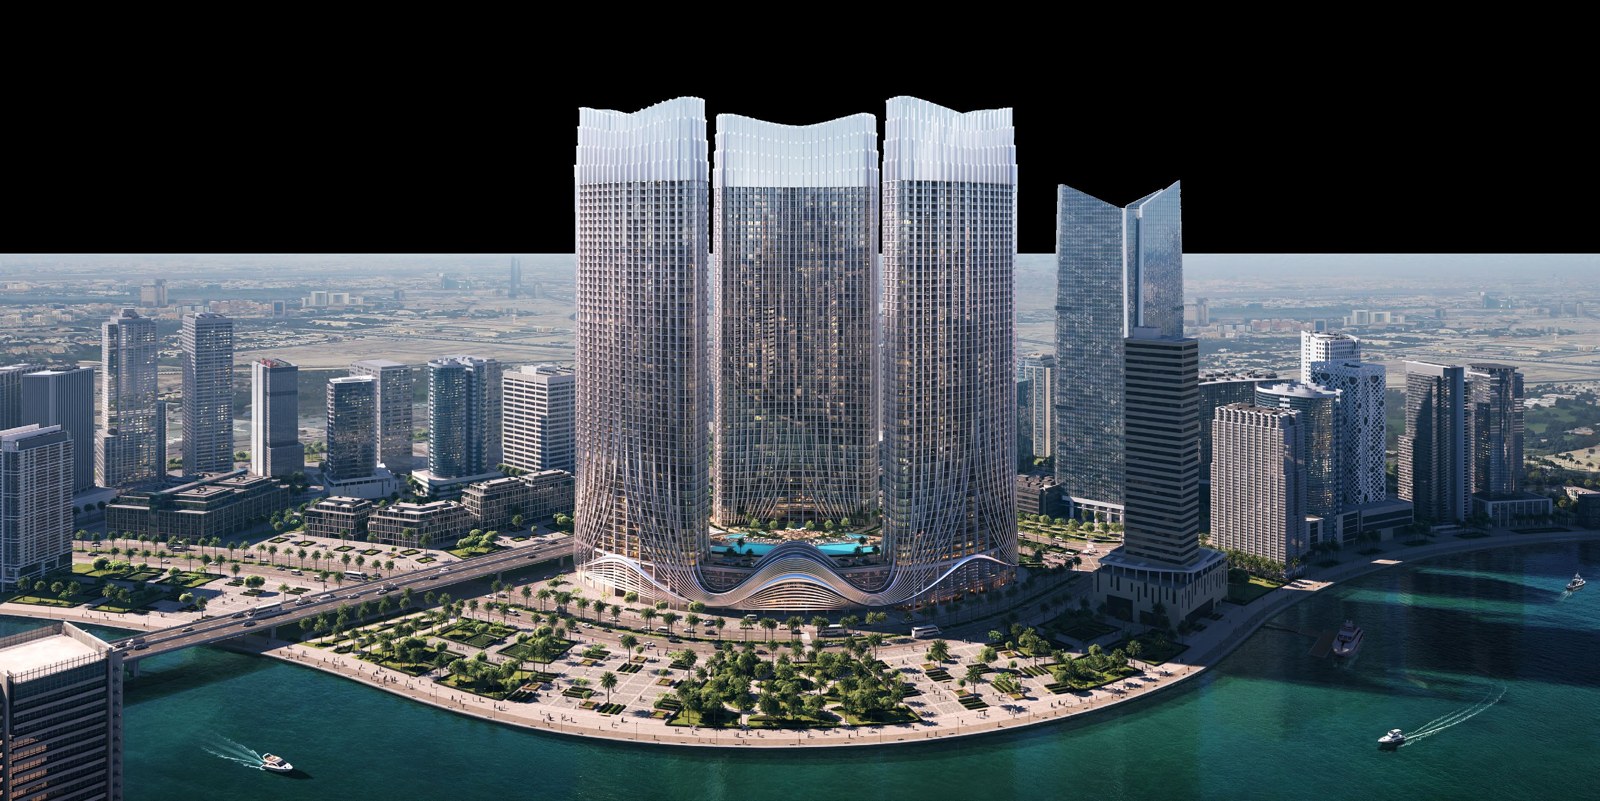
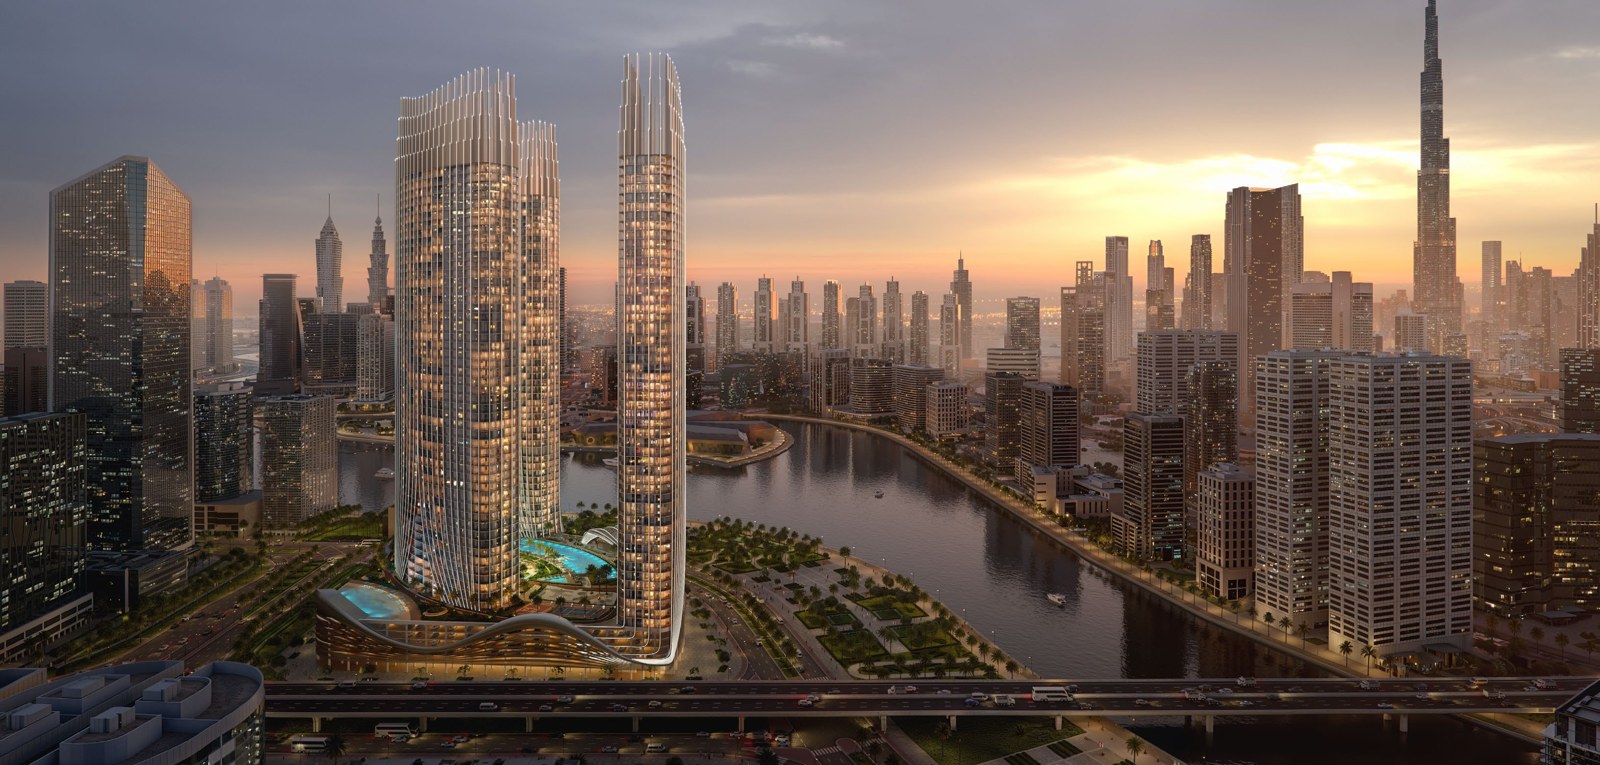
Binghatti Skyrise is a three-tower residential development by Binghatti in the centre of Business Bay, with a sleek, curvilinear silhouette set against the Dubai skyline. Comprising studios, one and two-bedroom apartments and a limited collection of expansive three-bedroom residences, it reflects Binghatti's sculptural design language on a large, master-planned scale.

The development sits on a plot of roughly 26,933.81 square metres (289,913.12 square feet) and rises over four basement levels, a ground floor, five podium levels and 48 residential floors, above two mechanical rooms and a roof, across three towers. It holds 3,302 residential units — 2,256 studios, 996 one-bedroom, 24 two-bedroom and 26 three-bedroom apartments — together with 31 ground-floor shops. Homes are finished in Binghatti's signature palette, including wood veneer, and served by a curated set of amenities.

At the time of this brief, Binghatti had not published a starting price, payment plan or handover date for Skyrise; those are confirmed on request and are noted below as pending.
Key information

Price, areas, mix & the masterplan

Total units
3,302 residential + 31 retail
Starting price
On request
Payment plan
On request
Expected completion
To be confirmed
Community
Business Bay, Dubai
Type
Studio, 1, 2 & 3-Bedroom Apartments + Ground-Floor Retail (3 towers)
Plot area
26,933.81 sq m (289,913.12 sq ft)

Based on the project brochure; pricing, payment plan and handover subject to confirmation on release.

UNIT MIX

3,333 units listed

Share of the 3,333 units listed in Binghatti Skyrise’s published unit mix. Percentages are calculated from the counts in the table below and are not a statement about availability.

  • Studio apartment2,25668%
  • 1-Bedroom apartment99630%
  • 2-Bedroom apartment24<1%
  • 3-Bedroom apartment26<1%
  • Shops (ground floor)31<1%

Unit counts per the Binghatti Skyrise brochure. Sizes and starting prices to be confirmed on release.

THE INVESTMENT CASE

Binghatti Skyrise is an off-plan brief: the angle below is qualitative. Where the live Dubai Land Department transaction feed for Business Bay is available, current pricing and PSF trends will be shown alongside — those figures are the basis for any comparison, not the estimates below.

LOCATION: BUSINESS BAY, ON THE DUBAI WATER CANAL BESIDE DOWNTOWN DUBAI

Skyrise sits in the centre of Business Bay, a central Dubai district on the Dubai Water Canal beside Downtown Dubai. The brochure cites the Dubai Canal around 2 minutes away; Downtown Dubai, the Dubai Mall, Burj Khalifa and Dubai Opera around 5 minutes; the Dubai International Financial Centre and Dubai Design District around 7 minutes; Coca-Cola Arena around 9 minutes; and Ras Al Khor Wildlife Sanctuary around 10 minutes. Business Bay adjoins the Downtown Dubai and Burj Khalifa district, with Sheikh Zayed Road and Al Khail Road serving the wider area. The position combines a central canal-side address with genuine connectivity to the city's commercial core.

APPLICABLE STRATEGIES

  • Pre-handover resale — a large off-plan launch in a central Business Bay location; where a construction-linked plan applies, a buyer commits limited capital ahead of completion, with an exit route before handover. Any premium depends on market conditions at the time and should be checked against live DLD data.
  • Buy-and-hold for rental / short-let — a very high proportion of studios and one-bedroom homes, minutes from Downtown and DIFC, suits both long-let and holiday-let demand; yields to be confirmed against current rental evidence.
  • Owner-occupation — a centrally located home in a design-led development with resort-style amenities including a pool deck, indoor gym, jogging lane, artificial beach, paddle and tennis courts and a skate park.

RISKS & WATCHPOINTS

  • Off-plan completion risk — the development is under construction; timelines can move, and returns depend on the market at handover, not today's.
  • Pricing not yet confirmed — starting price, payment plan and handover date were not published in the brochure; the entry point should be assessed against live Business Bay PSF once confirmed.
  • Unit-mix concentration and scale — studios and one-bedroom apartments make up the large majority of a 3,302-unit, three-tower development, which can mean a deep competing supply pool on resale and rental within the same scheme.
  • Service charges — design-led, amenity-rich buildings typically carry higher service charges, which affect net yield.

PAYMENT PLAN

Binghatti had not published a payment plan for Skyrise at the time of this brief. The current plan and starting price are confirmed on request.

Location

AREA, COMMUNITY & CONNECTIVITY

DLD register

Binghatti Skyrise is in the Business Bay area. The Dubai Land Department register records the nearest metro station, retail centre and landmark against the project — those are the points shown below.

Connectivity schematic
AREA · BUSINESS BAYPROJECTBINGHATTI SKYRISENEAREST METROBusiness Bay MetroStationNEAREST MALLDubai MallNEAREST LANDMARKDowntown Dubai

Diagram, not a map. Node positions are for orientation only — they are not to scale, not to bearing, and imply no distance or travel time.

Location record
Area
Business Bay
Nearest metro
Business Bay Metro Station
Nearest mall
Dubai Mall
Nearest landmark
Downtown Dubai

Area and community are from our own project record, not the DLD register. Each connectivity point is the nearest of its kind recorded against this project in the Dubai Land Department register. The register publishes the name only — no distances or journey times — so none are stated here. We can confirm them in writing on request.

Connectivity points: Dubai Land Department project register. Area and community: our own project record. Neither is a survey, and neither is a substitute for your own site visit.

Location

Binghatti SkyriseBusiness Bay, Business Bay

Get Directions
Investment case

HOW THIS PRICES AGAINST THE MARKET

Registered evidence · as at 11 Sep 2026

Every figure below is derived from arm’s-length sales registered with the Dubai Land Department — completed transactions, not asking prices. The register was read on 15 Sep 2026. The most recent qualifying sale at Binghatti Skyrise is dated 11 Sep 2026. Medians are of AED per square foot across all unit types unless stated otherwise.

Median AED / sqft — Binghatti Skyrise against its benchmarks
Binghatti Skyrisen = 1,382 registered sales since Apr 2025
2,752AED / sqft
this project
Business BayArea median, off-plan properties · n = 4,613 sales
2,743AED / sqft
+0.3%in line

Premium and discount compare Binghatti Skyrise’s median AED/sqft with each benchmark median from the same extract; n is the number of registered sales behind each median. A premium is neither good nor bad in itself — it reflects specification, unit mix, floor level and how recently the sales were registered. Bar length is proportional to the median shown.

Registered price trend
+9.2%
median AED/sqft, 2025 Q2 → 2026 Q1 (9 months)
AED 2,382 → AED 2,602 per sqft.

A change between two period medians, not a compounded annual rate and not a forecast. Period medians move with the mix of units sold as well as with price, so read this alongside the sample sizes in each period.

Off-plan vs resale
Off-plan
2,752
AED/sqft median · n = 1,382
Resale
No registrations · n not reported

Only off-plan sales are on the register for this project as at 11 Sep 2026, so no off-plan-to-resale comparison can be evidenced here.

What to watch
  • Wide price dispersion. Registered prices run from AED 856 to AED 3,671 per sqft — a spread of 102% of the median, as at 11 Sep 2026. We have not measured what drives that range for this project; floor, view, layout and unit size are the usual causes and are worth checking unit by unit. The median is not a price guide for any specific unit.
  • Concentrated unit mix. 69% of registered sales (959 of 1,382) are Studio units, so the overall median largely describes that layout. Evidence for the other layouts is thinner and should be read at the bedroom level.
  • Volatile quarterly medians. Quarterly medians have ranged between AED 2,327 and AED 3,057 per sqft since 2025 Q2 — a band of 31%. Read the series as a whole; a single quarter's print moves with unit mix as much as with price.
  • A median is not a valuation. Every figure here is a median of registered AED per sqft across mixed floors, sizes and payment terms, up to 11 Sep 2026. The price of a particular unit can sit well outside it, and none of this constitutes a valuation or investment advice.
  • Historic evidence, not a projection. These are transactions already completed and registered up to 11 Sep 2026. They describe what buyers paid, not what prices, rents or resale liquidity will do next.

Source: Dubai Land Department (DLD) transaction register, via Mitchell's DLD pipeline. Register read 15 Sep 2026; most recent qualifying sale 11 Sep 2026. Only arm’s-length sales are counted. This section is a summary of registered transaction evidence — it is not a valuation, a forecast, or investment advice.

Illustrative model

Scenario modeller

Set your own assumptions and see how Binghatti Skyrise behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.

Purchase

Seeded from this page — change it to your figure.

Drives the service charge only.

Rent and service charge both start here.

Holding & income

Seeded from tenancy evidence; edit freely.

0% holds rent flat. It may be negative.

Your figure — we publish none. A month vacant plus re-letting time is roughly 8%, if that fits your building.

Your figure — we publish none. Letting fees and routine repairs.

Your figure — we publish none. Look your building up on Mollak — rates run AED 3 to AED 30+.

Acquisition costs

4% is the Dubai standard.

Buyer-side. 5% VAT added.

Your figure — we publish none. The trustee tariff is tiered and the admin lines vary by office; ask your trustee office for the total, and add your NOC and any legal quote.

Exit

1 to 40 years.

0% by default: we publish no price forecasts.

5% VAT added automatically.

Gross yieldGross annual rent divided by the purchase price. Before any costs.
7.7%
Annual rent ÷ purchase price
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price.
Set service charge, maintenance & management, vacancy allowance above
ROI (unlevered)Return on investment: total profit divided by total cash invested (price plus all acquisition costs). No debt in this mode.
Set service charge, maintenance & management, vacancy allowance above
IRRInternal rate of return: the discount rate at which the cash-flow schedule below has a net present value of zero.
Set service charge, maintenance & management, vacancy allowance above
Cash out, and cash back over 5 years
Cash out at t0AED 1,330,228
Cash back, years 1–5

Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.

Cash required at completion
Purchase priceAED 1,253,749
DLD transfer fee (4%)AED 50,150
Agency fee (2%)AED 25,075
VAT on agency fee (5%)AED 1,254
Conveyancing, trustee & adminAED 0
Total cash investedAED 1,330,228

This is the ROI and IRR denominator: the price plus every cost of getting the keys, not the price alone.

Annual operating position
Gross annual rentAED 96,000
Vacancy allowance (not set)
Maintenance & management (not set)
Service charge (462 sq ft at AED — not set)
Net operating income

Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.

Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete — see note)
YearNet operating incomeSale proceeds, netNet cash flow
0 · today−AED 1,330,228
1AED 96,000AED 96,000
2AED 96,000AED 96,000
3AED 96,000AED 96,000
4AED 96,000AED 96,000
5AED 96,000AED 1,227,420AED 1,323,420
Years 1–5AED 480,000AED 1,227,420AED 1,707,420
Less the year-0 outflow of AED 1,330,228 → total profitAED 377,193

Exit at year 5: illustrative sale price AED 1,253,749 less selling costs AED 26,329 = AED 1,227,420 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.

Sensitivity — the same purchase at −5% to +5% exit growth
Exit growthExit priceTotal profitROIIRR
−5% p.a.AED 970k
−3% p.a.AED 1.08M
0% p.a.your figureAED 1.25M
3% p.a.AED 1.45M
5% p.a.AED 1.60M

Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. Every column past exit price is shown as “—” until service charge, maintenance & management, vacancy allowance are set above — the schedule these figures come from assumes zero for anything unset, which is not a result we print.

How each figure is calculated
Handover
The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
Gross yield
Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
Net yield
(Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
Rent growth
Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
ROI
Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
ROE
Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
Cash-on-cash return
Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
IRR
The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.

Email my results

We’ll send this scenario — your assumptions and the figures they produce — to your inbox.

Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.

Context, not a forecast: the registered median AED/sqft moved 9.2% between 2025 Q2 and 2026 Q1 (9 months). Historic movement is not a guide to future prices.

An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.

Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.

Market evidence

WHAT BUYERS ARE ACTUALLY PAYING

DLD registerAs at 11 Sep 2026

Independent, registered evidence — not asking prices. Every figure below is drawn from arm’s-length sales at Binghatti Skyrise recorded by the Dubai Land Department, taken from a single extract pulled on 15 Sep 2026 and covering sales registered up to 11 Sep 2026: 1,382 in all, the earliest dated 28 Apr 2025.

Median price / sqft
AED 2,752
Registered DLD sales
Registered sales
1,382
Apr 2025 – Sep 2026
PSF range
856 – 3,671
Low to high, AED/sqft
Median sale price
AED 1.49M
All unit types
Median AED/sqft by month
17 months · sale counts omitted at this scale
3,5002,000AED/sqft2,408Apr 25Jul 25Oct 25Jan 26Apr 262,125Sep 26
By bedroom count
BedsSalesMedian sizeMedian PSFMedian price
Studio959462 sqft2,881AED 1.25M
1 BR390831 sqft2,715AED 2.31M
2 BR121,324 sqft2,887AED 3.88M
3 BR211,989 sqft2,644AED 5.45M
Off-plan first sale from the developer
2,752 AED/sqft
Median of 1,382 registered sales
100% of these sales
Most recent registered sales
12 most recent of 1,382 on record, to 11 Sep 2026
DateBedsSize (sqft)Price (AED)AED/sqft
11 Sep 20261 BR8311,905,0002,293
10 Sep 20261 BR8311,625,0001,956
9 Sep 2026Studio434371,500856
1 Sep 20263 BR1,7665,294,9992,998
25 Aug 2026Studio4631,030,0002,226
24 Aug 2026Studio4651,100,0002,368
19 Aug 20261 BR1,0222,527,1992,473
18 Aug 2026Studio4651,050,0002,260
5 Aug 2026Studio4341,025,0002,362
31 Jul 20263 BR2,2885,734,1492,506
27 Jul 20261 BR9662,774,9992,871
27 Jul 20261 BR8292,399,9992,894

Individual arm’s-length sales as registered with the Dubai Land Department. Sizes are as recorded on the title deed; price is the registered consideration, exclusive of the 4% transfer fee and any agency or developer charges.

Registered DLD transactions for this project. Only arm's-length 'Sales' of homes are counted; intra-family 'Gifts' transfers, zero-price rows, and land, building and villa transfers are excluded. Offices, shops, showrooms and other non-residential units in the same building are also excluded — they price far above the apartments above them and would otherwise set the top of the price-per-square-foot range. Where the register holds the same sale twice, the duplicate is removed before anything is counted. A project is published only once it has at least 30 qualifying sales. Period and bedroom figures are medians of AED per square foot, which are robust to the outliers that skew a mean on a thin sample. Benchmarks are medians over the trailing 12 months for the same area and registration type. This is a dated extract, not a live query: it changes only when the extract is regenerated with `npm run data:dld`. Source: Dubai Land Department (DLD) transaction register, via Mitchell's DLD pipeline. Data as at 11 Sep 2026; extract generated 15 Sep 2026. Past registered prices are evidence of what has been paid, not a forecast of future value.

The developer

Binghatti

An Emirati developer known for a sculptural design language and branded residences.

Binghatti is a privately held Emirati developer founded in 2008, with roots as a contractor before it moved into full-scale development. It is vertically integrated across design, development, construction and delivery — unusual in the Dubai market, where those functions are more often split between separate firms — and is most recognisable for a distinctive, sculptural facade language that repeats across its portfolio.

It is also the developer behind several of Dubai’s branded-residence collaborations, including projects with BUGATTI, Mercedes-Benz and Jacob & Co. Its schemes concentrate in central, well-connected districts — Jumeirah Village Circle, Business Bay, Al Jaddaf and Dubai Science Park among the communities covered on this site — typically at apartment sizes aimed at the investor and first-time-buyer end of the market rather than the luxury villa segment.

Projects delivered
50+
Of a portfolio Binghatti states exceeds 100 projects, with a gross value of more than AED 100 billion — Binghatti’s own investor-relations overview, binghatti.com, read 8 September 2026.
Pipeline
~30m sq ft
Sellable area under development, as stated by Binghatti’s investor-relations overview, binghatti.com, read 8 September 2026.

Both figures are Binghatti’s own published statements about its business, carried here as the developer reports them. They are not an independent measurement, an audit, or a forecast, and they describe Binghatti as a whole rather than this or any other individual project.

Got questions?

Get Answers!
Method & questions

HOW TO READ THIS PAGE

Figures as at 11 Sep 2026

Two different things sit on this page: transaction evidence taken from the Dubai Land Department’s public register, and the mechanics of buying in Dubai. The four notes below explain how the figures were built and what they can fairly be used for.

  1. Registered, not askedEvery Dubai Land Department figure on this page comes from a sale that completed and was entered on the public register. Asking prices, portal listings and developer price lists are excluded: they record what someone hoped for, not what was paid.
  2. Medians, not averagesProject samples are often thin, and a single penthouse or one bulk-discounted floor will pull an average a long way off. The median — the middle transaction — describes the typical unit far more reliably at these sample sizes. The count behind each figure is always shown so you can judge how much weight it deserves.
  3. Sales only“Sales” means arm’s-length sales. Intra-family and other “Gift” transfers are excluded, as are rows registered at zero or nominal consideration, because neither is evidence of a market price.
  4. A dated snapshotThese are a snapshot, stated as at 11 Sep 2026, taken from one extract of the register rather than queried live. A figure for this project quoted elsewhere, or taken from a different extract, may not match what you see here.

Common questions

What does buying off-plan at Binghatti Skyrise involve?

Off-plan means contracting with the developer before the building is finished. In outline: you reserve the unit, sign the developer’s Sale and Purchase Agreement (SPA), and pay in instalments tied to construction milestones rather than in a single sum at the start.

Buyer payments on an off-plan sale in Dubai are made into a project escrow account regulated under Dubai Law No. 8 of 2007, and are released to the developer against verified construction progress. The developer registers the sale with the Dubai Land Department. The contract is between you and Binghatti; we act as broker, not as principal.

What is the 4% DLD transfer fee, and who pays it?

The Dubai Land Department charges a property registration (transfer) fee of 4% of the price recorded on the contract, plus a fixed administrative charge. That is the rate in force as at July 2026. The statutory position splits the fee between buyer and seller; established market practice in Dubai is that the buyer pays the whole 4%.

Developers sometimes offer to absorb part or all of it on off-plan sales. Treat that as real only where it is written into the sale documents, not where it appears in marketing. Budget separately for the registration trustee charge, the Oqood registration fee on off-plan units, and — if you are borrowing — mortgage registration at 0.25% of the loan amount.

What is an Oqood registration, and is it the same as a title deed?

No. Oqood is the Dubai Land Department’s registration system for property that is not yet complete. When you buy off-plan, the developer lodges the SPA through Oqood, your interest is recorded on the interim property register, and you receive an initial registration certificate.

The title deed is a separate and later document, issued once the project is complete and the unit is formally transferred into your name. An off-plan purchase that is never registered leaves you off that interim register, so ask for evidence of Oqood registration once your first payment has cleared.

Can a non-UAE buyer own a unit outright?

In Dubai’s designated freehold areas, yes. Regulation No. 3 of 2006 sets out the areas in which non-UAE nationals may hold freehold title or a long lease; outside those areas ownership is restricted to UAE and GCC nationals. Ownership does not depend on holding UAE residency, and no local partner is required.

Tenure attaches to the plot rather than to a development’s marketing, so confirm what is recorded against the specific unit — freehold or leasehold, and the remaining term if leasehold — before you sign.

What happens at handover?

Once the building is complete and the completion certificate issued, you are called for handover: you inspect the unit (the snagging inspection), the developer addresses the defects listed, you settle the final instalment and any outstanding fees, and the unit is transferred into your name with a title deed issued.

Annual service charges begin at handover. They are levied per square foot at a rate approved by the regulator, so they are a recurring cost rather than a one-off. If you intend to let the unit, allow for the interval between handover and the first tenancy — a vacant unit earns nothing, and gross yield is annual rent measured against the purchase price, before those costs are taken off.

Where do the Dubai Land Department figures on this page come from?

They are drawn from the Dubai Land Department’s public transaction register — sales actually registered against Binghatti Skyrise, rather than asking prices, portal listings or developer price lists. The set shown here is stated as at 11 Sep 2026. They are a dated extract of the register, not a live query: the extract date is printed with the figures, and everything on this page is calculated from that single extract.

The number of sales behind every figure is shown alongside it. A median drawn from a handful of registrations carries far less weight than one drawn from several hundred, and should be read that way.

Who is Mitchell’s Commercial Real Estate, and how are you paid?

Mitchell’s Commercial Real Estate is the trading brand of Stephen James Mitchell, RERA-licensed broker BRN 68593.

On developer off-plan sales the commission is paid by the developer. On resale transactions the brokerage fee is agreed with you in writing before terms are signed. We will confirm how we are paid on any specific transaction before you commit to it.

Please note. The above is general information about how transactions work in Dubai, not legal, tax or financial advice, and it is not a recommendation to buy. Fee rates, tenure rules and residency requirements change, and your own position may differ. Take your own independent legal and tax advice before you commit to a purchase.

Small print

Sources, provenance & what is not published

Every figure on this page is traceable

SOURCES

  • Binghatti — Binghatti Skyrise project brochure (unit mix, plot, specification, amenities, location).
  • Binghatti — corporate profile: portfolio scale (more than 100 projects, valued at more than AED 100 billion), delivery record (more than 50 projects delivered) and branded-residence collaborations, as stated on Binghatti's own investor-relations overview, https://www.binghatti.com/en/investors-relations (accessed 2026-09-08), and repeated in Binghatti's Q1 2026 financial-results release of 11 May 2026, https://www.binghatti.com/en/pr/binghatti-q1-2026-financial-results. Figures are Binghatti's own.
  • Verified 2026-09-08 against Binghatti’s own investor-relations overview (https://www.binghatti.com/en/investors-relations, live, accessed 2026-09-08): “Binghatti’s portfolio exceeds 100 projects with a gross value of more than AED 100 billion, including over 50 delivered developments and maintains a pipeline of approximately 30 million square feet of sellable area.” Binghatti’s Q1 2026 financial-results release of 11 May 2026 (https://www.binghatti.com/en/pr/binghatti-q1-2026-financial-results) states the same. The portfolio value on this page was changed from “nearly” to “more than AED 100 billion” on 2026-09-08, following Stephen’s ruling that a developer’s figures track that developer’s latest published wording; “nearly” was Binghatti’s own 25 March 2026 wording (https://www.binghatti.com/en/pr/binghatti-sales-delivery-update-dubai-2026), superseded twice since. The delivered-projects count is unchanged: Binghatti’s H1 2026 financial-results release of 27 July 2026 (https://www.binghatti.com/en/pr/binghatti-h1-2026-financial-results) states no portfolio or delivery total, and the “nearly 60 completed developments” wording carried by wire copies of that release appears on no Binghatti-owned page, so it is not published here.
  • Dubai Land Department transaction register — every registered-sales figure on this page (transaction count, medians, the price-per-square-foot range, the quarterly and monthly trend and the bedroom breakdown), as at 2026-09-01. Arm's-length sales only: intra-family gift transfers, zero-price rows and land, building and villa transfers are excluded, and where the register holds the same sale twice the duplicate is removed before anything is counted. The Business Bay benchmark these figures are compared against is a trailing-12-month median on the same basis. A dated extract, not a live query.

Next step

Register your interest

Tell us your budget and objective and we’ll send the full investor pack — floor plans, payment schedule, unit availability and the underlying comparables. Availability and pricing are confirmed on request and kept current.

Need help?