Palm Jumeirah AED 3,559/sqftDubai Maritime City AED 3,152/sqftDowntown Dubai AED 2,883/sqftDubai Islands AED 2,774/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,500/sqftDubai Marina AED 2,481/sqftDubai Hills Estate AED 2,459/sqftJumeirah Lakes Towers AED 2,321/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,051/sqftJumeirah Village Triangle AED 1,658/sqftDubai South AED 1,652/sqftArjan AED 1,584/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm Jumeirah AED 3,559/sqftDubai Maritime City AED 3,152/sqftDowntown Dubai AED 2,883/sqftDubai Islands AED 2,774/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,500/sqftDubai Marina AED 2,481/sqftDubai Hills Estate AED 2,459/sqftJumeirah Lakes Towers AED 2,321/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,051/sqftJumeirah Village Triangle AED 1,658/sqftDubai South AED 1,652/sqftArjan AED 1,584/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO OCT 2026
Palm Jumeirah, Dubai — area guide

Area guide · Dubai

Palm Jumeirah Investment Guide

When I discuss Palm Jumeirah with investors, the conversation almost always starts the same way — with its global recognition.

I want to
Budget

Answer the two questions and this page reorders itself around them. Nothing is sent until you ask for something.

Sales prices

3,559AED/sqft
Median price, whole register
DLD register — median of 1,149 sales in the twelve months to 25 October 2026. Pools off-plan registrations with sales of completed property, every property type. Across the register 69.1% of those rows are off-plan registrations and 30.9% sales of completed property.
1,500–2,500AED/sqft, 2001
Launch price
Developer launch pricing when the community came to market, from this guide. Historic — not a current valuation.

A building can sit well under the area figure. Tell us which one you have in mind and we will read its own register history back to you.

Rental rates

AED 200,000a year
Median annual rent
Ejari — 7,652 registered contracts in the 24 months to 16 October 2026. the Palm Jumeirah sector.
AED 123.7per sq ft a year
Median rent per sq ft
Same contracts, same window.
~3–7%
Gross yield band
Mitchell’s own range for Palm Jumeirah, from this guide — an assessment, not a register figure.

The register gives one rent figure for the area. What a specific building lets for, and how quickly, is the question worth asking before you buy for income.

Ready buildings with recent sales

Median registered price per bedroom type. Hotel rooms and serviced units are left out where the register marks them.

BuildingUnitMedian priceMedian sq ftAED/sqftSales
MARINA RESIDENCE
The Palm - Jumeirah Co. (L.L.C) · completed 2009 · 96 registered sales
2 bedAED 3.85m1,8582,04764
3 bedAED 7.15m2,7362,58528
4 bedAED 12.84m10,2541,2521
5 bedAED 34.16m13,0952,6082
GOLDEN MILE
Souq Residences FZCO · completed 2009 · 63 registered sales
1 bedAED 2.65m1,3042,00712
2 bedAED 3.8m1,8021,96431
3 bedAED 6.5m3,5831,84212
4 bedAED 11.79m6,8241,6982
PenthouseAED 8.66m4,1942,1116
ROYAL AMWAJ
Seven Tides Limited · completed 2021 · 45 registered sales
StudioAED 1.5m5492,7327
1 bedAED 2.6m1,1582,18321
2 bedAED 4.25m1,8232,33017
THE 8
C Fourteen FZE · completed 2019 · 37 registered sales
1 bedAED 3.32m8563,8468
2 bedAED 5.05m1,2814,06422
3 bedAED 7.69m1,7204,3686
4 bedAED 9.2m5,0211,8321
TIARA RESIDENCE
Zabeel Investments (L.L.C) · completed 2009 · 36 registered sales
1 bedAED 3.95m1,2963,00917
2 bedAED 5.85m1,6773,47314
3 bedAED 10m2,3924,4135
THE PALM TOWER
The Palm - Jumeirah Co. (L.L.C) · completed 2021 · 34 registered sales
StudioAED 2.22m5234,28018
1 bedAED 4.58m1,0764,20916
FAIRMONT PALM RESIDENCE
The Palm Vacation Club FZE · completed 2010 · 32 registered sales
1 bedAED 2.6m1,3541,9916
2 bedAED 4.95m1,7672,80515
3 bedAED 9.15m4,9041,7648
4 bedAED 7.88m2,3773,3122
PenthouseAED 17m4,3803,8811
BALQIS RESIDENCE
Balqis Residence FZE · completed 2019 · 27 registered sales
StudioAED 1.78m7032,5331
1 bedAED 2.1m1,2601,6681
2 bedAED 4.4m1,9772,16213
3 bedAED 6.18m2,4332,5635
4 bedAED 11.75m5,3811,9922
5 bedAED 18.85m12,0462,0414
6 bedAED 34m17,3591,9591
SERENIA RESIDENCES THE PALM
Palma Homes Real Estate Development L.L.C · completed 2018 · 25 registered sales
1 bedAED 3.25m1,0192,9958
2 bedAED 6.27m1,7243,70513
3 bedAED 10.45m3,4472,9883
4 bedAED 50.3m12,8693,9091
EMERALD PALACE KEMPINSKI
Sunny Beach Properties Ltd O.F · completed 2010 · 19 registered sales
2 bedAED 4.7m1,9692,36214
3 bedAED 8.4m3,7902,1053
4 bedAED 10.09m4,5792,1992
PALM VIEWS - WEST
The Palm - Jumeirah Co. (L.L.C) · completed 2014 · 17 registered sales
StudioAED 1.41m5482,62016
1 bedAED 2.9m1,1072,6191
SERENIA LIVING
Palma Homes Real Estate Development L.L.C · completed 2025 · 17 registered sales
2 bedAED 8.3m1,8974,53725
3 bedAED 12.25m2,7954,38814
4 bedAED 19.7m4,4644,0597
ELLINGTON BEACH HOUSE
Beach House Real Estate Development L.L.C · completed 2024 · 15 registered sales
1 bedAED 3.9m1,1373,4313
2 bedAED 7.16m1,4184,7978
3 bedAED 14m2,0456,8463
4 bedAED 16m3,4024,7031
GRANDEUR RESIDENCES
ETA Star Property Developers L.L.C · completed 2012 · 15 registered sales
1 bedAED 2.17m1,1181,9678
2 bedAED 4.05m1,8991,9925
3 bedAED 6.5m2,5642,5361
4 bedAED 16.25m5,2903,0721
PALM VIEWS - EAST
The Palm - Jumeirah Co. (L.L.C) · completed 2014 · 13 registered sales
StudioAED 1.5m5482,73213
AZURE RESIDENCE
The Palm - Jumeirah Co. (L.L.C) · completed 2016 · 12 registered sales
1 bedAED 3m1,1432,6299
2 bedAED 5.85m2,0182,5863

DLD register — sales of units registered 28 April 2025 to 24 October 2026, duplicates removed. The sale count is the building’s registered sales of completed property.

How this table is built

Buildings with ten or more registered sales of completed property in the window are listed by default; the rest are behind “Show all buildings”. Hotel rooms and serviced units are left out where the register marks them. “Completed property” is the register’s own registration type, which does not separate an owner’s resale from a developer’s first sale of a finished unit, so neither do we. Bedroom medians are over the building’s registered sales in the window and are shown only where at least five sales of that type. AED/sqft on a row is the register’s median rate for that type, or median price over median size where it publishes none.

Two towers in the same block can sit points apart on net yield once service charges and occupancy are counted. Name the buildings and we will tell you which side of that line each one sits.

Under construction now

Projects the register records as under construction here, with the registered sales behind each figure; a project with fewer than ten is marked as a small sample. Hotel rooms and serviced units are left out where the register marks them.

ProjectCompleteMedian AED/sqftSalesMedian price by unit
Passo By Beyond
Estate Grand Real Estate Development L.L.C · register end date Dec 2029
Project brief
0%
at 24 Mar 2026
5,8132281 bed AED 4.85m · 2 bed AED 8.78m · 3 bed AED 13.44m · 4 bed AED 22.65m · 5 bed AED 56.54m (2 sales) · 6 bed AED 90m (3 sales)
+3.8% Q4 2025 → Q3 2026
The Alba Residences by Omniyat
Grandeur Beach Real Estate Development L.L.C · register end date Mar 2028
Project brief
8.4%
at 1 Sep 2026
8,811302 bed AED 18.88m · 3 bed AED 31.64m · 4 bed AED 67.56m · 6 bed AED 225.97m (one sale)
Olaia Residences
Gulf House Real Estate Development L.L.C · register end date Dec 2027
14.3%
at 21 Jul 2026
271 bed AED 4.72m · 2 bed AED 6.51m · 3 bed AED 8.7m · 5 bed AED 21.71m (one sale)
Palm Beach Towers - 2
The Palm - Jumeirah Co. (L.L.C) · register end date Dec 2026
81.6%
at 12 Aug 2026
3,227261 bed AED 3.21m · 2 bed AED 6.2m · 3 bed AED 8.23m · 4 bed AED 12.26m (2 sales)
Palm Beach Towers -1
The Palm - Jumeirah Co. (L.L.C) · register end date Dec 2026
82.8%
at 12 Aug 2026
3,297
5 sales
181 bed AED 3.3m (4 sales) · 2 bed AED 5.1m · 3 bed AED 9.68m (4 sales) · 4 bed AED 16.95m (one sale)
Palm Beach Towers -3
The Palm - Jumeirah Co. (L.L.C) · register end date Dec 2026
74.3%
at 12 Aug 2026
3,462
8 sales
181 bed AED 4m · 2 bed AED 5.2m (4 sales)
Vitalia by Pinnacle
Pinnacle A K S Real Estate Development L.L.C · register end date Jun 2026
12.3%
at 30 Jun 2026
5,381
3 sales
162 bed AED 9.21m · 3 bed AED 16.2m (4 sales) · 4 bed AED 22.86m (2 sales)
Como Residences
The Palm - Jumeirah Co. (L.L.C) · register end date Mar 2027
Project brief
24.8%
at 9 Oct 2026
5,669
7 sales
123 bed AED 52.6m · 4 bed AED 57.27m
OCEAN HOUSE
Northacre Ellington Development L.L.C
Project brief
80.7%
at 3 Sep 2026
5,200
6 sales
102 bed AED 9.36m (4 sales) · 3 bed AED 18.95m
ORLA BY OMNIYAT
Crescent 17 Real Estate Developments L.L.C · register end date Dec 2026
Project brief
70%
at 21 Aug 2026
7,010
4 sales
92 bed AED 22.41m (one sale) · 3 bed AED 33.7m (4 sales) · 4 bed AED 79.85m (3 sales) · 5 bed AED 59.11m (one sale)
Armani Beach Residences At Palm Jumeirah
Arada Developments L.L.C S.O.C · register end date Dec 2027
10.2%
at 20 Jul 2026
52 bed AED 26.46m (one sale) · 3 bed AED 39.36m (one sale) · 4 bed AED 48.96m (one sale) · 5 bed AED 91.2m (2 sales)
ORLA Infinity by OMNIYAT
Crescent 16 Real Estate Development L.L.C
Project brief
61.3%
at 26 Aug 2026
9,639
2 sales
54 bed AED 65.44m
AVA AT PALM JUMEIRAH BY OMNIYAT
Ava Residences Real Estate Developments L.L.C · register end date Jun 2026
Project brief
95.9%
at 26 Aug 2026
24 bed AED 46.02m (2 sales)

All projects under construction in Palm Jumeirah

DLD project register (completion percentage as read on the date shown) and transaction register — sales of units registered 28 April 2025 to 24 October 2026, duplicates removed.

How this table is built

Completion percentage is the register’s own, read on the date shown against each project. The median is over the project’s registered sales in the window and is published only from ten sales; quarterly movement only where each quarter holds twenty or more. Hotel rooms and serviced units are left out where the register marks them.

Completion percentage and the register’s own median are the two numbers a payment plan should be read against.

Developments here

Nakheel · ~10,000+ units · launched 2001
Palm Jumeirah
The developer, the launch date and the unit count are this guide’s own, as captured.

What a development here is worth today is a register question, and we will read it back to you building by building.

Deals below market here now

UnitAskingSizePer sq ft
2-BR IN SLS RESIDENCES THE PALM
handover Q4 2026
AED 8,325,435
3.9% below o.p.
2,242 sq.ftAED 3,713
2-BR IN SLS RESIDENCES THE PALM
handover Q4 2026
AED 7,277,490
3.2% below o.p.
1936 sq.ftAED 3,759
3-BR IN PALM BEACH - TOWER 2
handover Q4 2026
AED 7,950,000
11.5% below o.p.
2738 sq.ftAED 2,904

Mitchell’s deal pages, as published. Asking prices and the discount are stated on each deal’s own page with their basis; we act for the buyer on every one.

Each of these can be read against the register history of its own building before you commit.

Project briefs

Mitchell's project briefs, written from the developer's own material.

New launches

Mitchell's new-launch pages, as published.

PALM JUMEIRAH: DUBAI'S MOST ICONIC WATERFRONT ADDRESS

There is no address in Dubai that is more immediately identifiable to the outside world, and that global brand recognition is one of the most potent drivers of property value in this market. The Palm is not simply a residential community; it is a statement of intent. For investors who need their Dubai asset to be understood, valued and recognised internationally — whether by future buyers, tenants or partners — there is no substitute.

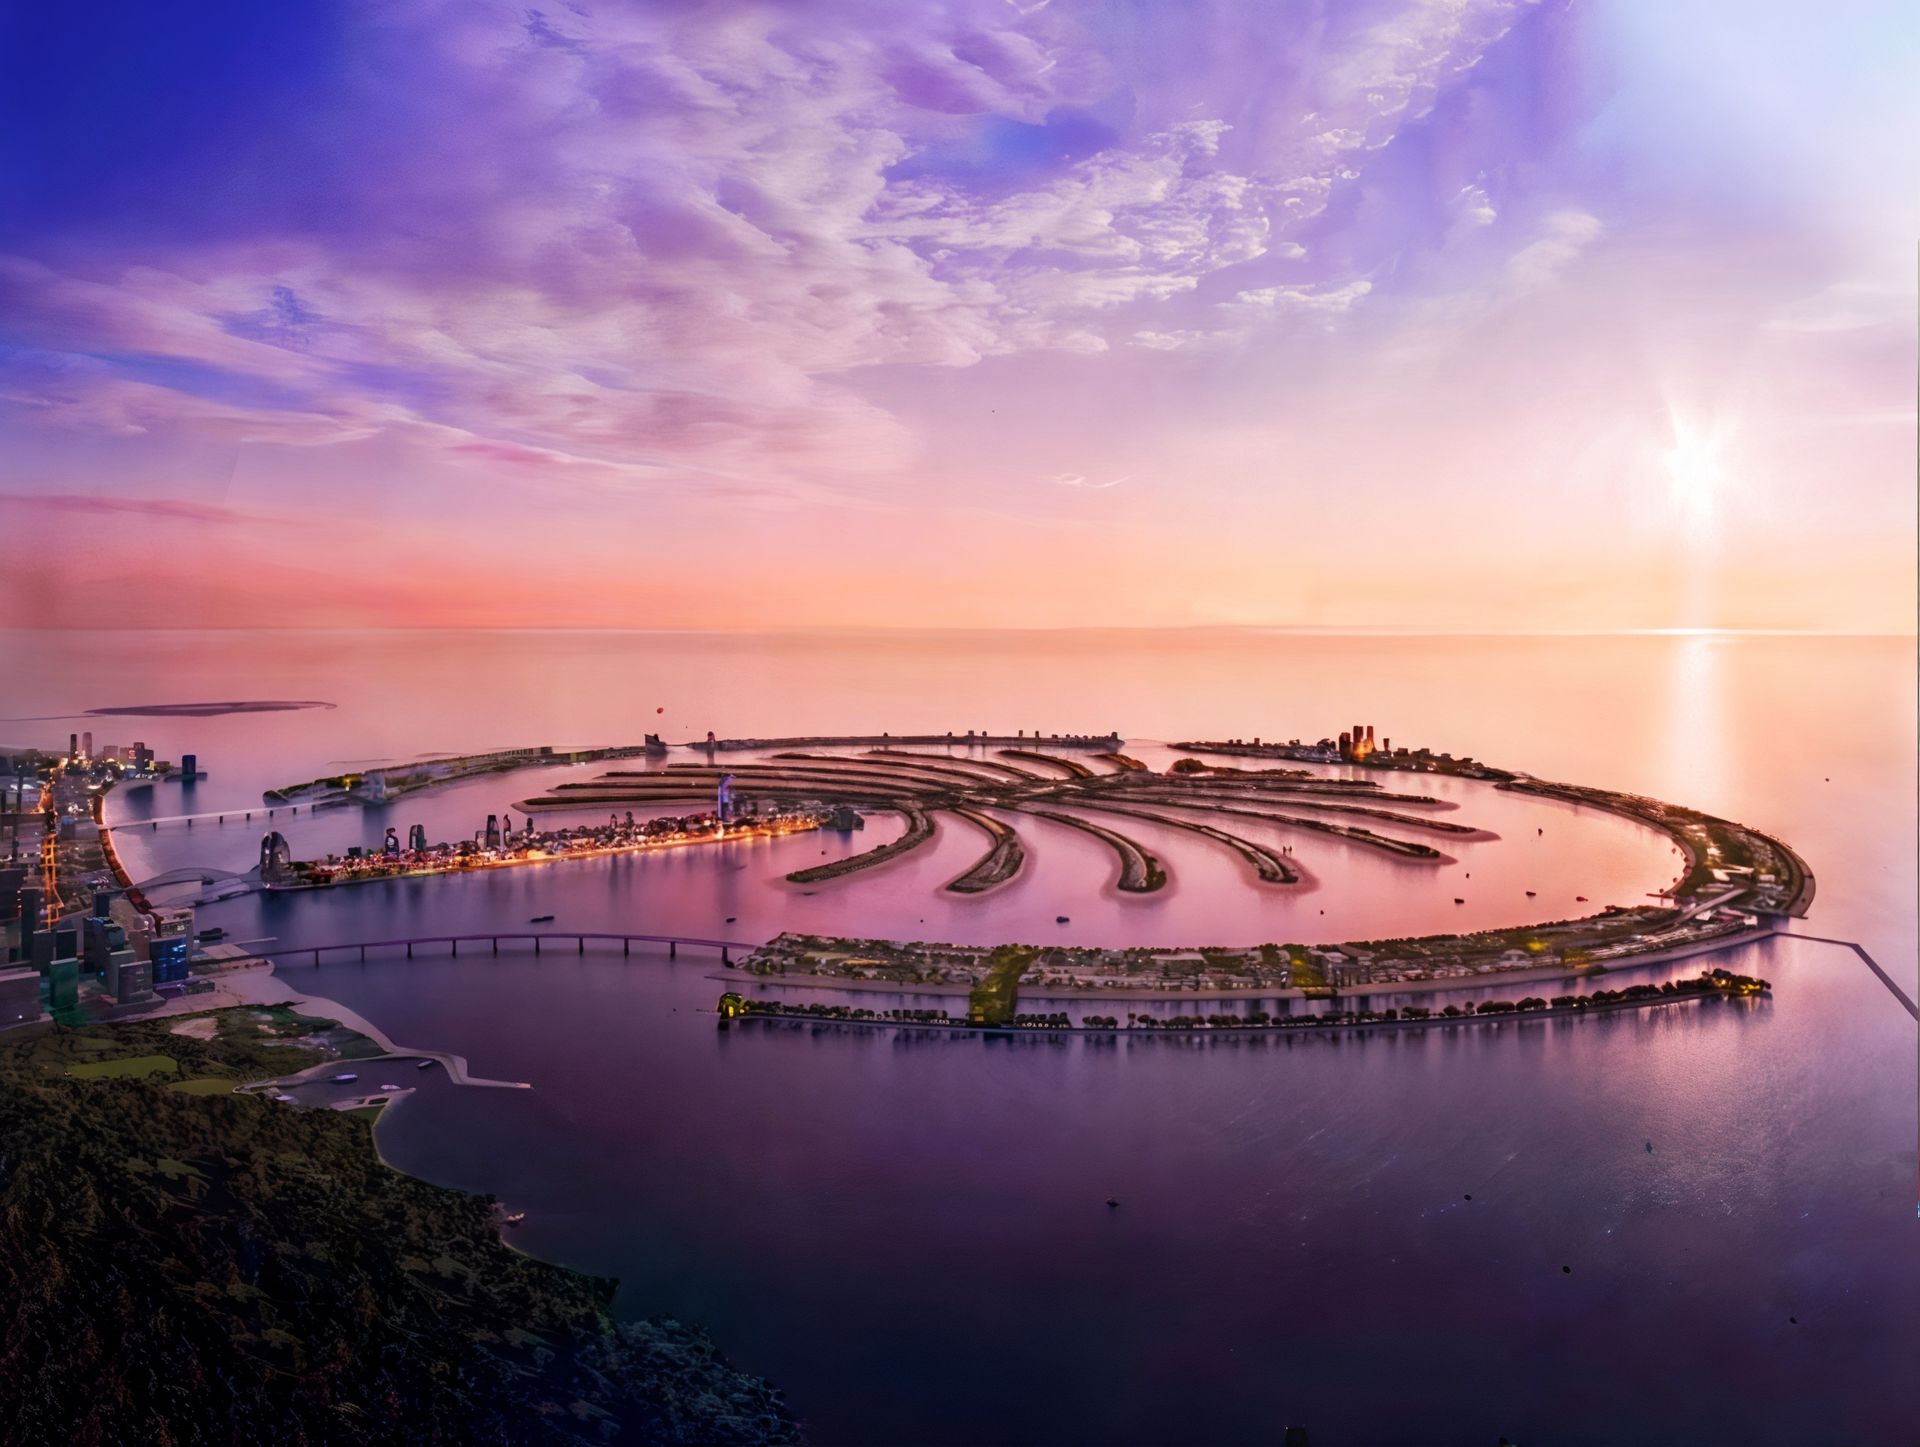
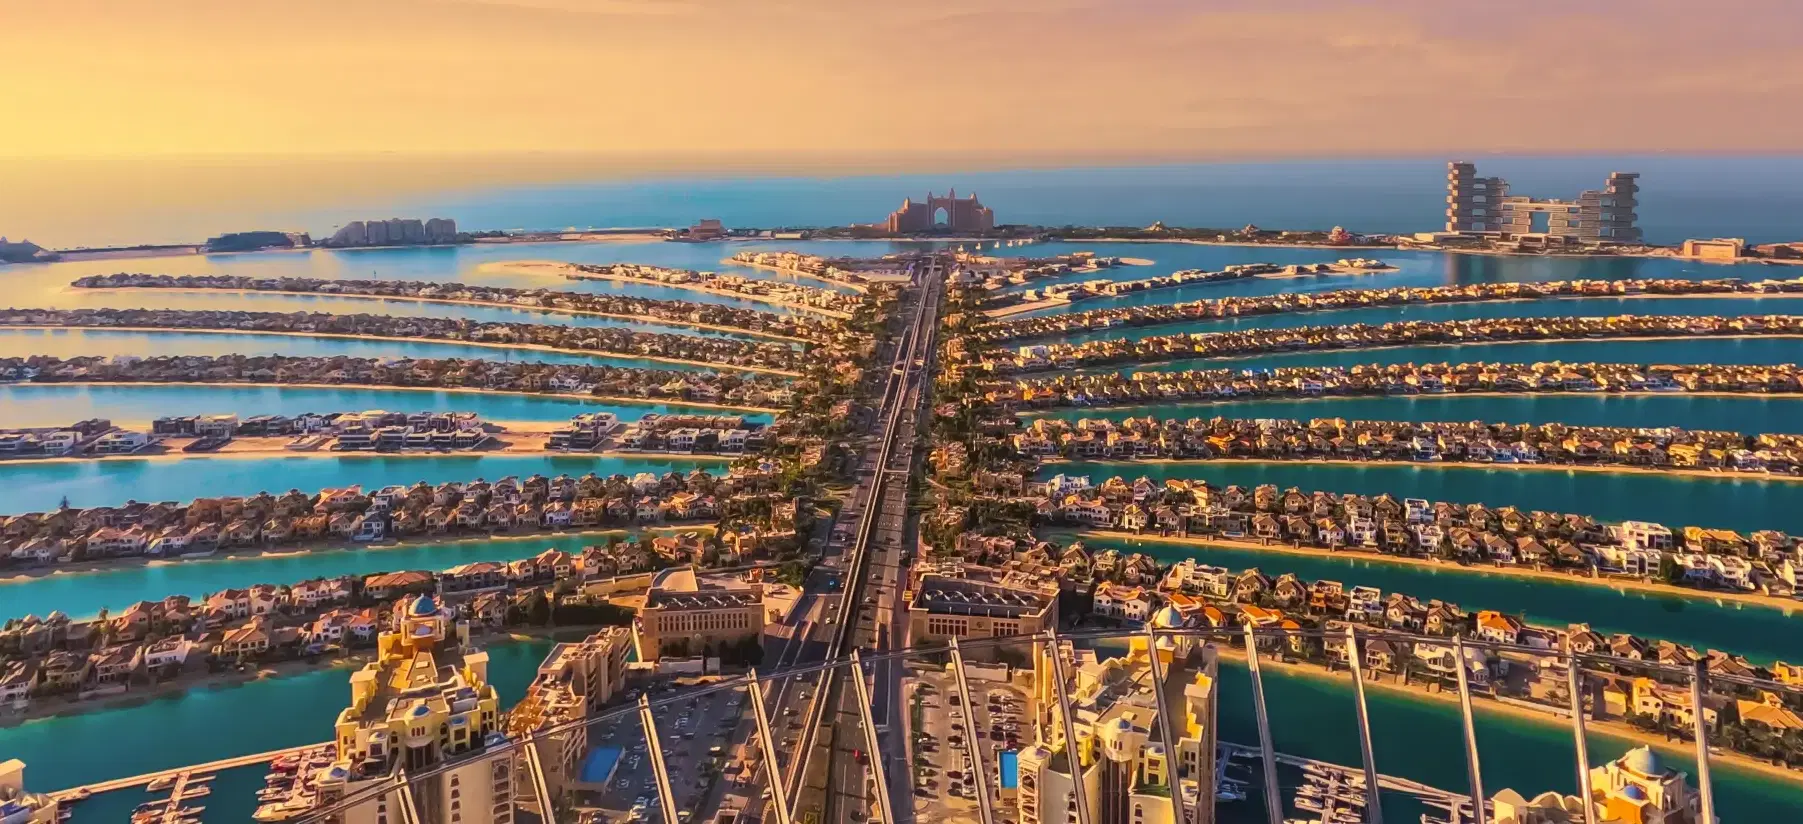
Palm Jumeirah was developed by Nakheel as an artificial island extending into the Arabian Gulf, adding approximately 78 kilometres of coastline to Dubai. Construction began in 2001 and the first residents moved in around 2006 to 2008. The community comprises the Trunk, the Fronds and the Crescent, each offering distinct product types and price points. The Trunk is primarily high-rise apartments and hotel residences; the Fronds offer private villa plots with beach access; the Crescent is dominated by the Atlantis resort complex and ultra-premium hotel residences.

The product mix on the Palm is genuinely diverse. Entry-level apartments on the Trunk can be acquired from around AED 1 million, while Frond villas with private beach access typically trade from AED 10 million to over AED 50 million for the most premium positions. The diversity of price points means the Palm can accommodate a range of investor profiles — from yield-focused apartment buyers to ultra-premium villa purchasers focused on capital preservation and lifestyle value.

Pricing on the Palm has followed Dubai's broader trajectory, but with an important distinction — the Palm premium has historically been persistent and significant. Even during periods of market correction, Palm Jumeirah values have tended to hold relatively better than comparable properties elsewhere in Dubai, reflecting the brand's unique position. Post-2020, the Palm experienced substantial price appreciation driven by international wealth migration and strong demand for large-format beachfront homes from globally mobile buyers.

The branded residences segment has emerged as one of the most active and high-growth pockets within the Palm. Developments such as One Palm by Omniyat, Atlantis The Royal Residences and the W Residences have established new pricing benchmarks for branded hospitality-managed inventory, often trading at AED 4,500 to 8,000 per square foot — a meaningful premium over standard Trunk apartments. This segment now defines the upper end of the Palm apartment market and increasingly sets the comparable benchmark for ultra-premium pricing across Dubai.

In the sections that follow, I will break down the market analysis across infrastructure and connectivity, rental market dynamics and tenant profile, and supply constraints. I will then offer a practical investment strategy framework — the product types, entry points and positioning logic that I use when advising clients considering Palm Jumeirah as part of their Dubai portfolio.

PALM JUMEIRAH: MARKET ANALYSIS AND INVESTMENT DYNAMICS

INFRASTRUCTURE AND CONNECTIVITY

Palm Jumeirah is accessed via the Palm Jumeirah Monorail and a primary road tunnel connecting to Sheikh Zayed Road and the broader emirate network. The Palm Monorail links the island to the Gateway Towers at the base and to Atlantis at the far end of the Crescent. For residents, the primary route is by car — Palm Jumeirah Road runs the length of the Trunk and connects to all Frond access roads. The Palm is served by Nakheel Mall — one of Dubai's largest community malls — as well as The Pointe, a waterfront dining and retail destination on the Palm's outer crescent. Proximity to Dubai Marina and JBR means residents have access to one of the city's densest entertainment and dining corridors. International schools, medical facilities and five-star hotels are all accessible within or immediately adjacent to the island.

RENTAL MARKET AND TENANT PROFILE

The rental market on Palm Jumeirah is strong, diverse and consistently in demand. Apartment rentals on the Trunk attract a broad international tenant base — expatriate professionals, couples and small families drawn by the waterfront lifestyle, proximity to JBR and Dubai Marina, and the prestige of a Palm address. Rental yields for Trunk apartments typically range from 5 to 7 per cent gross, making this segment one of Dubai's better-performing yield plays relative to its brand profile. Villa rentals on the Fronds are at a completely different level — annual rents for large beachfront villas commonly range from AED 500,000 to AED 1.5 million per year, and tenants are typically UHNW individuals or corporate relocation packages. The Palm's short-term rental market, driven by holiday platforms, is also well-established, with many Trunk apartments generating strong short-term returns due to the volume of international visitors attracted by Atlantis, the hotel corridor and the Palm's global brand.

SUPPLY DYNAMICS AND PORTFOLIO POSITIONING

Palm Jumeirah is a fixed land asset — no new island can be built alongside it, and the total number of Frond villas and Trunk apartments is structurally constrained by the island's geography. While new developments have been added within the island's limits over the years — including One Palm and several hotel residences — the core Frond villa and Trunk apartment stock is now largely delivered and trading on the secondary market. This supply constraint is a key pillar of the Palm's long-term value case. The Trunk apartment market does have more ongoing competition from new hotel residences and branded apartment launches, so investors in that segment need to be aware of the competitive landscape. For Frond villa buyers, however, the supply picture is significantly tighter. In a portfolio context, Palm Jumeirah offers a blend of brand recognition, supply restriction and genuine rental demand — qualities that make it a core holding for any serious Dubai real estate investor.

PALM JUMEIRAH: INVESTMENT STRATEGY AND ENTRY POINTS

When I advise clients on Palm Jumeirah entry points, the first question I ask is: are you buying for yield, capital growth, or both? The answer shapes the strategy fundamentally. For yield-focused investors, the Trunk apartment segment is the clearest opportunity — mid-floor, well-maintained apartments in established buildings with good building management and rental history. Studios and 1-bedroom units in the AED 1 to 2.5 million range have historically delivered solid yields and liquid secondary market exits. For capital growth buyers, the Frond villa market offers more compelling long-term upside — the combination of scarcity, beachfront access and global brand recognition means that well-positioned Frond villas have historically outperformed over five to ten year holding periods.

The branded residences and hotel-apartments segment on the Palm deserves specific mention. Developments like One Palm, XXII Carat and the Atlantis The Royal residences attract buyers who want both the Palm address and the full-service hotel management infrastructure. These products typically trade at a significant premium to standard Trunk apartments, but offer professional management, high-end amenities and access to an international rental market. For investors who want passive income from a trophy address without operational complexity, this segment has become increasingly relevant. The premium is real, but so is the convenience.

A complementary diversification strategy is to pair a Palm Jumeirah position with a Tier 2 Yield & Volume income asset in Jumeirah Lake Towers or The Greens, and a Tier 3 Growth position in Dubai South, Dubai Creek Harbour or Expo City. Palm Jumeirah provides the trophy-address Tier 1 capital-and-brand leg of a three-tier Dubai portfolio, with the Tier 2 apartment supplementing cashflow and the Tier 3 leg providing long-duration growth upside. For investors seeking exposure to Dubai's premium waterfront cluster, JBR, Bluewaters Island and Emaar Beachfront offer alternative Tier 1 entry points with distinct character and pricing.

If you are considering Palm Jumeirah, the key is not deciding whether the area works — it clearly does, for a wide range of investor profiles. The question is which segment, which product type, and which price point aligns with your specific objectives. The Palm is one of Dubai's most liquid markets, meaning you can enter and exit with relative confidence — but that liquidity also means you need to be precise about what you are buying and why. My advice is to focus on product quality, building management, and specific floor and view position before committing. The Palm's address premium is real, but within that premium, individual asset quality still determines investment outcomes, typically suiting portfolios at the AED 1,500,000–50,000,000 capital commitment level depending on segment.

SUPPLY DYNAMICS

Nakheel master developer, fixed island geography, Trunk and Frond largely delivered

TENANT PROFILE

Expat professionals on Trunk apartments, UHNW individuals on Frond villas, short-let tourists

KEY RISK FACTORS

Premium pricing, branded Trunk competition, high service charges, Frond illiquidity, marine upkeep

KEY INFRASTRUCTURE

Palm Jumeirah sits off the Dubai Marina coastline with vehicle access via the Palm Jumeirah Road tunnel from Sheikh Zayed Road (E11) and the Palm Jumeirah Monorail providing public transit between Gateway Towers, Nakheel Mall, Atlantis The Palm and Atlantis The Royal at the Crescent. The island is internally anchored by Nakheel Mall (one of Dubai's largest community malls), The Pointe waterfront dining and retail destination, Atlantis The Palm, Atlantis The Royal, Five Palm hotel, RIVA Beach Club, Aquaventure Waterpark, the Boardwalk promenade, beach clubs, fine dining outlets and 78 km of new coastline across the Trunk, 16 Fronds and Crescent. Nearby external anchors include Bluewaters Island, Ain Dubai, Dubai Marina, JBR, Mall of the Emirates and Madinat Jumeirah. Adjacent communities include Dubai Marina, JBR, Bluewaters Island and Dubai Harbour, reinforcing Palm Jumeirah's positioning as Dubai's most iconic global trophy waterfront address.

Area fundamentals

ASSET PROFILE
Global trophy waterfront island; yield and capital store
INVESTOR PROFILE
International UHNW buyer + yield investor + lifestyle
TIER
Tier 1 – Core Capital
MARKET TYPE
Iconic, branded apartments and beachfront villas
EST. POPULATION
~25,000–35,000
LAND SIZE
~61.6m sq ft

Next step

Request a briefing

You will get Palm Jumeirah as a brief: the buildings on this page, the register readings behind them, and our view on each.
Sent with your enquiry:Palm Jumeirahpurpose not statedbudget not statedno buildings on screenasked from: the brief

We come back with specifics, not a brochure. Stephen Mitchell · RERA BRN 68593 · in Dubai since 2007.

Location

Palm Jumeirah, Dubai

Get Directions

Try it yourself

Investor Tools

Rental Yield Calculator

Model the gross and net return on a Dubai buy-to-let purchase. It covers service charges, void periods and acquisition costs.

All-in purchase price before transaction costs.

Total contracted rent for one year, before charges.

Community and building service charges, annualised.

5%

Your buffer for void periods. 5% is about 18 days empty a year — a month is 8%.

7%

7% is the 4% DLD transfer fee, 2% agency plus VAT, and DLD's flat registration lines. It excludes the developer NOC and any legal quote — see the Buying Costs Calculator for the full itemisation.

6% net

The net yield a deal has to clear to interest you. Sets the target line on the curve — it does not change the yield above it.

5.3%Net rental yield
Moderate yield
Gross yieldGross yield: 7.00%
Net annual incomeNet annual income: AED 84,750
Monthly net incomeMonthly net income: AED 7,063
Total cash investedTotal cash invested: AED 1,605,000

Against your 6% hurdle

Short of it
9.1%0%AED 975KAED 2.03M
Net yield (vertical) against the price you pay (horizontal), on the rent, charges and costs entered. The gold dot is your deal; the line across is your hurdle.
Price that clears it
AED 1,320,093AED 179,907 below your price — a 12.0% discount.
Rent that clears it
AED 117,158AED 12,158 a year more than you have entered, at this price.

Estimates for guidance only, assuming full-year occupancy net of the vacancy allowance above. Actual returns depend on financing, unit condition and market timing — speak to an advisor for a deal-specific model.

Email my results

We’ll send this summary — your figures and the results — to your inbox.

Next step

We'll hunt deals that meet or beat this yield hurdle

Send us this scenario and we'll go into the market against it — on-market and off — qualify what we find, and only come back with what clears your number.

Got questions?

Get Answers!
Continue reading

The closest area guides to this one, matched on subject.

Showing 4 of 101 Dubai area guides.

Browse all 101 area guides
Need help?