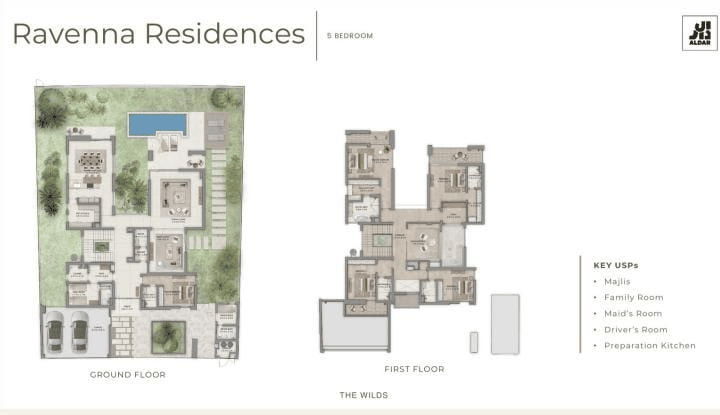
This five-bedroom villa in The Wilds - Ravenna, Dubailand, is offered at AED 16,500,000. The source records an original price plus the 4% DLD fee of AED 17,160,000, so the asking figure sits AED 660,000, or 3.9%, below original price. The villa occupies a 13,718 sq.ft plot with 6,762 sq.ft of built-up area over ground plus one floor, which puts the entry basis at AED 2,440 per sq.ft on built-up area. It is a corner plot with a private pool, a balcony and allocated parking, and handover is stated as Q2 2029. The developer is Aldar. The plot is the striking figure: at 13,718 sq.ft it is more than twice the built-up area, so the house sits within genuinely generous grounds rather than filling its boundary.
Available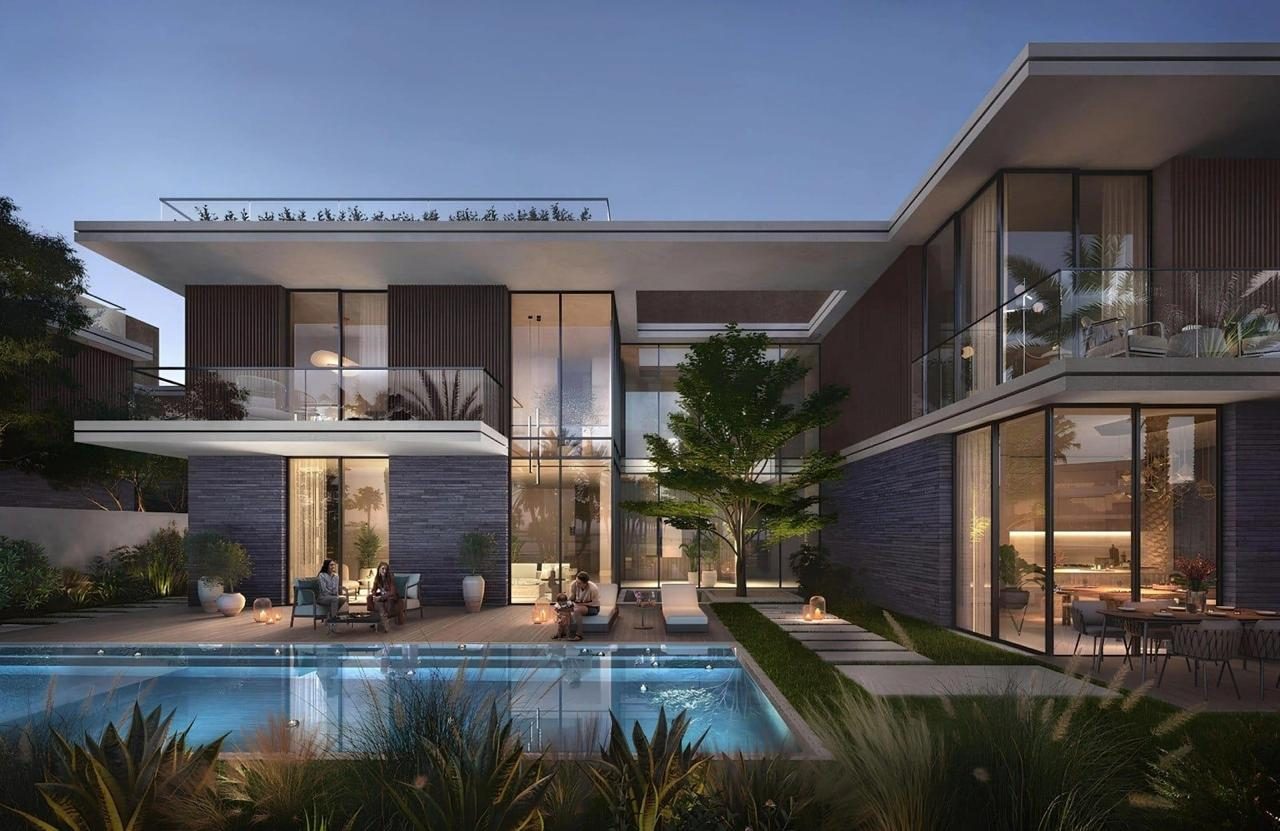 THE WILDS - RAVENNA · The Wilds
Aldar · The Wilds
DISTRESS DEAL: 5-BR IN THE WILDS - RAVENNA
Asking priceAED 16,500,000AED 2,440 per sq.ft
Original price + DLDAED 17,160,000
DiscountAED 660,0003.9% below original price
- Unit
- 5-BR
- Size
- 6,762 sq.ft
- Developer
- Aldar
- Handover
- Q2 2029
The discount is measured against the original price + DLD recorded for this unit, not against a valuation.
Available
Listed 19 August 2026
Available when we last checked. The asking price shown is the one published when the listing was added on 19 August 2026, and it is not re-checked against the market automatically. Confirm availability and price with us before you act on it.
On this page
Quick navigation
The unit
Unit details
- Property type
- Villa
- Plot
- 13,718 sq.ft
- Floor
- G+1
Layout
Floor plan
Distress Deal
PROJECT DESCRIPTION
OVERVIEW
LOCATION & TRANSPORT
Dubailand sits south-east of the city centre, in the band of land between Sheikh Mohammed Bin Zayed Road and the Dubai–Al Ain Road. It is an area that has moved from open land to established residential district over the past decade, and the remaining low-density plots are what make villa schemes of this scale possible at all this close to the city. Sheikh Mohammed Bin Zayed Road provides the orbital connection north towards Sharjah and south-west towards Jebel Ali and Abu Dhabi, while Al Ain Road runs north-west into Dubai Silicon Oasis, Academic City and on towards Downtown. Global Village and IMG Worlds of Adventure lie a short distance to the south. Travel here is by car. The corridor has continued to attract family buyers for precisely this reason.
AMENITIES & SURROUNDING
The Wilds is planned as a low-density villa community organised around landscaped wadis, naturalistic planting and open green corridors rather than around a golf course or a retail spine, which gives the scheme a quieter and more secluded character than the denser communities nearby. Community parks, walking and cycling routes and shared leisure facilities run through the plan. The established retail, schooling and clinical base of Dubai Silicon Oasis and Academic City lies to the north-west, with Global Village and the Dubailand leisure cluster to the south. This particular villa holds a corner plot with its own private pool, balcony and parking. For the community's full amenity schedule, the service charge position and the floor plan, please contact us. Plot boundaries, landscaping obligations and pool maintenance arrangements all vary within schemes of this type, so it is worth establishing exactly what applies to this plot.
MARKET
The 3.9% reduction is measured against the original price plus the 4% DLD registration fee, the basis the source publishes, and it compares the asking figure with what the first buyer committed rather than with current resale evidence. We have not attached a valuation. At AED 2,440 per sq.ft on built-up area the basis is high for the Dubailand corridor, and that is the correct reading: the price is carrying a 13,718 sq.ft corner plot as well as a 6,762 sq.ft house, and a per-square-foot figure calculated on built-up area alone understates what is being bought. Handover is stated as Q2 2029, so the outstanding developer instalments will be substantial relative to the payment due to the seller at transfer. We hold the schedule.
CONCLUSION
This suits a buyer who wants land as much as house: a corner plot of nearly 14,000 sq.ft with a private pool, in a low-density community within the city rather than beyond its edge, with a 2029 handover. Plot size and corner position are the attributes that cannot be improved after purchase, and in a scheme of this type they set the resale ceiling. The 3.9% reduction against original price is incidental to the case rather than central to it. The long horizon to 2029 means the instalment profile deserves particular attention, and we will set it out alongside the transfer costs and the seller's position. For the floor plan, the payment schedule and current availability, please get in touch.
Location
THE WILDS - RAVENNA — The Wilds, Dubai
Illustrative model
Scenario modeller
Set your own assumptions and see how DISTRESS DEAL: 5-BR IN THE WILDS - RAVENNA behaves as a cash purchase, the same purchase mortgaged, or a capital-only resale.
Listed
19 August 2026
The date this listing was added to our records. The asking price below is the one published then, and is not re-checked against the market automatically — confirm it with us before relying on it.
Below original price
3.9%
As stated on this listing: the asking price measured against the original purchase price recorded for this unit. It is not a discount to current market value and not a valuation — a unit priced below what it originally sold for may still be at or above what comparable units achieve today. Check the registered comparables before treating the gap as equity. It is not used in any calculation below.
Asking price per sq.ft
AED 2,440/sqft
The asking price divided by the stated size. Compare it against registered sales in the same building before deciding whether the asking price is competitive.
Handover
Q2 2029
As stated on this listing. Rent cannot start before handover, so on an incomplete unit the early years of the schedule below are holding cost only.
Total cash investedThe purchase price plus every cost of getting the keys. It is the denominator of the ROI, ROE and IRR figures.
AED 17.5M
Price plus every acquisition cost
Illustrative exit price
AED 16.5M
After 5 yr at 0.0% p.a.
Total profit, capital onlyCapital movement over the hold, less every purchase and sale cost and the service charge. It carries no rental income at all, because no rent has been set.
—
Set service charge, maintenance & management, vacancy allowance above
Net yieldNet operating income (rent collected less management, maintenance and service charge) divided by the purchase price. It cannot be calculated until a gross annual rent is set.
—
Set a gross annual rent
Cash out, and cash back over 5 years
Set service charge, maintenance & management, vacancy allowance above to see cash back — until then this figure would be assuming zero for them.
Cash required at completion
Purchase priceAED 16,500,000
DLD transfer fee (4%)AED 660,000
Agency fee (2%)AED 330,000
VAT on agency fee (5%)AED 16,500
Conveyancing, trustee & adminAED 0
Total cash investedAED 17,506,500
ROI and IRR are calculated on this figure: the price plus every cost of getting the keys.
No rental evidence is held for this unit. The rent figure is yours to set — we have not assumed one. Until you enter a gross annual rent, the yield, ROI/ROE and IRR figures reflect capital movement and costs only.
Annual operating position
Gross annual rentAED 0
Vacancy allowance (not set)—
Maintenance & management (not set)—
Service charge (6,762 sq ft at a rate not yet set)—
Net operating income—
Figures marked “—” need service charge, maintenance & management, vacancy allowance entered above — we do not compute them on an assumed zero.
Cash-flow schedule — the 5-year figures the IRR is solved from (incomplete, see note)
| Year | Net operating income | Sale proceeds, net | Net cash flow |
|---|---|---|---|
| 0 · today | — | — | −AED 17,506,500 |
| 1 | AED 0 | — | AED 0 |
| 2 | AED 0 | — | AED 0 |
| 3 | AED 0 | — | AED 0 |
| 4 | AED 0 | — | AED 0 |
| 5 | AED 0 | AED 16,153,500 | AED 16,153,500 |
| Years 1–5 | AED 0 | AED 16,153,500 | AED 16,153,500 |
| Less the year-0 outflow of AED 17,506,500 → total profit | −AED 1,353,000 | ||
Exit at year 5: illustrative sale price AED 16,500,000 less selling costs AED 346,500 = AED 16,153,500 net. The final column is the schedule the IRR is solved from. Rent is held flat in nominal terms — the rent-growth field is at 0% — as is the service charge, so no inflation is assumed on either side. This audit table is arithmetic, so every row must resolve to a number — but service charge, maintenance & management, vacancy allowance are not set above, and the figures here currently assume zero for them. Nothing on this table should be read as a result until you set them; the headline tiles above withhold theirs for exactly this reason.
Sensitivity — the same purchase at −5% to +5% exit growth
| Exit growth | Exit price | Total profit | ROI | IRR |
|---|---|---|---|---|
| −5% p.a. | AED 12.8M | — | — | — |
| −3% p.a. | AED 14.2M | — | — | — |
| 0% p.a.your figure | AED 16.5M | — | — | — |
| 3% p.a. | AED 19.1M | — | — | — |
| 5% p.a. | AED 21.1M | — | — | — |
Each row re-runs the whole model with only the exit growth rate changed, over the same 5-year hold. The 0% and negative rows are not a worst case — they are simply what the same purchase returns if prices do not rise. Dubai prices have fallen in the past and can fall again. The return columns are shown as “—” until a gross annual rent is set; the total profit column reflects capital movement, purchase and sale costs and the service charge only.
Method
- Handover
- The date the unit is handed over, set in quarters from purchase. Gross rent, the vacancy allowance, maintenance and management, and the service charge all start there and not before — an unbuilt unit cannot be let and is not billed. The year handover falls in gets the exact fraction it is entitled to, not a rounded whole year. Capital growth is not treated this way: it compounds from today across the whole hold, because an off-plan unit can be sold before it completes. Where the holding period ends before handover, there is no operating income anywhere in the schedule and the whole return is capital movement less costs.
- Gross yield
- Gross annual rent ÷ purchase price. Before every cost. Where handover is in the future this is a stabilised full year from handover — a rate on the price, not a figure reduced by the construction period. The schedule shows what each year actually books.
- Net yield
- (Rent collected after the vacancy allowance − maintenance and management − service charge) ÷ purchase price. Stabilised on the same basis as the gross yield.
- Rent growth
- Compound annual movement in gross rent, applied from handover and stepping at each anniversary of it, which is when a tenancy renews. It may be negative. It does not touch the service charge, which is held flat in nominal terms.
- ROI
- Total profit over the whole hold ÷ total cash invested (price + all acquisition costs). Unlevered. Not an annual rate.
- ROE
- Total profit over the whole hold ÷ equity contributed (deposit + all acquisition and finance costs), after debt service. Levered. Not an annual rate.
- Cash-on-cash return
- Year-one operating cash flow, after debt service where there is a mortgage, ÷ cash invested. Reported separately from ROI/ROE and never merged with it. Year one means the first year of the schedule as it stands: where that year falls before handover it carries no rent, so on a mortgaged off-plan purchase the figure is negative — that is the year you fund out of pocket, and it is shown rather than smoothed away.
- IRR
- The annualised rate that discounts the dated cash-flow schedule above to a net present value of zero, solved numerically. Where the schedule has no sign change, or the solver does not converge on a single meaningful rate, we print “—” rather than substitute a simpler annualised-return figure.
Email my results
We’ll send this scenario — your assumptions and the figures they produce — to your inbox.
Set service charge, maintenance & management, vacancy allowance above and we can email you this scenario. Until then every headline figure reads “—”, because the model would otherwise be assuming zero for them — and we publish no figure for them.
An illustrative model, not a forecast, a valuation, an offer or investment advice. Every figure is generated from the assumptions on this page — some yours, the rest stated defaults, not promises. Rents, service charges, fees, vacancy, handover dates, financing terms and sale prices vary by unit and over time; past prices are not a guide to future prices. Returns are not guaranteed and capital is at risk.
Mortgage availability, loan-to-value, rate and term are subject to lender criteria and underwriting; nothing here indicates that finance will be offered. Figures exclude any tax payable in your country of residence — take independent financial, tax and legal advice before committing. Mitchell's Commercial Real Estate is a trading brand; the RERA-licensed broker is Stephen James Mitchell, BRN 68593.
More deals
The latest distress deals
The most recently listed deals that were still available when we last checked. Sold units are not shown here.
Al Kifaf
DISTRESS DEAL: 3-BR IN PARK VIEWS RESIDENCES B
AED 3,461,928AED 3,300,000Asking price
4.7%Below O.P.
- Size
- 1,632 sq.ft
- Price / sq.ft
- AED 2,022
- Developer
- Wasl
- Handover
- Q4 2026
Business Bay
DISTRESS DEAL: 1-BR IN BINGHATTI SKYRISE - TOWER C
AED 2,106,000AED 1,700,000Asking price
19.3%Below O.P.
- Size
- 966 sq.ft
- Price / sq.ft
- AED 1,760
- Developer
- Binghatti
- Handover
- Q1 2028
Maritime City
DISTRESS DEAL: 1-BR IN SARIA
AED 1,954,160AED 1,700,000Asking price
13.0%Below O.P.
- Size
- 829 sq.ft
- Price / sq.ft
- AED 2,051
- Developer
- Beyond
- Handover
- Q1 2028
City Walk
DISTRESS DEAL: 1-BR IN VERVE - TOWER B
AED 2,647,840AED 2,250,000Asking price
15.0%Below O.P.
- Size
- 834 sq.ft
- Price / sq.ft
- AED 2,698
- Developer
- Meraas
- Handover
- Q1 2028
Beachfront
DISTRESS DEAL: 2-BR IN BEACH VISTA 2
AED 4,524,000AED 3,550,000Asking price
21.5%Below O.P.
- Size
- 1,205 sq.ft
- Price / sq.ft
- AED 2,946
- Developer
- Emaar
Bluewaters Island
DISTRESS DEAL: 2-BR IN BLUEWATERS BAY - BUILDING 1
AED 5,402,800AED 4,800,000Asking price
11.2%Below O.P.
- Size
- 1,340 sq.ft
- Price / sq.ft
- AED 3,582
- Developer
- Meraas
- Handover
- Q3 2027
Read next
A discounted unit is bought the same way any other is. The questions are just sharper. These are our own guides and articles on buying from overseas, taking on a resale or an off-plan assignment, and what the purchase costs.
The gold rule under an entry is its length, against the longest piece here.
Guides
How to Buy Dubai Property from Overseas
Power of attorney, attestation country by country, remote AML checks, funding the purchase, and remote signing against a short trip.
How to Buy Ready (Secondary) Property in Dubai
The fixed sequence the Land Department sets for a resale — an agreed Form F, a deposit, a developer NOC and the Trustee Office transfer.
Pre-Handover Assignment (Off-Plan ‘Flipping’) in Dubai: How It Works
Assigning an off-plan unit before handover — the developer NOC and minimum-paid rules, the fees that come off the profit, and when it still loses money.
Off-Plan Payment Plans in Dubai Explained: 10/90, 50/50 and Post-Handover
Construction-linked and post-handover structures, what escrow protects at each stage, and what happens if a later instalment cannot be funded.
NOC (No Objection Certificate) for a Dubai Property Purchase
What the developer’s certificate confirms, how service-charge clearance runs through Mollak, and the usual reasons issuance is delayed.
How to Vet a Dubai Developer Before You Buy
Brochures are marketing; DLD registration, project escrow status and broker licensing are checkable public facts. How to verify all three.
A Due-Diligence Checklist for Buying in Dubai
Who owns the title, whether the unit carries a mortgage or a restriction, and whether its service charges are current. In order, with the tool that verifies each.
The True Cost of Buying Property in Dubai: All Fees Explained
Transfer, trustee office, agency commission, developer NOC and the mortgage costs, each set against the Land Department’s own published figures.
Mortgages for Non-Residents in Dubai
What a genuine non-resident can borrow, as distinct from a UAE-resident expatriate, which banks lend, and how a purchase is completed remotely.
Capital Gains & Property Tax in Dubai: What Investors Actually Pay
What an individual owner is and is not charged here, which transaction cost is the real one, and why your home-country position is a separate question.
Articles
How to Buy a Cancellation Unit in Dubai: Strategic Guide
A cancellation unit is a launch booking the first buyer lost — how they reach the market, and the steps to secure one at launch pricing.
How to Buy Dubai Property During Crisis and Build a Portfolio at Peak Fear
The historical entry points, yields by district, and a contrarian acquisition process for buying when confidence is at its lowest.
Buying a Resale Property in Dubai: Step-by-Step Guide for Investors
The process, the legal steps, the costs and the mortgage options, for residents and international investors alike.
How to Buy Property in Dubai as a Foreign Investor: Step-By-Step Guide
Costs, the legal process, the risks, and how to structure the investment — written for a buyer outside the UAE.
Buying Off-Plan Property in Dubai: Primary Market Guide
The primary market end to end. EOIs, SPAs, payment plans, Oqood, escrow, resales and mortgages.
Residential Mortgages in Dubai: Guide for Expats and Investors
Rates, loan-to-value limits, eligibility, fees and the documents a lender asks for, for residents and investors.