Palm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,148/sqftDowntown Dubai AED 2,920/sqftDubai Islands AED 2,769/sqftDubai Creek Harbour AED 2,564/sqftBusiness Bay AED 2,511/sqftDubai Marina AED 2,484/sqftDubai Hills Estate AED 2,446/sqftJumeirah Lakes Towers AED 2,304/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,048/sqftJumeirah Village Triangle AED 1,664/sqftDubai South AED 1,651/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,492/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,148/sqftDowntown Dubai AED 2,920/sqftDubai Islands AED 2,769/sqftDubai Creek Harbour AED 2,564/sqftBusiness Bay AED 2,511/sqftDubai Marina AED 2,484/sqftDubai Hills Estate AED 2,446/sqftJumeirah Lakes Towers AED 2,304/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,048/sqftJumeirah Village Triangle AED 1,664/sqftDubai South AED 1,651/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,492/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO OCT 2026
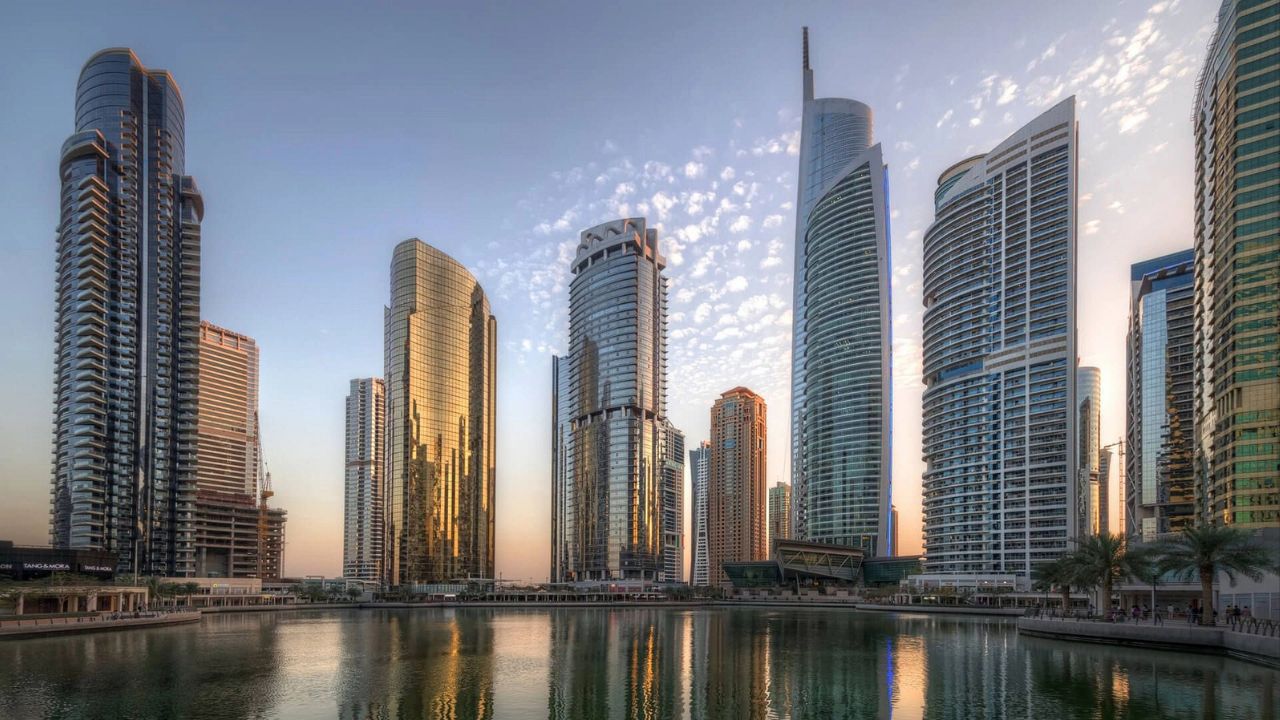
Jumeirah Lake Towers, Dubai — area guide

Area guide · Dubai

Jumeirah Lake Towers Investment Guide

When I discuss JLT with investors, I often describe it as Dubai Marina's working neighbour — the community that houses the professionals who work in Dubai Marina or the adjacent free zones, without the premium pricing that the marina waterfront commands.

I want to
Budget

Answer the two questions and this page reorders itself around them. Nothing is sent until you ask for something.

Sales prices

2,304AED/sqft
Median price, whole register
DLD register — median of 2,353 sales in the twelve months to 5 October 2026. Pools off-plan registrations with sales of completed property, every property type. Across the register 69.1% of those rows are off-plan registrations and 30.9% sales of completed property.
400–700AED/sqft, 2002
Launch price
Developer launch pricing when the community came to market, from this guide. Historic — not a current valuation.

A building can sit well under the area figure. Tell us which one you have in mind and we will read its own register history back to you.

Rental rates

~5–7%
Gross yield band
Mitchell’s own range for Jumeirah Lake Towers, from this guide — an assessment, not a register figure.

The register gives one rent figure for the area. What a specific building lets for, and how quickly, is the question worth asking before you buy for income.

Ready buildings with recent sales

Median registered price per bedroom type. Hotel rooms and serviced units are left out where the register marks them.

BuildingUnitMedian priceMedian sq ftAED/sqftSales
MBL Royal
MBL Royal Development DMCC · completed 2025 · 57 registered sales
1 bedAED 1.71m8702,00027
2 bedAED 3m1,4132,12211
3 bedAED 4.63m2,2402,08118
5 bedAED 20.15m12,8591,5671
CONCORDE TOWER
32 Group Properties Limited · completed 2008 · 45 registered sales
StudioAED 790,0004531,7443
1 bedAED 1.12m8791,21042
LAKE VIEW
DAMAC Properties Co (L.L.C) · completed 2009 · 45 registered sales
StudioAED 717,5004201,71716
1 bedAED 1.12m8551,24220
2 bedAED 1.8m1,5221,2607
PenthouseAED 1.53m1,2171,2532
GOLD CREST VIEWS2
Star Gigaestablishment Limited · completed 2010 · 40 registered sales
StudioAED 742,5003702,00716
1 bedAED 1.23m7991,5348
2 bedAED 1.35m9501,51011
3 bedAED 2.2m1,5111,3605
LAKE TERRACE
DAMAC Properties Co (L.L.C) · completed 2008 · 38 registered sales
StudioAED 850,0004971,68715
1 bedAED 1.16m7371,57714
2 bedAED 1.66m1,2641,3086
3 bedAED 2.28m1,4781,5433
MBL RESIDENCE
MBL Development DMCC · completed 2021 · 34 registered sales
1 bedAED 1.6m7862,03628
2 bedAED 2.5m1,3371,8696
LAKE CITY TOWER
Tiger Properties · completed 2008 · 33 registered sales
StudioAED 710,0004091,7354
1 bedAED 1.04m8401,29024
2 bedAED 1.55m1,2451,2475
ARMADA TOWERS
Mohammad Rahif Hakmi · completed 2010 · 32 registered sales
StudioAED 720,0004811,4985
1 bedAED 1.09m8801,26016
2 bedAED 1.75m1,3151,33111
SABA TOWER 2
Saba Properties DMCC · completed 2008 · 32 registered sales
StudioAED 750,0005301,4149
1 bedAED 1.24m8121,49114
2 bedAED 1.84m1,4451,2978
3 bedAED 2.32m1,9161,2101
GLOBAL LAKE VIEW
Venus International Holding Ltd · completed 2010 · 31 registered sales
StudioAED 750,0004511,6643
1 bedAED 1.01m7071,3198
2 bedAED 1.47m1,0191,46711
3 bedAED 1.85m1,3281,3949
LAGUNA TOWER
Laguna Tower Residence FZE · completed 2012 · 29 registered sales
StudioAED 399,2153701,0828
1 bedAED 1.43m1,1851,18812
2 bedAED 2.4m1,7581,2926
3 bedAED 3.25m2,4191,3433
LAKE SHORE TOWER
Al Bodor Real Estate Development Limited · completed 2009 · 29 registered sales
StudioAED 700,0005061,3841
1 bedAED 1.02m8761,12110
2 bedAED 1.64m1,4501,20417
3 bedAED 2.5m2,3461,0661
NEW DUBAI GATE1
Bonyan International Investment Group (Holding) (L.L.C) · completed 2010 · 28 registered sales
1 bedAED 700,0004501,34823
2 bedAED 1.23m1,0911,1422
3 bedAED 1.4m1,2281,1401
4 bedAED 2.69m2,5731,0412
SABA TOWER 3
Saba Properties DMCC · completed 2008 · 27 registered sales
StudioAED 780,0004571,6425
1 bedAED 1.08m7941,44814
2 bedAED 1.78m1,3791,3978
GOLD CREST EXECUTIVE
Star Gigaestablishment Limited · completed 2009 · 26 registered sales
StudioAED 747,7504061,89620
1 bedAED 1.02m7041,5266
ME DO RE
Me Do Re Properties DMCC · completed 2024 · 25 registered sales
StudioAED 1.16m4472,5706
1 bedAED 2.09m9312,1568
2 bedAED 2.78m1,4952,1519
3 bedAED 4.9m2,2632,1652
DUBAI ARCH TOWER
Aaber Facilites Management (L.L.C) · completed 2009 · 24 registered sales
StudioAED 780,0004061,7879
1 bedAED 1.29m1,0971,2039
2 bedAED 1.55m1,2331,3595
3 bedAED 2.6m1,7581,4791
LAKESIDE RESIDENCE
Al Manal Development FZCO · completed 2012 · 22 registered sales
1 bedAED 1.1m8171,40412
2 bedAED 1.79m1,1671,49010
PALLADIUM
ETA Star Property Developers L.L.C · completed 2007 · 21 registered sales
1 bedAED 1.24m9931,2482
2 bedAED 1.7m1,1871,47417
3 bedAED 2.63m1,8971,3862
V3
Sheikh Suroor Bin Mohd Alnehayan · completed 2009 · 19 registered sales
1 bedAED 1.02m8111,2529
2 bedAED 2m1,6251,2927
3 bedAED 3.2m2,1671,4783
BANYAN TREE RESIDENCES HILLSIDE DUBAI
Sweid & Sweid Hillside Development DMCC · completed 2020 · 18 registered sales
1 bedAED 2.12m9042,3328
2 bedAED 3.86m1,4692,6306
3 bedAED 5.5m2,1982,5033
4 bedAED 9m3,1492,8581
MADINA TOWER
REEF Real Estate Investment Co (L.L.C) · completed 2007 · 15 registered sales
1 bedAED 1.35m1,0121,33210
2 bedAED 2.8m2,0311,3825
AL SEEF II
Deyaar Development (P.J.S.C) · completed 2008 · 11 registered sales
2 bedAED 2.75m1,9661,51310
5 bedAED 7.2m5,5401,3001
ALSHERA TOWER
Saleh Bin Lahej Real Estate L.L.C · completed 2008 · 10 registered sales
1 bedAED 1.57m9931,5453
2 bedAED 2.6m1,7301,4215
3 bedAED 4.09m3,1961,2922

DLD register — sales of units registered 28 April 2025 to 5 October 2026, duplicates removed. The sale count is the building’s registered sales of completed property.

How this table is built

Buildings with ten or more registered sales of completed property in the window are listed by default; the rest are behind “Show all buildings”. Hotel rooms and serviced units are left out where the register marks them. “Completed property” is the register’s own registration type, which does not separate an owner’s resale from a developer’s first sale of a finished unit, so neither do we. Bedroom medians are over the building’s registered sales in the window and are shown only where at least five sales of that type. AED/sqft on a row is the register’s median rate for that type, or median price over median size where it publishes none.

Two towers in the same block can sit points apart on net yield once service charges and occupancy are counted. Name the buildings and we will tell you which side of that line each one sits.

Under construction now

Projects the register records as under construction here, with the registered sales behind each figure; a project with fewer than ten is marked as a small sample. Hotel rooms and serviced units are left out where the register marks them.

ProjectCompleteMedian AED/sqftSalesMedian price by unit
Diamondz By Danube
Danube Properties Development L.L.C
16.3%
at 20 Jul 2026
2,513222Studio AED 1.14m · 1 bed AED 1.89m · 2 bed AED 2.67m · 3 bed AED 3.7m · 4 bed AED 4.98m (one sale)
-10.3% Q2 2025 → Q1 2026
Saba 4
Saba 4 FZCO · register end date Jun 2027
30.4%
at 31 Jul 2026
2,4001341 bed AED 2.33m · 2 bed AED 3.39m · 3 bed AED 5.57m
+9.8% Q2 2025 → Q1 2026
UH WEST BY ELLINGTON
Ellington Properties Development L.L.C · register end date Mar 2026
71.3%
at 11 Jun 2026
1,93168Studio AED 912,500 (4 sales) · 1 bed AED 1.65m · 2 bed AED 2.49m · 3 bed AED 3.78m (3 sales)
UH EAST BY ELLINGTON
Ellington Properties Development L.L.C · register end date Mar 2026
46.8%
at 11 Jun 2026
1,90460Studio AED 985,000 (4 sales) · 1 bed AED 1.66m · 2 bed AED 2.51m · 3 bed AED 3.7m (3 sales)
Verde by Sobha
Sobha L.L.C · register end date Jun 2027
Project brief
85%
at 24 Aug 2026
2,105411 bed AED 1.73m · 2 bed AED 2.7m · 3 bed AED 3.89m (4 sales)
Viewz 2 By Danube
Danube Properties Development L.L.C · register end date Jun 2026
50%
at 21 Jul 2026
2,20539Studio AED 1.01m · 1 bed AED 1.59m · 2 bed AED 2.29m (4 sales) · 3 bed AED 6.12m (one sale) · 4 bed AED 7.9m (one sale)
Viewz 1 By Danube
Danube Properties Development L.L.C · register end date Jun 2026
50%
at 21 Jul 2026
2,15227Studio AED 988,500 · 1 bed AED 1.61m · 2 bed AED 2.2m (4 sales) · 4 bed AED 7.99m (3 sales)

All projects under construction in Al Thanyah Fifth

DLD project register (completion percentage as read on the date shown) and transaction register — sales of units registered 28 April 2025 to 5 October 2026, duplicates removed.

How this table is built

Completion percentage is the register’s own, read on the date shown against each project. The median is over the project’s registered sales in the window and is published only from ten sales; quarterly movement only where each quarter holds twenty or more. Hotel rooms and serviced units are left out where the register marks them.

Completion percentage and the register’s own median are the two numbers a payment plan should be read against.

Developments here

Multiple · ~35,000+ units · launched 2002
Jumeirah Lake Towers
The developer, the launch date and the unit count are this guide’s own, as captured.

What a development here is worth today is a register question, and we will read it back to you building by building.

Commercial units for sale here

Mitchell's commercial listings, as published.

JUMEIRAH LAKE TOWERS: THE DMCC COMMUNITY AND ITS INVESTMENT PROPOSITION

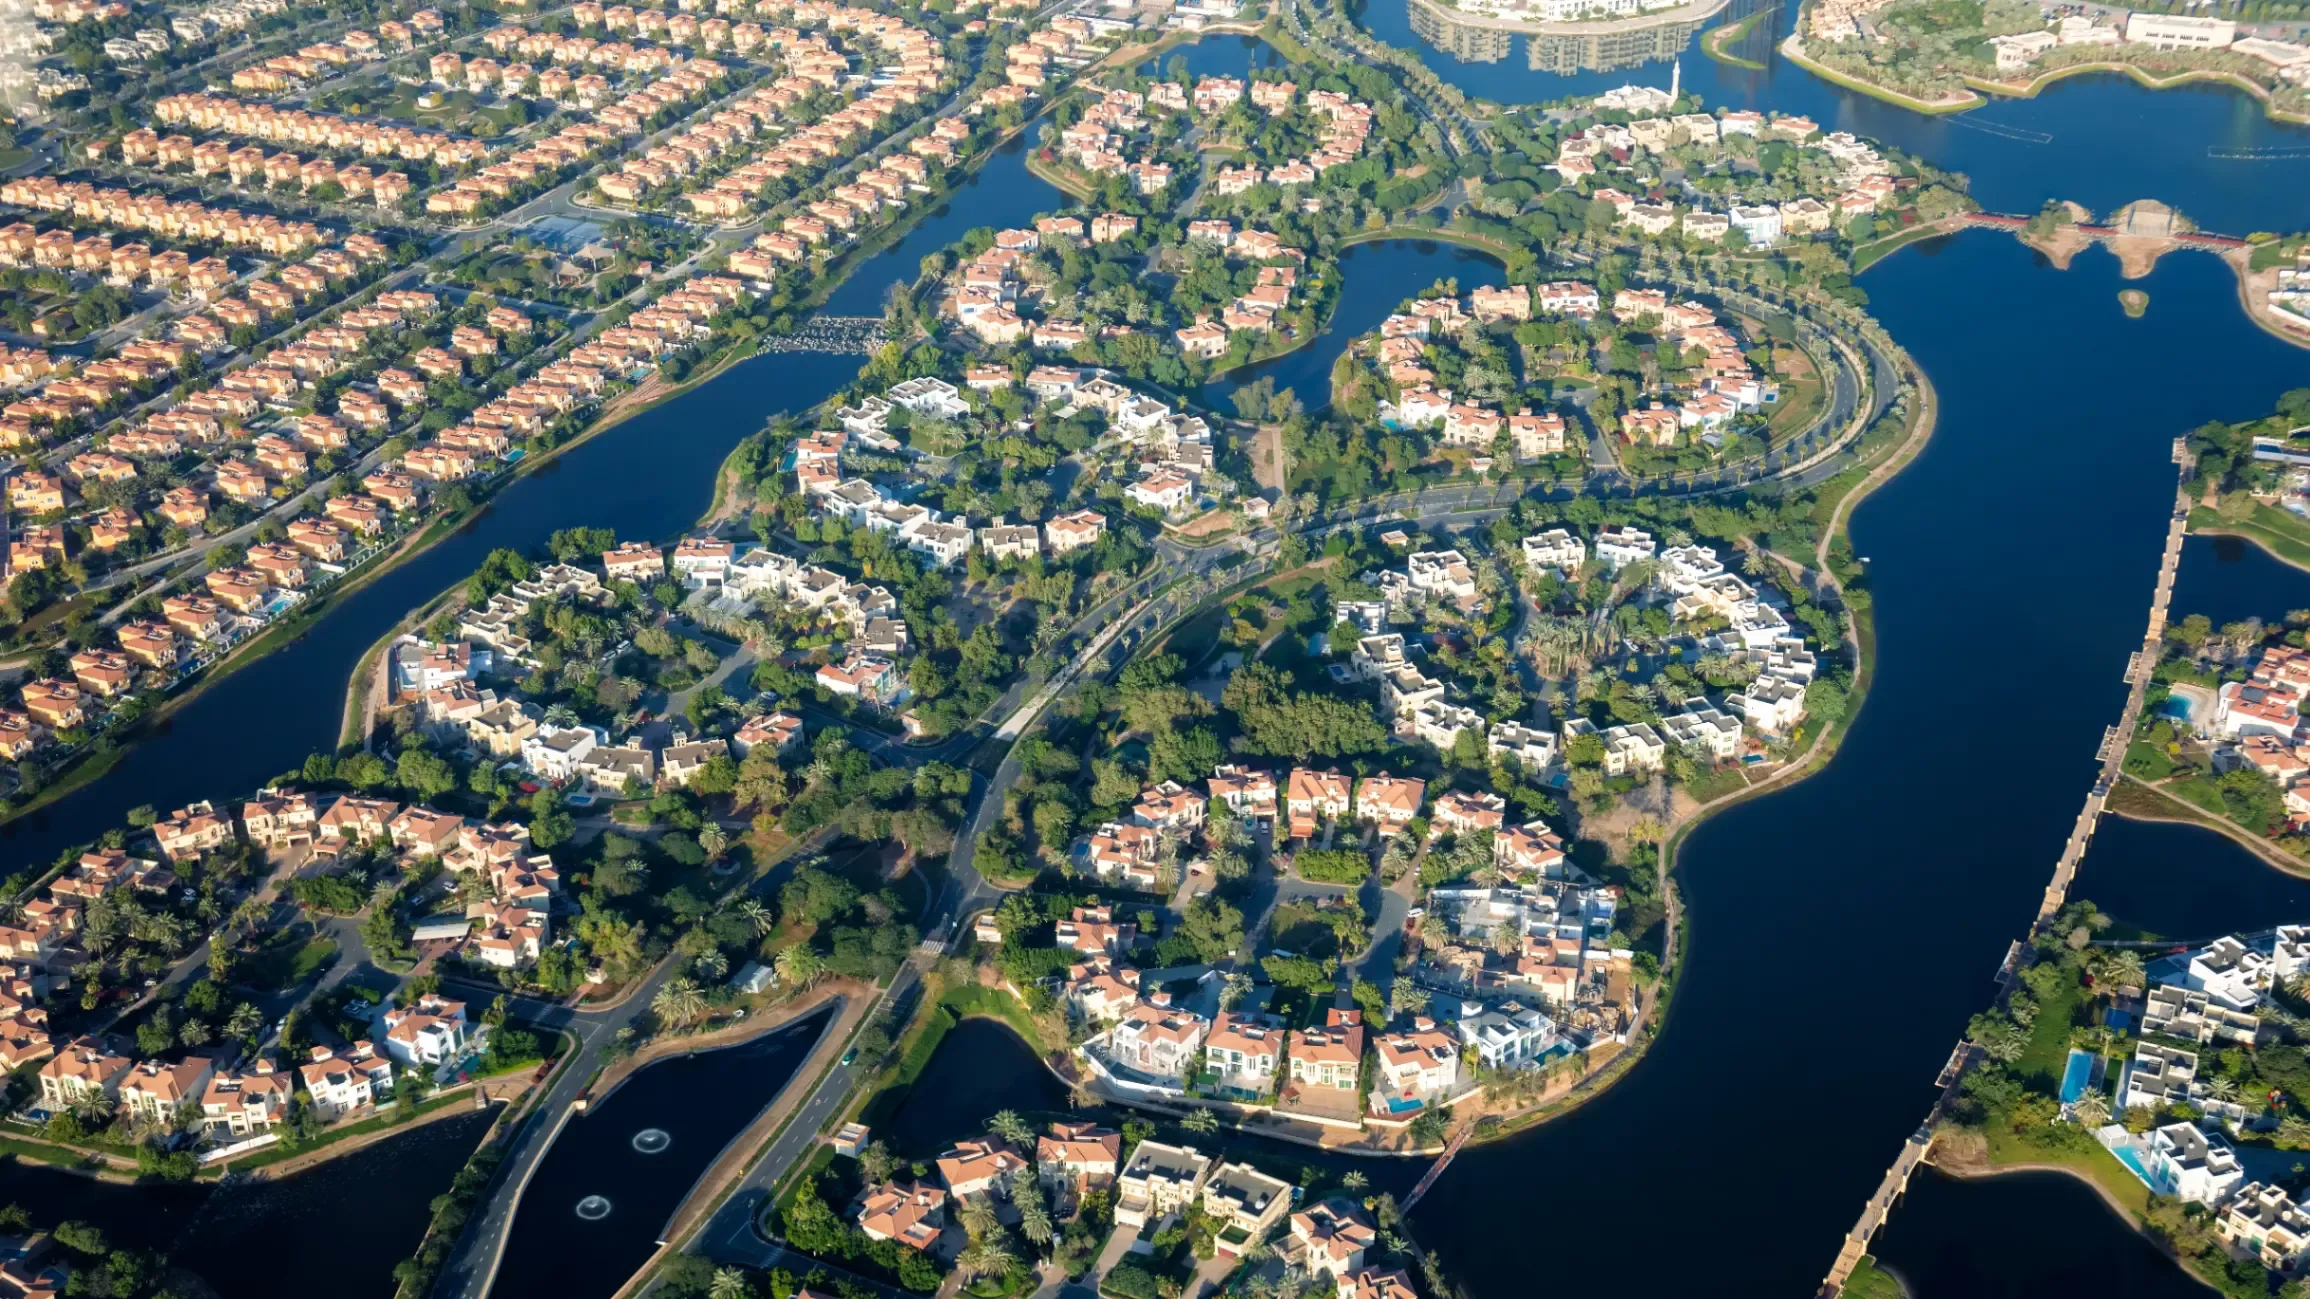
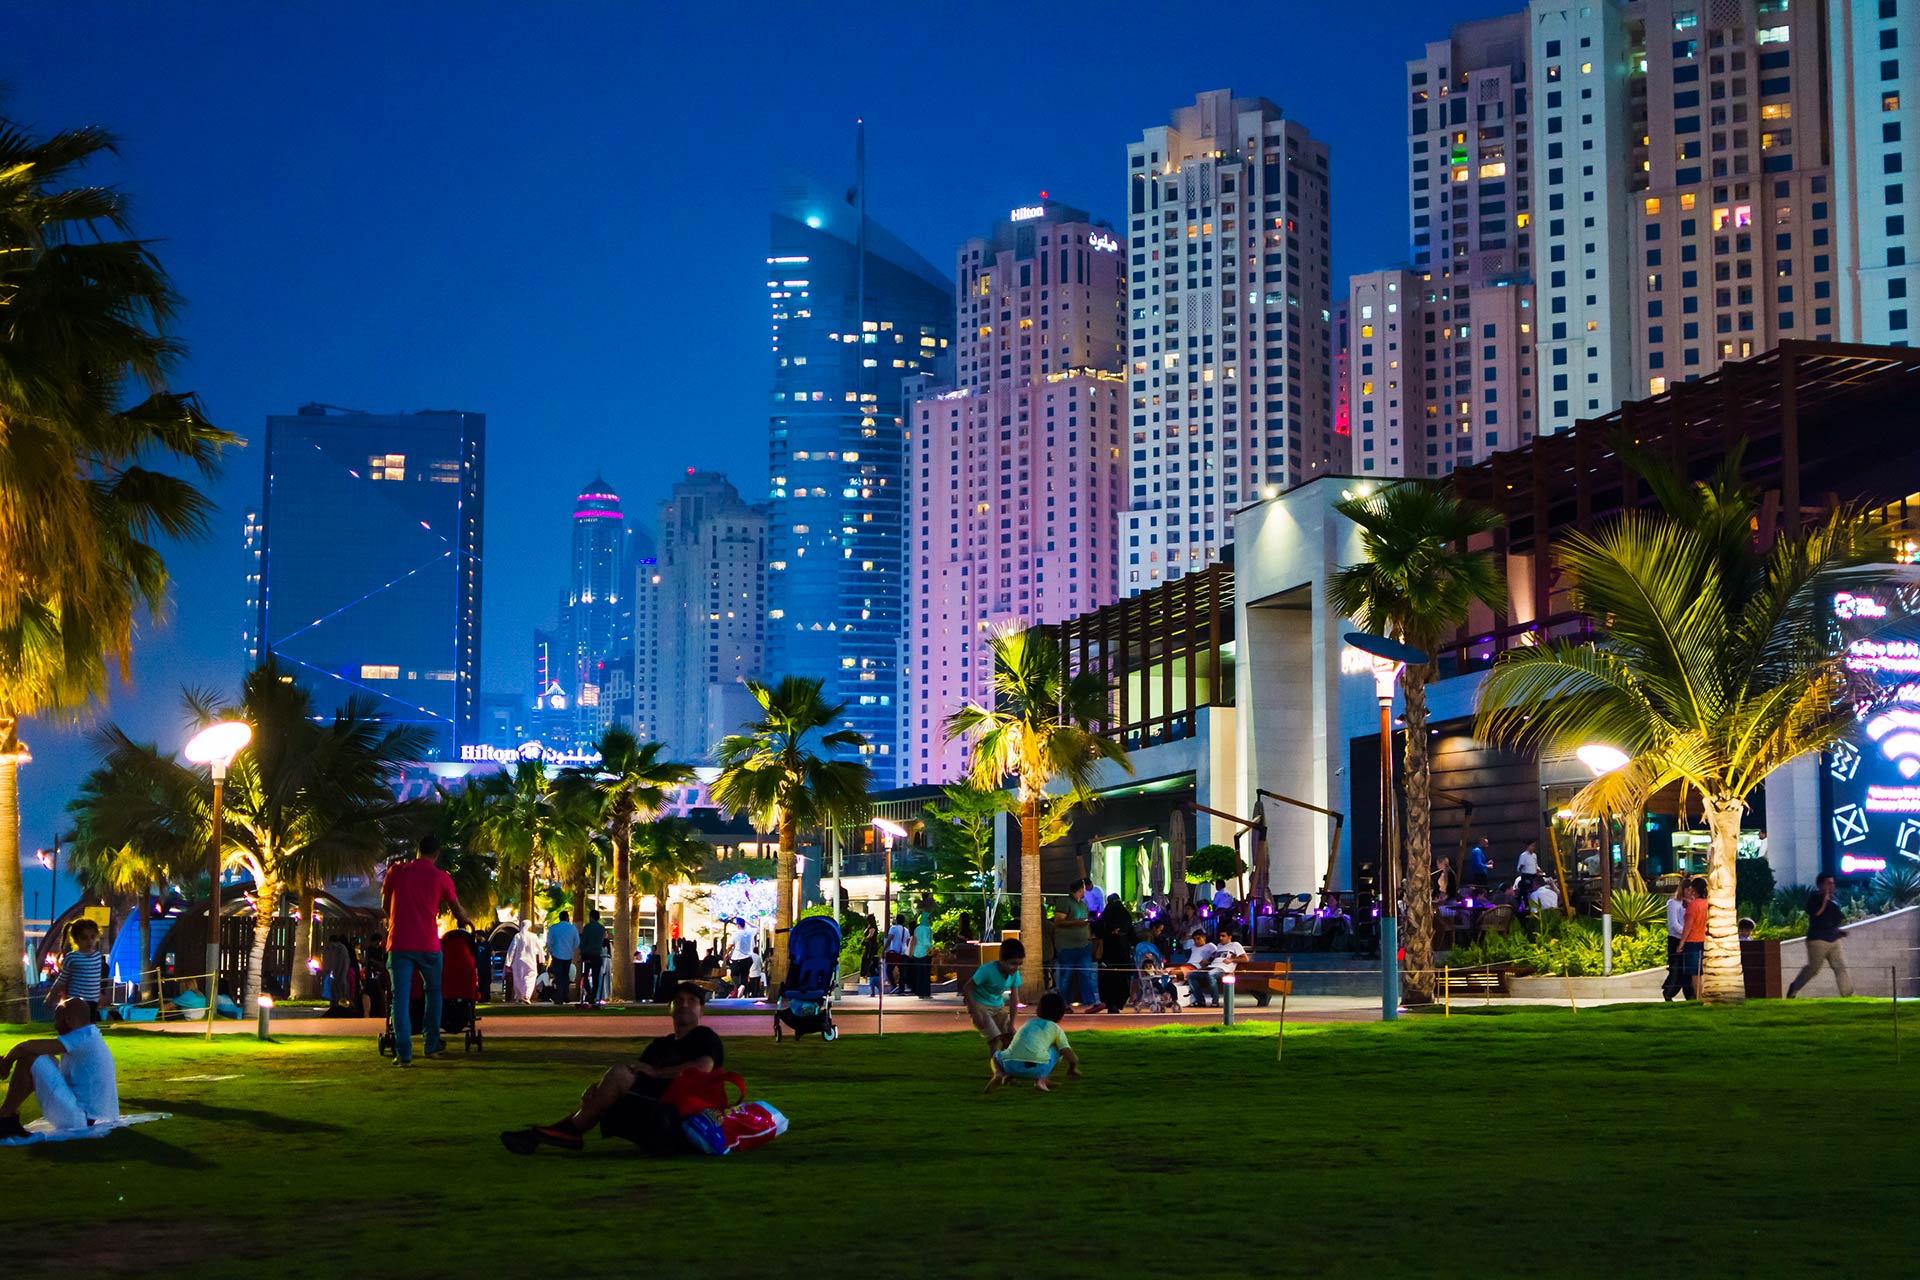
JLT is a DMCC free zone district consisting of 79 towers arranged in clusters around three artificial lakes, sitting directly adjacent to the Dubai Metro Red Line. The combination of metro access, competitive pricing relative to Marina, a genuine walkable community atmosphere and DMCC business registration flexibility makes JLT one of the more compelling mid-market investment cases in freehold Dubai. The question is not whether JLT works as a community — it clearly does — but whether the current pricing offers sufficient entry value and what the yield and growth dynamics look like at that entry point.

The Dubai Multi Commodities Centre (DMCC) is one of the world's largest free zones, established in 2002, and JLT was developed specifically as the residential and mixed-use district supporting the DMCC business community. Nakheel developed the residential towers, with multiple sub-developers responsible for individual tower projects within the 79-tower masterplan. The district covers approximately 200 hectares in the new Dubai corridor between Sheikh Zayed Road and Al Khail Road, with the Jumeirah Islands and the Emirates Hills community to the west and Dubai Marina to the south. The scale of the community — nearly 80 towers — means JLT has a genuine critical mass of resident population, retail, dining and daily amenity that supports independent community function.

Product mix in JLT is predominantly apartments across all sizes — studios, 1, 2 and 3-bedroom units in high-rise towers — with a meaningful component of ground-floor and podium commercial units that form the retail and F&B spine of the community. Studio and 1-bedroom apartments represent the core investor product, with studios available from AED 450,000–650,000 and 1-bedroom apartments from AED 700,000–1,100,000 depending on tower quality, floor level and lake view orientation. Lake-facing units command a premium of approximately 15–25 per cent over equivalent non-lake units within the same tower. There is no significant villa component; JLT is fundamentally an apartment community.

Price evolution in JLT has broadly tracked the wider Dubai market cycle, with a notable feature: the pricing gap between JLT and Dubai Marina has compressed over time as JLT has matured and demand for well-located mid-market product has increased. JLT launched at a discount to Marina, and while that relative discount remains, it has narrowed from the early years. The metro connectivity has been a consistent support to JLT pricing, and the district has held value better through Dubai's various market corrections than communities without metro access. Capital values on a per-square-foot basis remain meaningfully below Dubai Marina and the premium waterfront areas, presenting a relative value argument for investors who want metro-connected community living at a step below premium pricing.

In the sections that follow, I will examine JLT's infrastructure advantages — particularly the dual-station metro access and the Sheikh Zayed Road connectivity that makes this one of Dubai's most accessible mid-market communities — the rental market and the corporate tenant profile that drives consistent occupancy, and the supply dynamics of an 80-tower community that has largely completed its original development programme. I will close with a strategic framework for approaching JLT investment across different capital and yield objectives.

JUMEIRAH LAKE TOWERS: MARKET ANALYSIS AND INVESTMENT DYNAMICS

INFRASTRUCTURE AND CONNECTIVITY

JLT's infrastructure profile is one of its strongest investment attributes. The community is served by two Dubai Metro Red Line stations — DMCC (formerly Jumeirah Lake Towers) and Sobha Realty (formerly Dubai Marina) — providing direct metro access from both ends of the district. This dual-station metro coverage is rare in Dubai and eliminates the car-dependency issue that affects comparable mid-market communities. Sheikh Zayed Road (E11) runs along the eastern boundary, providing direct highway access to Downtown Dubai northward and Abu Dhabi Highway southward. The community's internal pedestrian infrastructure — the lakeside promenade, the cluster retail zones and the connectivity between towers — supports genuine walkability that is unusual in Dubai. Al Khail Road provides western connectivity. The combination of metro, major highway and walkable internals makes JLT one of Dubai's best-connected mid-market residential districts.

RENTAL MARKET AND TENANT PROFILE

JLT's tenant profile is predominantly working professionals — particularly those employed in the DMCC free zone, Dubai Marina businesses, and the Sheikh Zayed Road corporate corridor. The DMCC free zone hosts over 22,000 registered companies, providing a large and continuously renewing base of resident demand from employees and business owners. Studios achieve AED 50,000–70,000 per annum and 1-bedroom apartments AED 75,000–110,000, with lake-facing units commanding the upper end of the range. Gross yields typically fall in the 5–7 per cent range for well-located units, reflecting the mid-market positioning of the community. The tenant pool is stable and relatively low-turnover compared to more transient tourist or short-let dominated communities; DMCC professionals on multi-year employment contracts create a reliable tenant base. Some buildings attract significant short-term rental activity given the metro access and Dubai Marina proximity, which can enhance yields for operators but introduces seasonality risk.

SUPPLY DYNAMICS AND PORTFOLIO POSITIONING

JLT's supply picture is characterised by a largely completed development programme — the 79-tower masterplan has been substantially delivered, and the active off-plan market within JLT itself is limited. New supply pressure on JLT comes primarily from neighbouring districts rather than from within the community, as competing mid-market communities launch new towers in areas like Business Bay, Dubai Science Park and Al Furjan that compete for the same tenant profile. The key supply consideration for JLT investors is building quality differentiation within the community: there is meaningful variation in finish quality, facilities management and tower positioning between JLT's 79 towers, and selecting the better-managed buildings in premium cluster positions materially affects both rental performance and capital value. Lake-facing units in well-managed buildings command the tightest yields — the demand for these units is most resilient — while peripheral or lower-quality towers can see higher vacancy rates and lower capital value growth.

JUMEIRAH LAKE TOWERS: INVESTMENT STRATEGY AND ENTRY POINTS

For yield-focused investors, the primary JLT entry strategy is the studio or 1-bedroom apartment in a well-managed building in a central cluster, acquired on the resale market at a pricing point that delivers 5.5–7 per cent gross yield. The key is building selection: JLT's range of tower quality means that a poorly selected building can underperform significantly. Investors should request service charge history and occupancy data before committing, and should prioritise buildings with professional facilities management companies rather than self-managed homeowner associations, as the former consistently deliver better maintenance and therefore better tenant retention. Lake-facing units carry the premium but also the most resilient demand — buying a lake view unit at a modest premium to non-lake inventory is generally a sound trade in the established JLT clusters.

For capital growth positioning, JLT offers a relative value argument against Dubai Marina. The Marina commands a meaningful premium per square foot for what is broadly comparable product — the waterfront view being the primary differentiator. As the Marina premium has compressed over time and JLT has matured as a community, the case for buying JLT on relative value has become more compelling. Investors who buy into well-positioned JLT towers at a 25–35 per cent discount to equivalent Marina product are effectively acquiring the same connectivity, amenity access and tenant quality at a lower entry point — and the historical gap compression supports the idea that this discount will continue to narrow over time as Dubai develops and more buyers focus on value fundamentals rather than address prestige.

A third strategy is the short-let operator play — JLT's metro access, walkable layout and Dubai Marina proximity make certain towers highly productive for managed short-term rentals, particularly studios and 1-bedroom apartments in lake-facing buildings with concierge support. Short-let gross yields in the better towers can reach 8–10 per cent, though this is operator-intensive work and exposes the asset to seasonality and platform regulation risk. For investors prepared to run short-let through a licensed operator, JLT represents one of Dubai's better-balanced short-let markets, sitting between the Marina short-let premium and the lower-tier short-let districts.

If you are considering Jumeirah Lake Towers, the key is not deciding whether the area works — it is selecting the right building within a community of 79 towers that varies enormously in quality, management and positioning. JLT works as an investment precisely because it has genuine demand drivers: metro access, DMCC employment base, competitive pricing versus Marina, and authentic community amenity. Do the building selection work before you do the area selection work, and you will find JLT one of the most reliable mid-market yield assets in Dubai's freehold portfolio, typically suiting portfolios at the AED 500,000–1,500,000 capital commitment level for studios and 1-bedrooms.

SUPPLY DYNAMICS

Nakheel master developer, multi-developer towers, 79-tower plan substantially delivered

TENANT PROFILE

DMCC corporate professionals, Marina-corridor employees, mid-market metro apartment renters

KEY RISK FACTORS

Building quality variance, service charge spread, Marina compression, corridor competition

KEY INFRASTRUCTURE

Jumeirah Lake Towers sits between Sheikh Zayed Road (E11) and Al Khail Road (E44) in new Dubai, with dual Red Line metro access via the DMCC and Sobha Realty stations bookending the district. The community is internally anchored by three artificial lakes, a lakeside promenade and pedestrian network connecting all clusters, 79 mixed-use towers housing ground-floor retail and F&B cores, the DMCC Authority headquarters serving 22,000+ registered free zone companies, schools, clinics, nurseries and daily-service outlets distributed across the cluster layout. Nearby external anchors include Dubai Marina, JBR, Ibn Battuta Mall, Mall of the Emirates, Dubai Internet City, Emirates Golf Club and Madinat Jumeirah. Adjacent communities include Dubai Marina, Emirates Living, The Greens, The Views and Jumeirah Islands, reinforcing JLT's positioning as Dubai's flagship metro-connected DMCC free zone apartment district.

Area fundamentals

ASSET PROFILE
DMCC mid-market yield cluster; Marina-adjacent value
INVESTOR PROFILE
Yield investor + Marina-relative value apartment buyer
TIER
Tier 2 – Yield & Volume
MARKET TYPE
Mid-market, apartments, high-rise, multi-developer
EST. POPULATION
~80,000–100,000
LAND SIZE
~21.5m sq ft

Next step

Request a briefing

You will get Jumeirah Lake Towers as a brief: the buildings on this page, the register readings behind them, and our view on each.
Sent with your enquiry:Jumeirah Lake Towerspurpose not statedbudget not statedno buildings on screenasked from: the brief

We come back with specifics, not a brochure. Stephen Mitchell · RERA BRN 68593 · in Dubai since 2007.

Location

Jumeirah Lake Towers, Dubai

Get Directions

Try it yourself

Investor Tools

Rental Yield Calculator

Model the gross and net return on a Dubai buy-to-let purchase. It covers service charges, void periods and acquisition costs.

All-in purchase price before transaction costs.

Total contracted rent for one year, before charges.

Community and building service charges, annualised.

5%

Your buffer for void periods. 5% is about 18 days empty a year — a month is 8%.

7%

7% is the 4% DLD transfer fee, 2% agency plus VAT, and DLD's flat registration lines. It excludes the developer NOC and any legal quote — see the Buying Costs Calculator for the full itemisation.

6% net

The net yield a deal has to clear to interest you. Sets the target line on the curve — it does not change the yield above it.

5.3%Net rental yield
Moderate yield
Gross yieldGross yield: 7.00%
Net annual incomeNet annual income: AED 84,750
Monthly net incomeMonthly net income: AED 7,063
Total cash investedTotal cash invested: AED 1,605,000

Against your 6% hurdle

Short of it
9.1%0%AED 975KAED 2.03M
Net yield (vertical) against the price you pay (horizontal), on the rent, charges and costs entered. The gold dot is your deal; the line across is your hurdle.
Price that clears it
AED 1,320,093AED 179,907 below your price — a 12.0% discount.
Rent that clears it
AED 117,158AED 12,158 a year more than you have entered, at this price.

Estimates for guidance only, assuming full-year occupancy net of the vacancy allowance above. Actual returns depend on financing, unit condition and market timing — speak to an advisor for a deal-specific model.

Email my results

We’ll send this summary — your figures and the results — to your inbox.

Next step

We'll hunt deals that meet or beat this yield hurdle

Send us this scenario and we'll go into the market against it — on-market and off — qualify what we find, and only come back with what clears your number.

Got questions?

Get Answers!
Continue reading

The closest area guides to this one, matched on subject.

Showing 4 of 101 Dubai area guides.

Browse all 101 area guides
Need help?