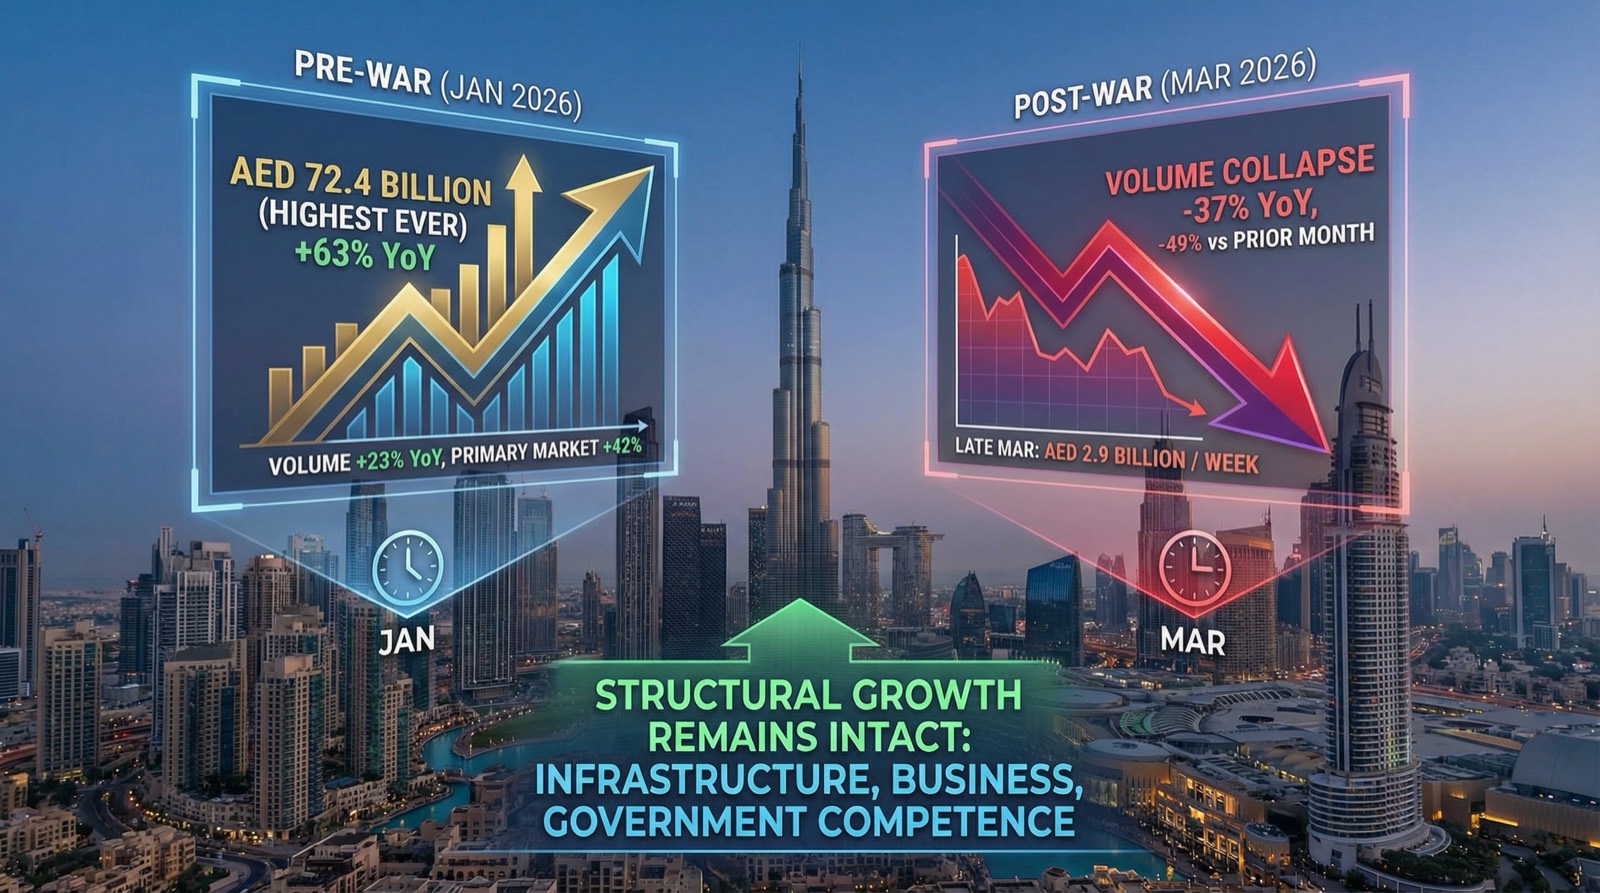
The past week showed clear developments across infrastructure, capital behaviour, and financial policy. The dominant themes are clear: prices have started to move lower, transaction volumes have slowed, and capital at the top end of the market remains active.
At the same time, policy responses on infrastructure and financial stability have become more visible and more direct.
If you’re reassessing your positioning in this market, I can show you where risk-adjusted opportunities are emerging. Click here to speak with me directly.
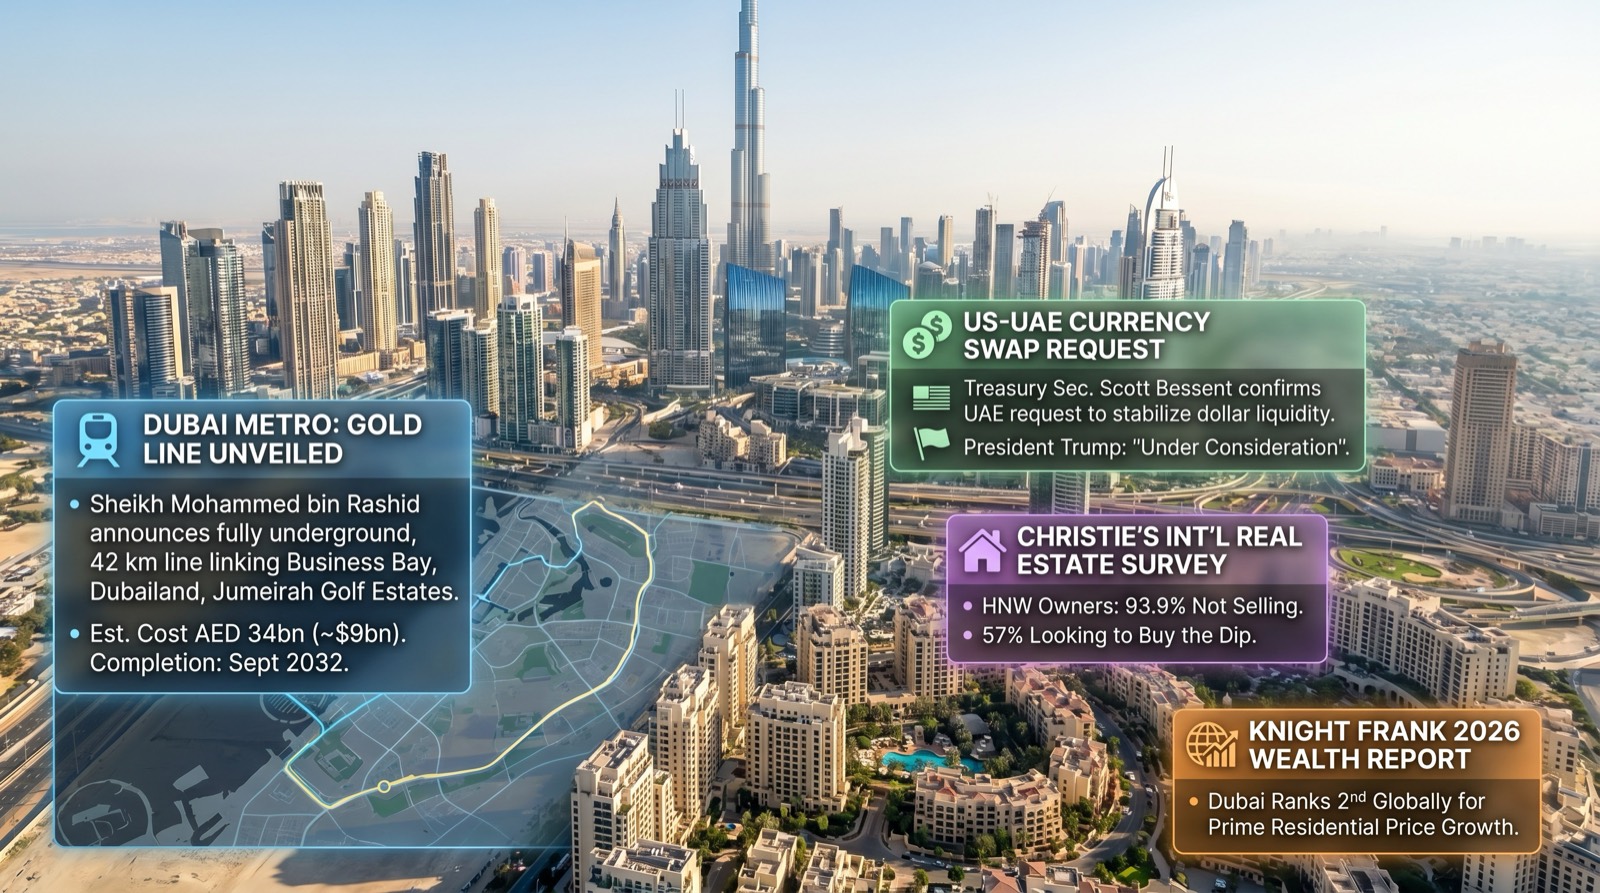
On Wednesday, Sheikh Mohammed bin Rashid unveiled the Gold Line — a fully underground, 42 km, AED 34bn (~$9bn) Dubai Metro line linking Business Bay, Dubailand and Jumeirah Golf Estates, scheduled for completion September 2032.
The project is framed by Dubai's leadership as economic stimulus following the Iran conflict, with Sheikh Mohammed stating "our future endeavours will not stop; rather, they will accelerate."
A day earlier, in Senate testimony, US Treasury Secretary Scott Bessent confirmed the UAE — alongside other Gulf and Asian allies — has formally requested a currency swap line to stabilise dollar liquidity. President Trump confirmed the same day that the swap is under consideration.
UAE officials have indicated a willingness to settle some oil receipts in Chinese yuan if dollar liquidity tightens further.
Taken together, these developments point to parallel action on infrastructure expansion and financial system stability.
- The dirham peg is being actively supported through coordination with Washington and alternative settlement mechanisms. AED-denominated property remains tied to that framework.
- The Gold Line is the most significant real estate value driver announced this week. The Business Bay → Dubailand → Jumeirah Golf Estates corridor should be viewed as a long-term infrastructure-led growth area.
One of this week’s key datasets came from Christie’s International Real Estate Dubai’s high-net-worth owner survey, conducted 6–17 April 2026:
- 93.9% of owners are not actively selling
- 57.1% are actively seeking or are open to discounted opportunities
- 57.2% would advise other market participants to acquire assets
- Respondents flagged ready properties as a stronger opportunity than off‑plan — a notable reversal of the dominant pattern since 2022
- Christie's found "no evidence of distressed selling behaviour, sudden sell‑offs, panic‑driven exits, or a meaningful shift in owners' pricing convictions"
Supply is not breaking; buyers are repositioning toward ready stock and waiting for motivated sellers who are not materialising at scale.
The opportunity is in identifying the 6.1% who are selling and the small minority of overleveraged off-plan resellers.
The 2026 Wealth Report by Knight Frank places Dubai second globally for prime residential price growth.
| Indicator | Data |
|---|---|
| Dubai prime price growth, 12 months | +25.1% |
| Dubai prime price growth, 5 years | +193.9% |
| Transactions above $10m, 2021 | 113 |
| Transactions above $10m, 2025 | 500 |
| UAE $30m+ wealth population, 2026 | 4,851 |
| UAE $30m+ wealth population, 2031 (forecast) | 6,588 |
| Middle East prime price growth average, 2025 | +9.4% |
Pre-war demand at the top end has not unwound; it has carried through into current conditions. Transaction volumes and wealth inflows remain elevated.
Exposure remains concentrated in ultra-prime and prime branded assets, where buyer depth and pricing resilience are strongest.
Source: Knight Frank
DMCC launched two new office towers this week in Uptown Dubai:
- 560,000+ sq ft office space
- 82,000 sq ft retail
- Completion scheduled for Q1 2028
Despite new supply entering the pipeline, the market continues to report:
- Limited availability of Grade A office space
- Strong demand from financial and technology occupiers
Building at this scale requires long-term capital commitment. The decision to proceed under current conditions reflects expectations of sustained occupier demand.
Explore curated office and retail opportunities at Mitchell’s Commercial Realty.
This week included a notable acquisition, with Indian investor Tiger Shroff purchasing a waterfront unit in Dubai Maritime City.
This matters because Indian investors represent one of the largest sources of cross-border demand into Dubai property.
While some short-term repatriation has been reported, this transaction confirms that the broader channel remains active.
Still reading
Need expert help on this subject?
In Abu Dhabi, Aldar reported two significant data points:
- Acquisition of a fully leased Masdar City asset for AED 654 million
- Sales exceeding AED 800 million at a Yas Island development
The Yas Island sales also provide a clear breakdown of the buyer profile:
| Buyer Characteristic | Share |
|---|---|
| International / expat | 54% |
| UAE national | 46% |
| New to Aldar | 83% |
| Under 45 years old | 66% |
This indicates continued inflow of new capital, with a younger and more international buyer base entering the market.
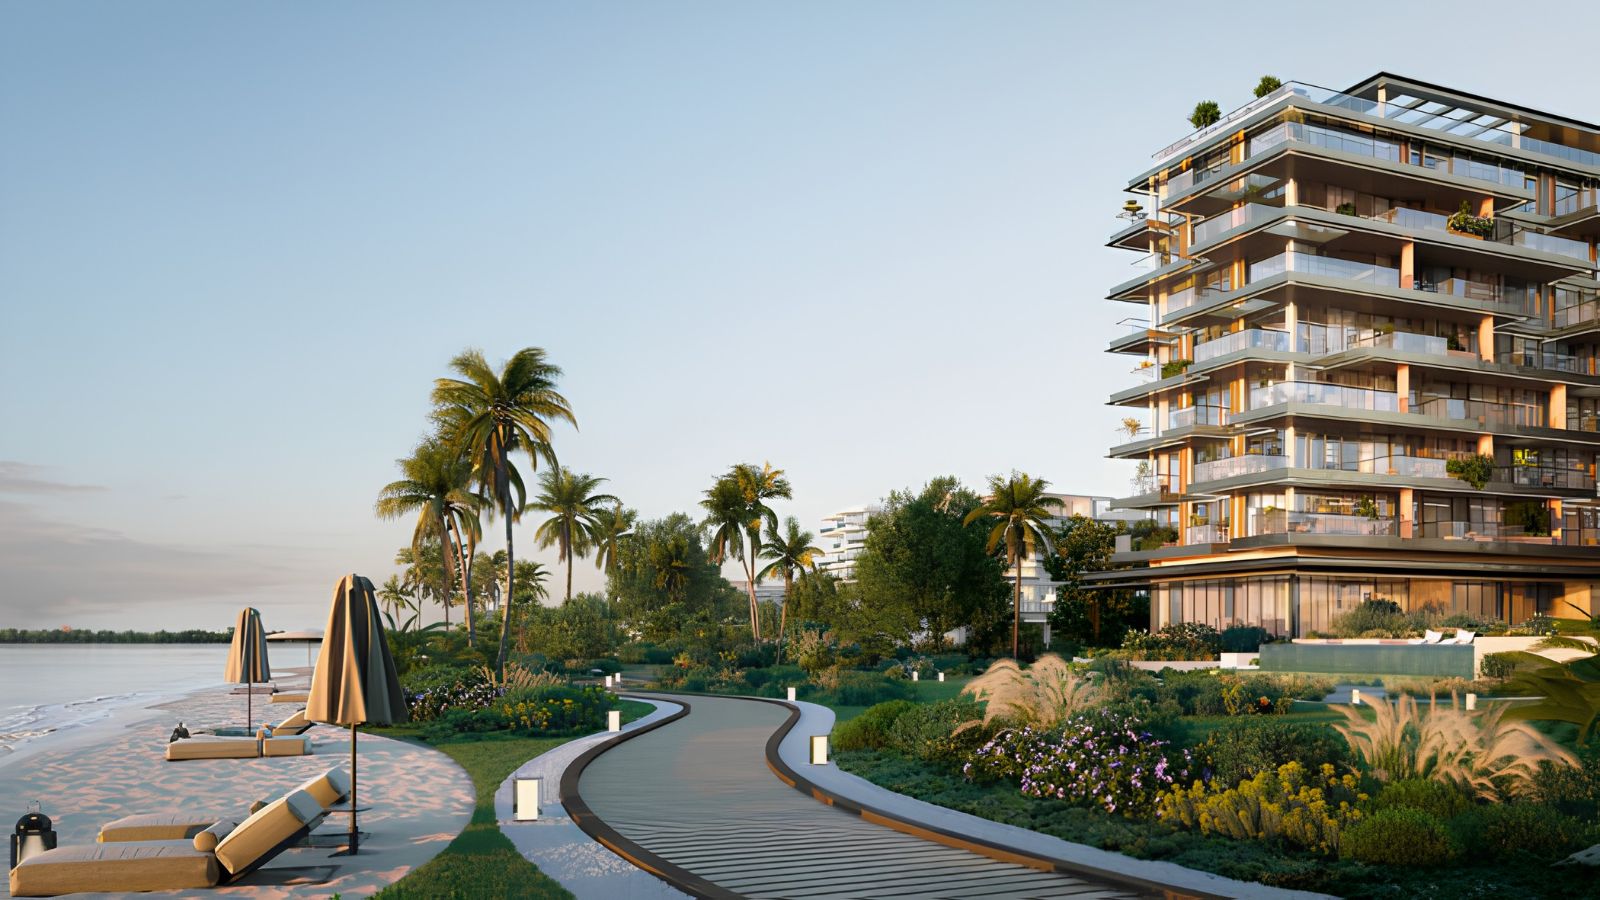
Cheval Collection announced a 99-unit branded residence project at Dubai Islands, scheduled for completion in 2029.
Branded stock continues to trade at a 25–35% premium over equivalent unbranded inventory and remains the most defensible yield positioning in a softer rental market.
Cavendish Maxwell published its 2025 RAK report on 23 April. RAK is now where Dubai was around 2014, with a known catalyst on the horizon:
- AED 12.4bn in residential sales, 6,600 transactions in 2025
- Off‑plan share: 85%
- Sales volumes ‑24% YoY (off‑plan ‑17.2%, ready ‑18.7%) — driven by fewer launches, not weaker demand
- Apartment prices +13.4%, villa prices ~+10%, rents +8.7% to +10.2%
- Pipeline: 1,300 units in 2026, 1,900 in 2027, 5,200 in 2028 — 8,400 total
- Wynn Al Marjan Island (the integrated casino resort) opens spring 2027 — single largest demand catalyst on the GCC tourism calendar
Source: Cavendish Maxwell
For Dubai investors, RAK is primarily a catalyst-driven opportunity linked to the Wynn opening, but it does not yet offer the same regulatory depth or institutional infrastructure as Dubai.
In closing
Final View for Dubai Property Investors
The past week confirms a market adjusting in real time rather than breaking.
Pricing has started to soften and transaction volumes have slowed, but the underlying structure remains intact.
High-net-worth owners are holding, institutional capital continues to deploy, and infrastructure and financial policy responses are being executed simultaneously.
The result is a narrower, more selective market. Activity has not stopped — it has concentrated around quality assets, proven locations, and capital with conviction.
Next step
Let’s Talk
If you’d like to unpack where the most resilient opportunities are emerging — in stabilised residential areas or income-generating commercial zones — I’d be happy to share a focused, data-driven shortlist based on your investment goals.
📞 No pressure, no sales pitch—just a focused, informed conversation about your investment goals.
Published 27 April 2026 by Stephen James Mitchell MBA. Market figures quoted reflect the data available at that date.