DUBAI STUDIO CITY: TECOM MEDIA FREE ZONE APARTMENT YIELD COMMUNITY
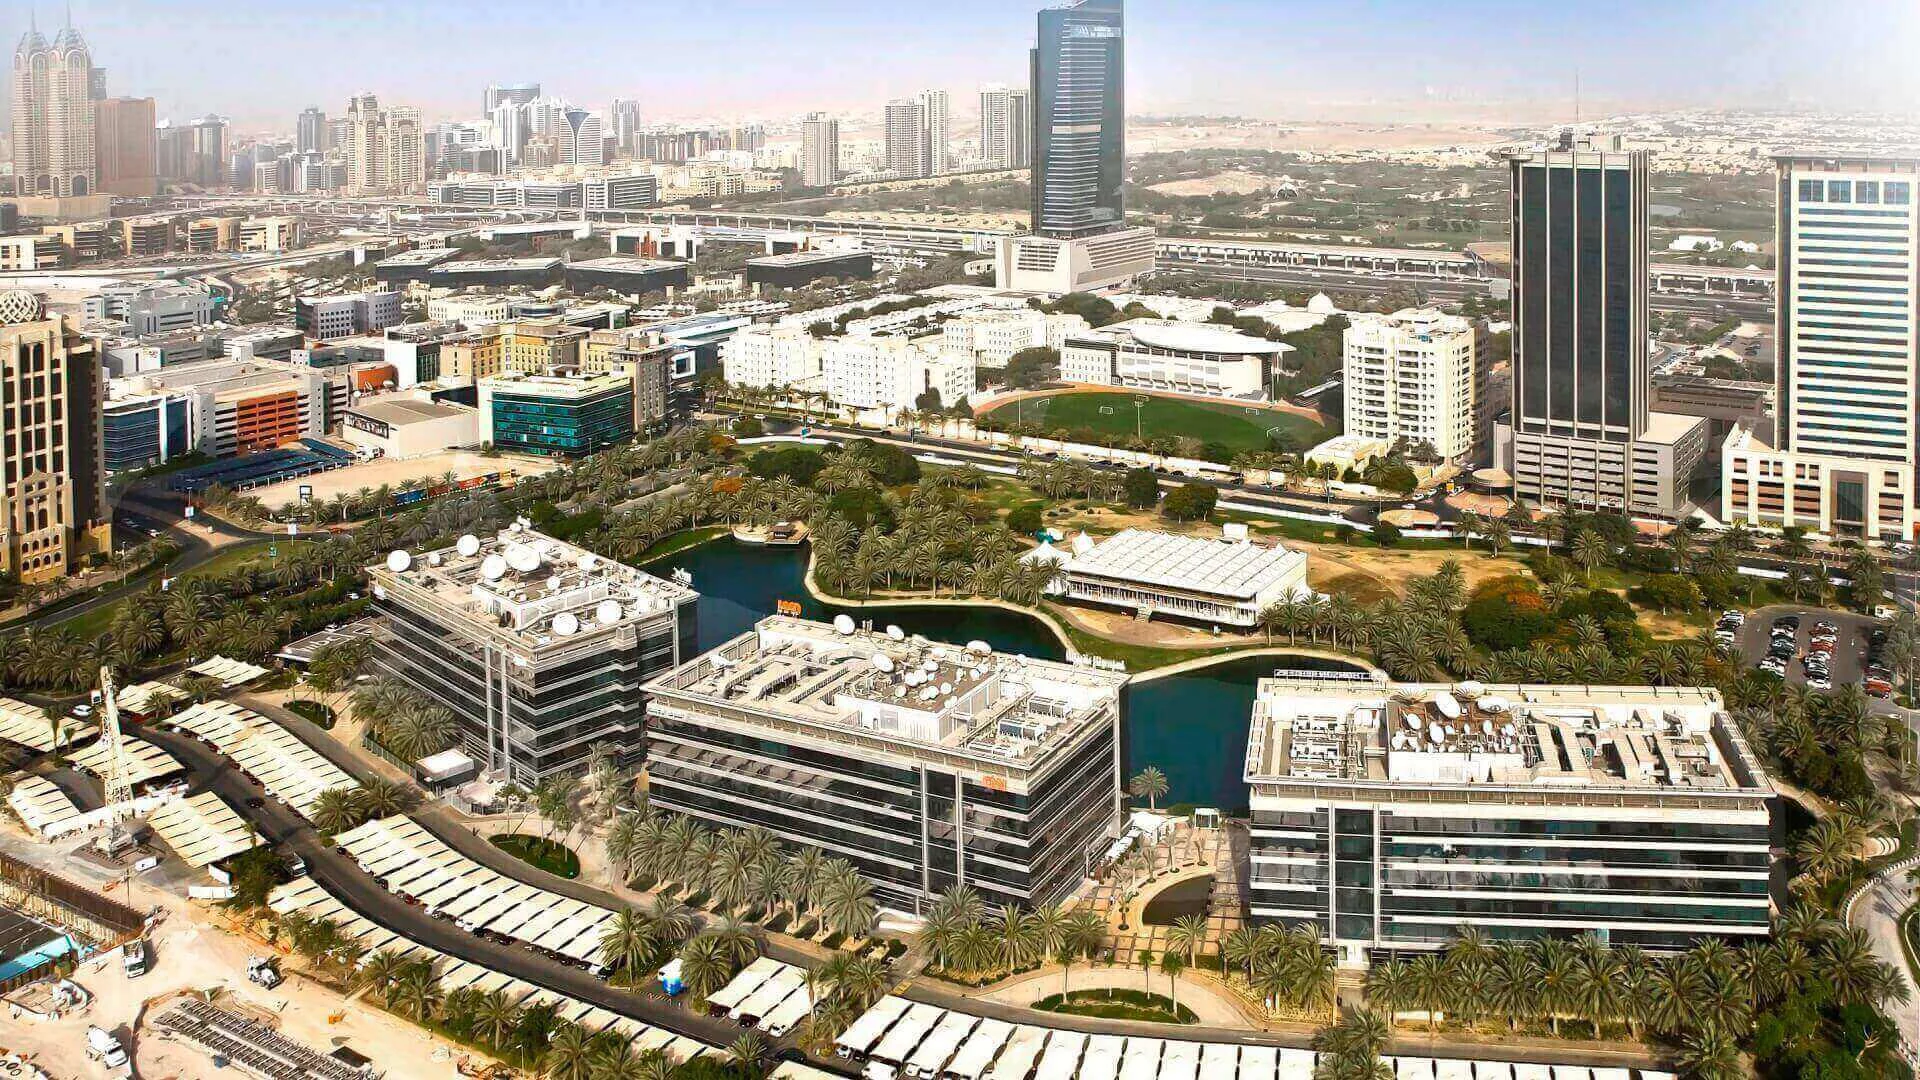
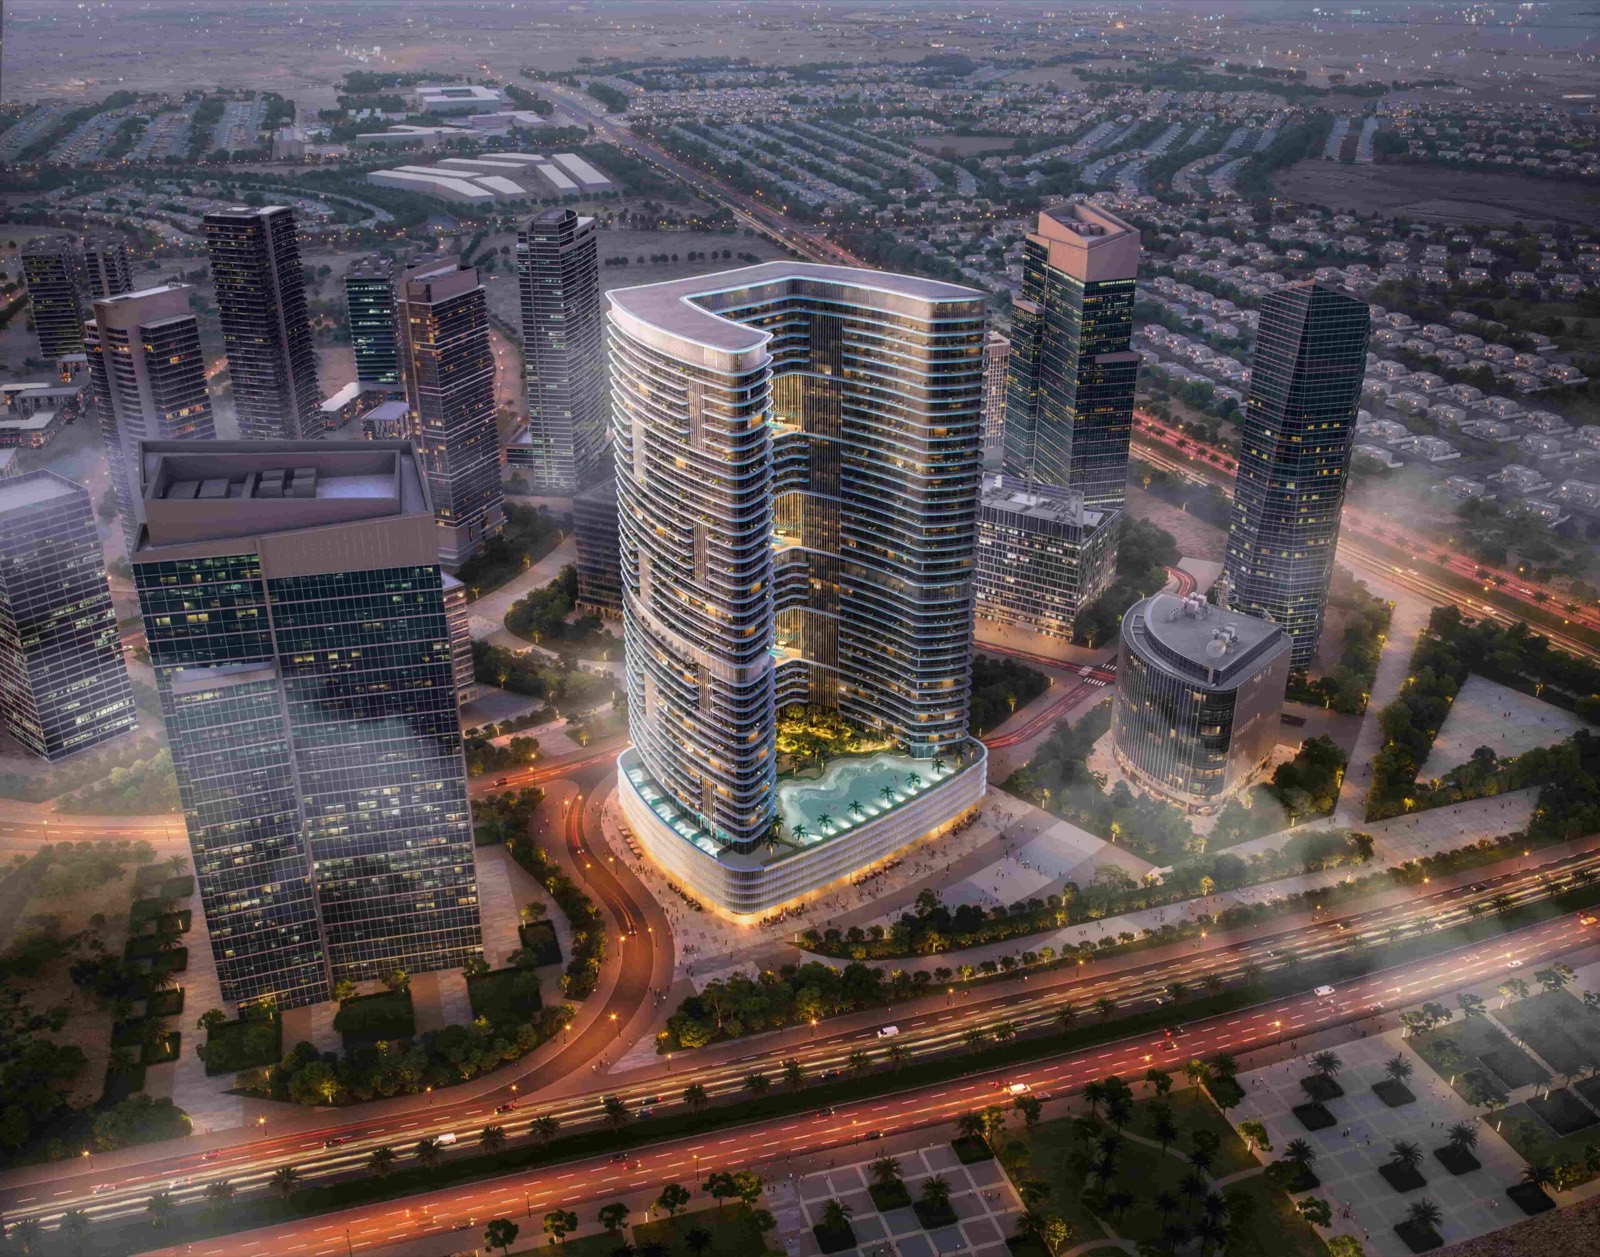
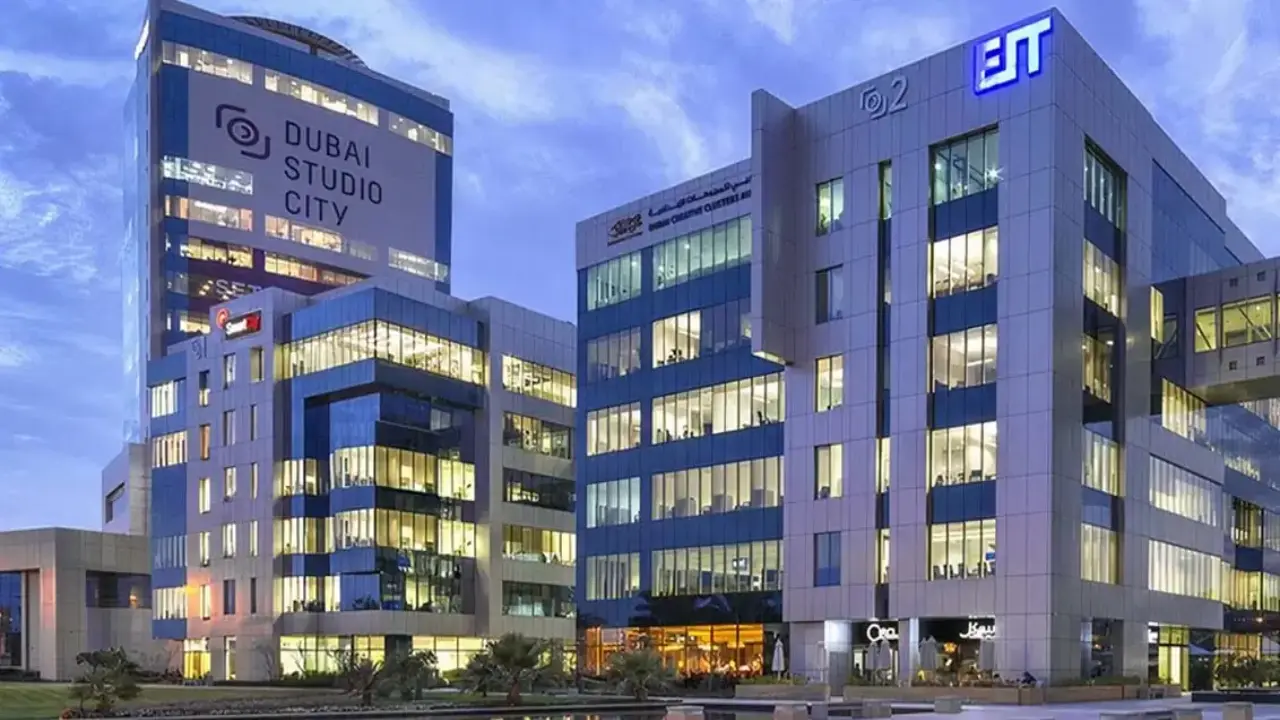
The masterplan spans approximately 22 million square feet and comprises 45 building developments delivering over 6,200 residential units, 70 buildings, 78 villas and 271 commercial units on the Dubai Land Department record. Like Dubai Media City and Dubai Internet City, Dubai Studio City sits under TECOM Investments — a subsidiary of Dubai Holding — which gives the community the same government-backed free-zone employer anchor that underpins the sister communities. Phase one construction began in June 2007, delivering sound stages, studio offices and amphitheatres that host regional and international film and television production.
For investors, Dubai Studio City is a Tier 2 Yield & Volume play with one of the highest published apartment-ROI profiles in Dubai. Bayut's twelve-month ROI averages show studios at 8.56 per cent, 1-bedroom units at 7.88 per cent, 3-bedroom at 7.14 per cent and 2-bedroom at 6.12 per cent gross — a yield profile comparable to International City and higher than most Dubailand apartment communities. Recent DLD pre-registration sales in February 2026 show studios at Ryah Living by Alyakka trading at AED 1,578–1,744 per sqft (AED 625,000–655,000) and 1-bed units at AED 1,135,000 at Laya Courtyard-B (AED 1,686 per sqft). Ready-stock Azizi Mirage 1 studios closed at AED 499,000 (AED 1,404 per sqft) in the same month. The entry-point is materially lower than apartment stock in Dubai Marina, JLT or Business Bay at broadly similar yield levels.
The investment case rests on three structural pillars. First, captive tenant demand from the TECOM media and film production sector — broadcasting companies, TV studios, music labels and entertainment service firms anchor the free zone and generate recurring rental demand from their staff. Second, the continuous multi-developer off-plan pipeline (Azizi, Samana, QUBE Development, Prescott, Alyakka) maintains supply momentum and allows yield investors to enter at successive launches with graduated pricing. Third, the adjacency to Motor City, DAMAC Hills, Arabian Ranches and Arabian Ranches 2 means tenants benefit from the Dubailand leisure cluster while paying apartment rents rather than villa rents, which protects occupancy and rental-rate resilience across economic cycles.
Classified as Tier 2 — Yield & Volume, Dubai Studio City serves yield-focused investors prioritising studio and 1-bedroom apartment cashflow with TECOM media-sector tenant demand and multi-developer supply dynamics. This guide covers the acquisition strategy for yield-focused apartment investors, the due diligence framework across 45 buildings with variable developer quality and service-charge discipline, the rental yield dynamics supported by the captive free-zone tenant base, and the portfolio construction role of Dubai Studio City as a high-yield Dubailand apartment contributor within a balanced Dubai residential portfolio. Building-level selection is central to return optimisation given the observed quality variance between Azizi, Samana, QUBE and early-phase Glitz stock. Long-term holders with 5 to 10 year horizons will find Dubai Studio City one of the most yield-accretive TECOM free-zone positions in southern Dubai.
DUBAI STUDIO CITY: MARKET ANALYSIS AND INVESTMENT DYNAMICS
INFRASTRUCTURE AND CONNECTIVITY
Dubai Studio City sits along Sheikh Mohammed Bin Zayed Road (E311) and Al Qudra Road (D63) with access to the rest of Dubai via the Hessa Street and Al Khail Road connections. There is no direct metro; the community is car-dependent with RTA bus links reaching the wider network. Internal amenities include the Studio One Hotel (with six F&B outlets including The Irish Village, The Maine Street Eatery, Rags to Riches and El Chapo's Tacos), Olivara Residences, Glitz 1–3 retail, Studio City Park 1 (0.2 km) and Park 2 (0.4 km), Eastlands Park (0.5 km), plus 28 daily-service outlets including supermarkets, gyms, salons, a butcher, pharmacy and mini-mart. Nearby anchors include First Avenue Mall at Motor City, City Centre Me'aisem at Dubai Production City, Arabian Ranches Golf Club (2.0 km), Trump International Golf Club (1.9 km), The Els Golf Club (4.0 km) and Dubai Miracle Garden (2.1 km). Schools include GEMS Metropole Motor City (0.7 km, British), Dhruv Global School (2.4 km) and the IB-curriculum Dwight School Dubai (2.5 km, AED 91,500).
RENTAL MARKET AND TENANT PROFILE
Published Bayut ROI sits at 8.56 per cent for studios, 7.88 per cent for 1-bed, 6.12 per cent for 2-bed and 7.14 per cent for 3-bed gross — among the highest apartment yields in Dubai. Azizi Beach Oasis (Mirage 1) studios rent at AED 41,000–72,000 and 1-beds at AED 60,000–85,000, while sale prices sit at AED 530,000–964,000 for studios and AED 849,000–1 million for 1-beds. Azizi Beach Oasis 2 1-beds list at AED 820,000–1 million and 2-beds at AED 1–2 million. The tenant base is dominated by TECOM free-zone workers in broadcasting, film production, TV, music and post-production, supplemented by Motor City, Dubai Sports City and Arjan-area staff seeking affordable apartment living within 20 minutes of the Marina and 18 minutes of Palm Jumeirah. Short-to-medium tenancies dominate rather than multi-year family leases.
SUPPLY DYNAMICS AND PORTFOLIO POSITIONING
Dubai Studio City has a continuous multi-developer off-plan pipeline with 45 tracked building developments. Active construction includes Azizi Beach Oasis 2, Samana Mykonos, Verano by Prescott, Arisha Terraces, Divine Residencia and Laya Courtyard, while Azizi Vista, Azizi Beach Oasis and Samana Santorini have recently completed handover. Recent DLD Q1 2026 activity confirms strong absorption: pre-registration sales at Ryah Living by Alyakka (AED 1,578–1,744 per sqft), Laya Courtyard-B (AED 1,686 per sqft) and The First Collection hotel rooms at premium hospitality PSF. Within a diversified Dubai portfolio, Dubai Studio City occupies the high-yield Dubailand apartment allocation alongside Dubai Production City, Arjan and International City, pairing well with capital-preservation villa positions in The Meadows or Arabian Ranches for balanced yield-and-growth exposure. Position sizing is typically two to four studios or 1-bed units given the AED 500,000–1 million ticket range.
DUBAI STUDIO CITY: INVESTMENT STRATEGY AND ENTRY POINTS
The first strategic decision is building-level selection. Dubai Studio City has 45 tracked building developments across multiple sub-developers (Azizi, Samana, QUBE Development, Prescott, Alyakka, Abou Eid Real Estate) with materially different build quality, service-charge discipline, management standards and resale liquidity. Azizi Beach Oasis (Mirage 1) and Azizi Beach Oasis 2 are Bayut's most-searched buildings and carry the developer-brand premium, while early-phase Glitz 1–3 stock offers accessible entry at discounted PSF but requires refurbishment due diligence on 10-to-15-year-old units. New Samana Santorini, Samana Mykonos and Azizi Vista buildings deliver modern specification with full amenity packages. Off-plan Ryah Living and Laya Courtyard at AED 1,578–1,744 per sqft reflect current developer launch pricing — significantly higher than 2015-era Azizi Mirage secondary market at AED 1,404 per sqft. Building selection within the community is therefore the single most important investment decision.
The second strategic decision is studio-versus-1-bed allocation. Studios at AED 500,000–700,000 entry (AED 1,400–1,700 per sqft) generate the highest gross yields at 8.56 per cent on 2-beds average — the yield-maximising entry point within the community. 1-bedroom units at AED 820,000–1.1 million (AED 1,388–1,686 per sqft) at 7.88 per cent yield target a slightly broader tenant pool including young professional couples and junior free-zone executives. 2-bedroom units at AED 1–2 million at 6.12 per cent yield appeal to small family renters but compress returns relative to the studio-and-1-bed sweet spot. A pure yield strategy targets studios and 1-beds in Azizi or Samana buildings; a blended yield-plus-growth strategy pairs one studio with one 1-bed across two different sub-developers.
The third strategic decision is timing and off-plan versus ready stock. Off-plan acquisitions at current developer launches (Ryah Living, Laya Courtyard, Arisha Terraces, Verano by Prescott) carry handover risk and 2-to-4-year capital lockup but offer payment-plan flexibility and launch-price positioning. Ready resale stock at Azizi Mirage, Azizi Vista or completed Samana buildings offers immediate rental income from day one but requires higher upfront capital (100 per cent instead of phased). For yield-focused investors with committed capital, ready-stock acquisition is the faster route to cashflow; for capital-growth-oriented investors willing to ride the launch-to-handover cycle, off-plan offers the pricing arbitrage.
The risk framework is explicit. No metro access is permanent and structural; the community relies on car transport and RTA buses. Continuous off-plan supply from multiple sub-developers caps rental-rate growth and requires careful building selection to avoid service-charge inflation and management-quality decline. Media-sector tenant concentration creates employment-risk exposure should the TECOM free zone contract. Meaningful portfolio exposure to Dubai Studio City typically requires AED 1 million and above of committed capital for a studio-plus-1-bed pairing, scaling to AED 3–5 million for a diversified 4-to-6-unit building-portfolio position, making it most appropriate for yield-focused apartment investors with a 5-to-7-year horizon.
SUPPLY DYNAMICS
TECOM master developer, multi-developer sub-projects, 45 buildings, continuous off-plan launches
TENANT PROFILE
Media and film professionals, young free zone workers, budget-conscious singles and couples
KEY RISK FACTORS
No metro, car-dependent, continuous off-plan supply, media-sector tenant concentration
KEY INFRASTRUCTURE
Dubai Studio City sits in DubaiLand, with access via Sheikh Mohammed Bin Zayed Road (E311) and Al Qudra Road (D63) connecting to Motor City, DAMAC Hills, Arabian Ranches and the wider Dubailand corridor. The community is internally anchored by the Studio One Hotel with The Irish Village, Rags to Riches and El Chapo's Tacos, Olivara Residences, Glitz 1–3 retail and 28 daily-service outlets including supermarkets, gyms, salons, pharmacy and F&B. Nearby anchors include First Avenue Mall at Motor City, City Centre Me'aisem at Dubai Production City, Dubai Miracle Garden, Global Village, Arabian Ranches Golf Club and Trump International Golf Club. Schools include GEMS Metropole Motor City, Dhruv Global School, Ranches Primary and the IB-curriculum Dwight School Dubai at Sports City. Adjacent communities include Motor City, DAMAC Hills, Arabian Ranches 2 and Sports City. No direct metro; car-dependent with RTA bus access.
Area fundamentals
- ASSET PROFILE
- TECOM media free zone apartment yield community
- INVESTOR PROFILE
- Yield-focused studio and 1-bed apartment investor
- TIER
- Tier 2 – Yield & Volume
- MARKET TYPE
- Mid-market, apartments, media free zone, multi-developer
- EST. POPULATION
- ~15,000–25,000
- LAND SIZE
- ~22m sq ft
Next step
Request a briefing
You will get Dubai Studio City as a brief: the buildings on this page, the register readings behind them, and our view on each.