Palm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,148/sqftDowntown Dubai AED 2,920/sqftDubai Islands AED 2,769/sqftDubai Creek Harbour AED 2,564/sqftBusiness Bay AED 2,511/sqftDubai Marina AED 2,484/sqftDubai Hills Estate AED 2,446/sqftJumeirah Lakes Towers AED 2,304/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,048/sqftJumeirah Village Triangle AED 1,664/sqftDubai South AED 1,651/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,492/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm Jumeirah AED 3,558/sqftDubai Maritime City AED 3,148/sqftDowntown Dubai AED 2,920/sqftDubai Islands AED 2,769/sqftDubai Creek Harbour AED 2,564/sqftBusiness Bay AED 2,511/sqftDubai Marina AED 2,484/sqftDubai Hills Estate AED 2,446/sqftJumeirah Lakes Towers AED 2,304/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,048/sqftJumeirah Village Triangle AED 1,664/sqftDubai South AED 1,651/sqftArjan AED 1,588/sqftJumeirah Village Circle AED 1,492/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO OCT 2026
Dubai Production City, Dubai — area guide

Area guide · Dubai

Dubai Production City Investment Guide

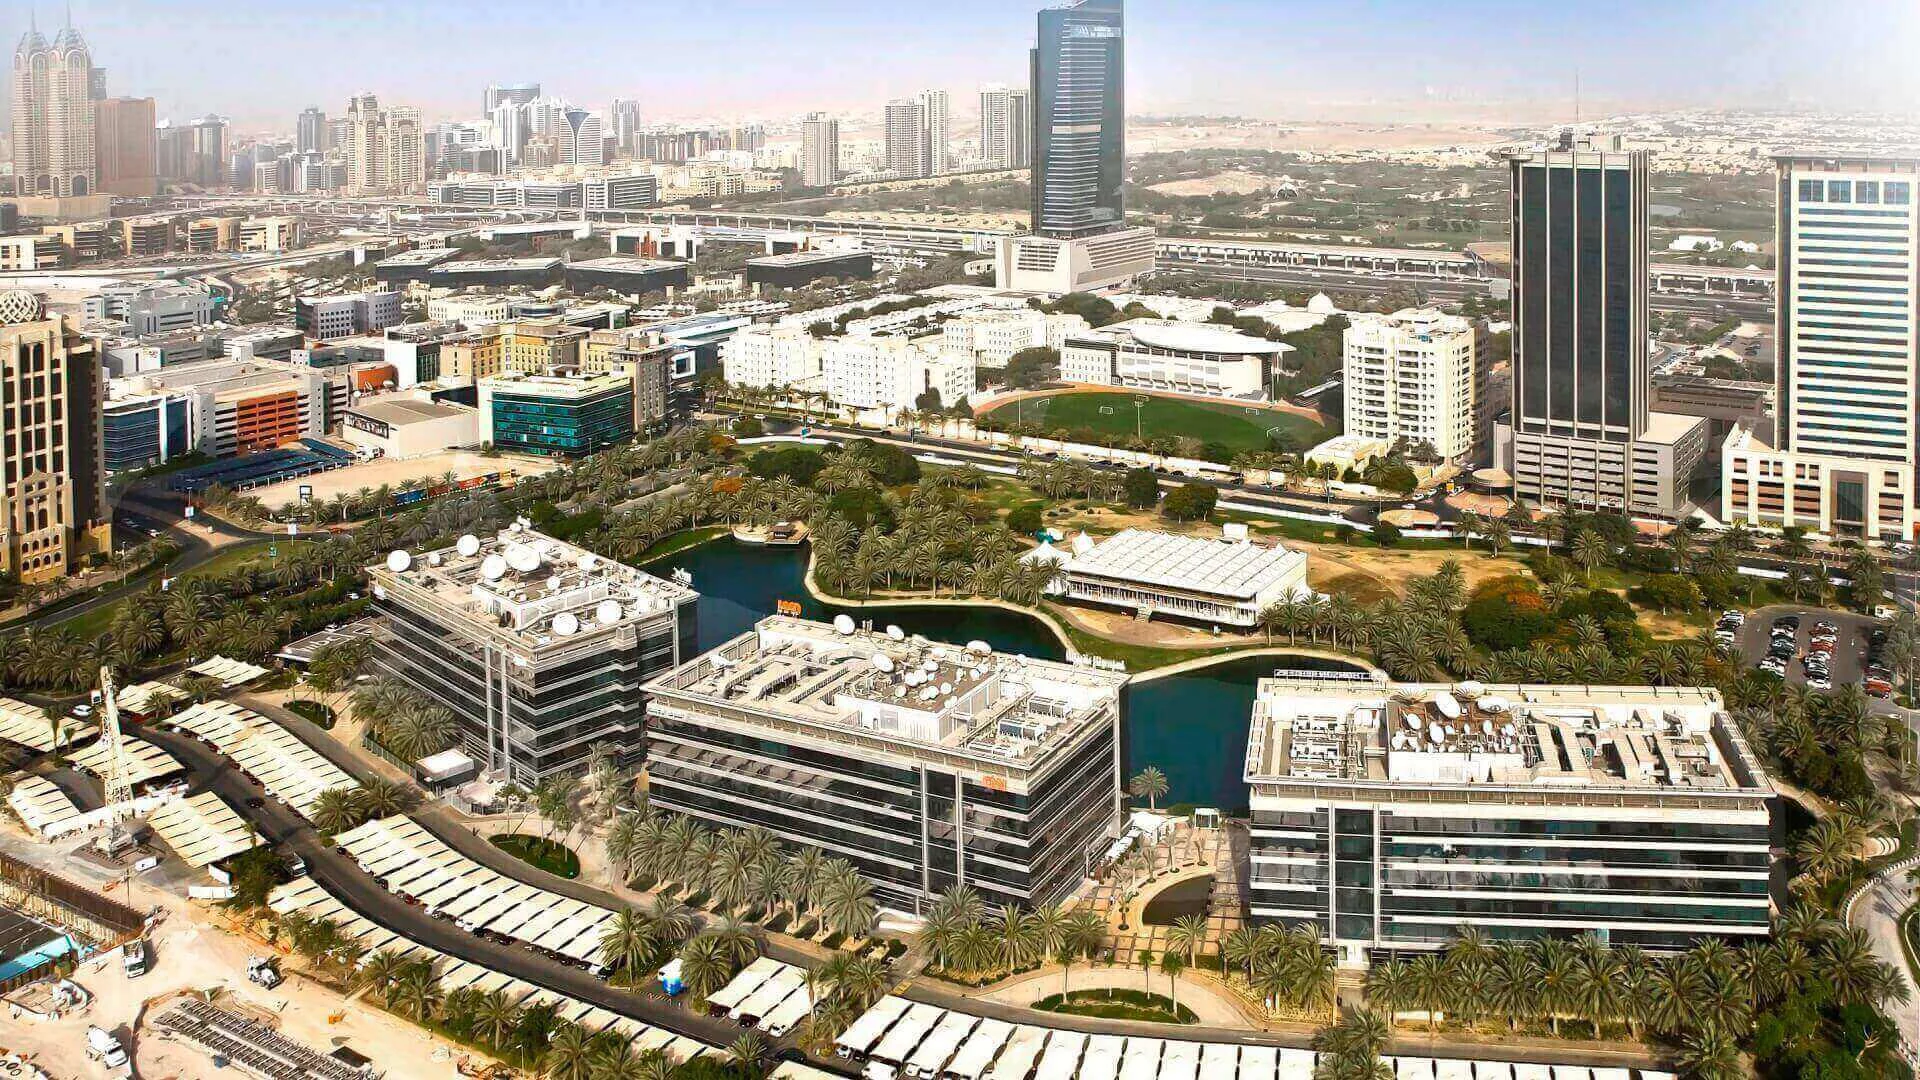
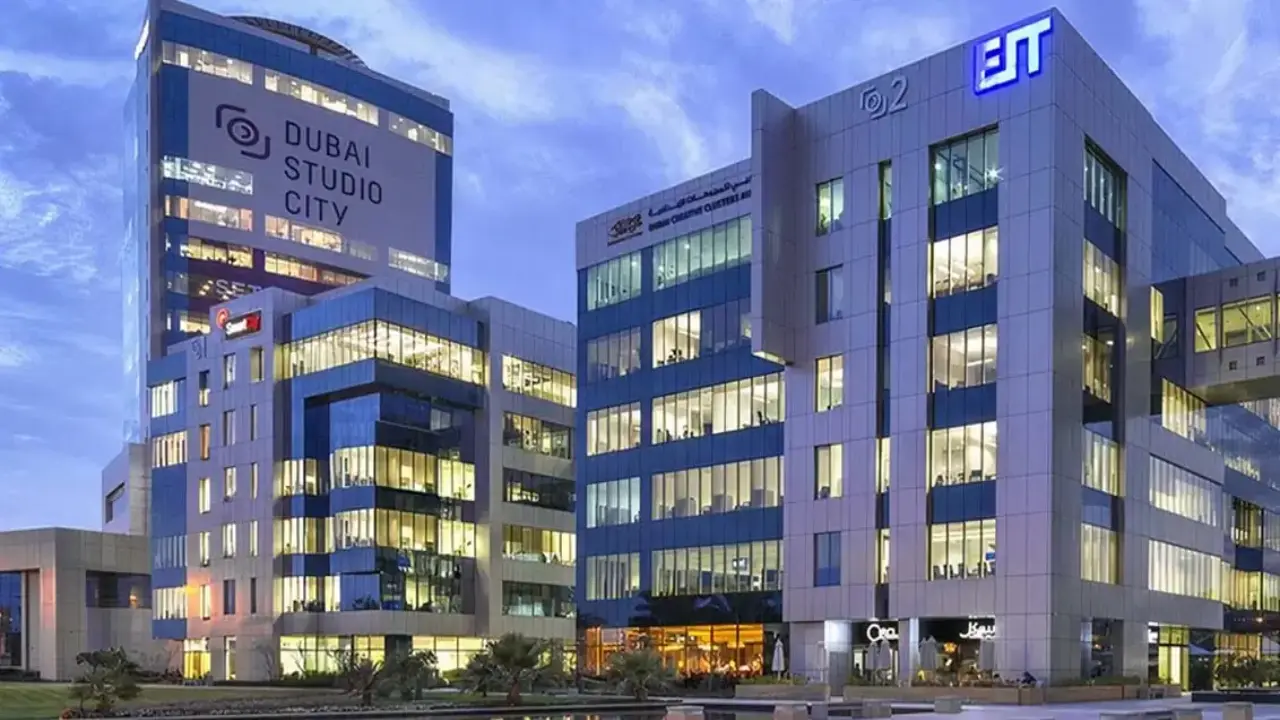
Dubai Production City, formerly the International Media Production Zone (IMPZ) and also known as DPC, is a TECOM Group mixed-use free zone and residential community within Me'aisem First, DubaiLand.

I want to
Budget

Answer the two questions and this page reorders itself around them. Nothing is sent until you ask for something.

Sales prices

350–550AED/sqft, 2003
Launch price
Developer launch pricing when the community came to market, from this guide. Historic — not a current valuation.

A building can sit well under the area figure. Tell us which one you have in mind and we will read its own register history back to you.

Rental rates

AED 49,350a year
Median annual rent
Ejari — 13,874 registered contracts in the 24 months to 1 October 2026. Me'Aisem First, the register's name for Jumeirah Golf.
AED 80.6per sq ft a year
Median rent per sq ft
Same contracts, same window.
~6–7.5%
Gross yield band
Mitchell’s own range for Dubai Production City, from this guide — an assessment, not a register figure.

The register gives one rent figure for the area. What a specific building lets for, and how quickly, is the question worth asking before you buy for income.

Ready buildings with recent sales

Median registered price per bedroom type. Hotel rooms and serviced units are left out where the register marks them.

BuildingUnitMedian priceMedian sq ftAED/sqftSales
LAKESIDE
The Waves FZ-LLC · completed 2014 · 170 registered sales
StudioAED 390,0003671,055128
1 bedAED 582,50067783942
THE CRESCENT
DAMAC Properties Co (L.L.C) · completed 2008 · 73 registered sales
StudioAED 420,00049984258
1 bedAED 745,0001,1776331
2 bedAED 927,5001,31270014
LAGO VISTA
DAMAC Properties Co (L.L.C) · completed 2011 · 70 registered sales
StudioAED 425,00049685736
1 bedAED 730,0009907375
2 bedAED 925,0001,37767629
MIDTOWN - MESK
Deyaar Development (P.J.S.C) · completed 2022 · 60 registered sales
StudioAED 800,0007881,0151
1 bedAED 1m7881,25413
2 bedAED 1.47m1,1651,25244
3 bedAED 2.18m1,8041,2102
MIDTOWN - AFNAN
Deyaar Development (P.J.S.C) · completed 2019 · 57 registered sales
StudioAED 530,0004331,2187
1 bedAED 815,2296421,21337
2 bedAED 1.3m1,0831,23012
3 bedAED 2m1,6701,1981
CENTRIUM TOWER
ETA Star Property Developers L.L.C · completed 2013 · 52 registered sales
1 bedAED 620,00071586517
2 bedAED 820,00096083424
3 bedAED 1.2m1,36183611
MIDTOWN - NOOR
Deyaar Development (P.J.S.C) · completed 2023 · 49 registered sales
StudioAED 620,0004341,4097
1 bedAED 911,0006571,36634
2 bedAED 1.54m1,1641,3066
3 bedAED 2.23m1,8041,2332
MIDTOWN - DANIA
Deyaar Development (P.J.S.C) · completed 2020 · 46 registered sales
StudioAED 562,7754331,30912
1 bedAED 795,0006541,24721
2 bedAED 1.35m1,0781,25913
QASR SABAH I, II, III
RS Realty FZ - L.L.C · completed 2015 · 40 registered sales
1 bedAED 433,25660271440
OAKWOOD RESIDENCY
Deyaar Development (P.J.S.C) · completed 2012 · 22 registered sales
1 bedAED 642,50089475418
2 bedAED 912,5001,6216494
JANNAT
Deyaar Development (P.J.S.C) · 18 registered sales
StudioAED 615,0003801,61316
1 bedAED 978,4497791,28119
2 bedAED 1.5m1,1821,28725
Viera Residences
Vantage Ventures Real Estate Development L.L.C · completed 2025 · 18 registered sales
StudioAED 534,5003951,3552
1 bedAED 1.09m7981,36044
2 bedAED 1.53m1,1521,29329
MYKA Residence
Myka Luxe Real Estate Development L.L.C · 12 registered sales
StudioAED 637,5004421,4424
1 bedAED 1.1m9261,2327
2 bedAED 1.63m1,1751,3831

DLD register — sales of units registered 28 April 2025 to 5 October 2026, duplicates removed. The sale count is the building’s registered sales of completed property.

How this table is built

Buildings with ten or more registered sales of completed property in the window are listed by default; the rest are behind “Show all buildings”. Hotel rooms and serviced units are left out where the register marks them. “Completed property” is the register’s own registration type, which does not separate an owner’s resale from a developer’s first sale of a finished unit, so neither do we. Bedroom medians are over the building’s registered sales in the window and are shown only where at least five sales of that type. AED/sqft on a row is the register’s median rate for that type, or median price over median size where it publishes none.

Two towers in the same block can sit points apart on net yield once service charges and occupancy are counted. Name the buildings and we will tell you which side of that line each one sits.

Under construction now

Projects the register records as under construction here, with the registered sales behind each figure; a project with fewer than ten is marked as a small sample. Hotel rooms and serviced units are left out where the register marks them.

ProjectCompleteMedian AED/sqftSalesMedian price by unit
Binghatti Elite
Binghatti Developers FZE · register end date Jun 2026
Project brief
53.3%
at 20 Apr 2026
1,655553Studio AED 736,250 · 1 bed AED 1.19m
+15.9% Q2 2025 → Q3 2026
Samana Resorts
Samana International Real Estate Development L.L.C · register end date May 2028
Project brief
5.9%
at 23 Jun 2026
1,436436Studio AED 721,000 · 1 bed AED 1.17m · 2 bed AED 1.49m
-6.7% Q2 2025 → Q1 2026
ELM AT PARK FIVE
Deyaar Development (P.J.S.C) · register end date Jun 2027
16.2%
at 3 Sep 2026
1,354343Studio AED 663,779 · 1 bed AED 1.03m · 2 bed AED 1.45m
-3.3% Q2 2025 → Q1 2026
Samana Sky Views
Samana World Real Estate Development L.L.C · register end date Jul 2028
2.2%
at 16 Jun 2026
1,525322Studio AED 727,000 · 1 bed AED 1.12m · 2 bed AED 1.49m
+2.8% Q3 2025 → Q1 2026
Reef 996
REEF Luxury Development L.L.C · register end date Sep 2028
0.1%
at 1 Sep 2026
1,647144Studio AED 719,513 · 1 bed AED 1.16m · 2 bed AED 1.57m · 3 bed AED 2.11m (3 sales)
+3.5% Q1 2026 → Q3 2026
EMBER AT PARK FIVE
Deyaar Development (P.J.S.C) · register end date Jun 2027
18.2%
at 17 Sep 2026
1,330137Studio AED 634,244 · 1 bed AED 1.07m · 2 bed AED 1.43m · 3 bed AED 2.37m
+6.2% Q3 2025 → Q1 2026
IVY AT PARK FIVE
Deyaar Development (P.J.S.C) · register end date Dec 2027
6.3%
at 17 Sep 2026
1,456127Studio AED 740,471 · 1 bed AED 1.15m · 2 bed AED 1.68m
Soul by vision
Vision Platinum Real Estate Development L.L.C · register end date Dec 2026
62.1%
at 17 Jul 2026
1,153119Studio AED 608,500 · 1 bed AED 939,500 · 2 bed AED 1.51m · 3 bed AED 1.88m
+3.9% Q3 2025 → Q1 2026
NEEM AT PARK FIVE
Deyaar Development (P.J.S.C) · register end date Dec 2027
15.2%
at 9 Sep 2026
1,31389Studio AED 683,058 (2 sales) · 1 bed AED 1.04m · 2 bed AED 1.49m · 3 bed AED 2.2m
+3.2% Q4 2025 → Q1 2026
Golf Grove by Regent
Regent Star Property Developments L.L.C · register end date Jan 2028
8.7%
at 10 Jun 2026
1,45446Studio AED 610,000 · 1 bed AED 999,000
ALDER AT PARK FIVE
Deyaar Development (P.J.S.C) · register end date Dec 2027
6.1%
at 30 Sep 2026
1,396451 bed AED 1.1m · 2 bed AED 1.7m · 3 bed AED 2.39m
Samana Lake Views 2
Samana Signature Real Estate Developments L.L.C
Project brief
8.9%
at 10 Jun 2026
1,46240Studio AED 694,529 · 1 bed AED 1.16m · 2 bed AED 1.45m
Samana Lake Views
Samana Signature Real Estate Developments L.L.C
Project brief
22.9%
at 28 Sep 2026
1,52531Studio AED 703,728 · 1 bed AED 1.06m · 2 bed AED 1.38m (4 sales)
Samana Portofino
Samana International Real Estate Development L.L.C
60.1%
at 29 Sep 2026
1,255
8 sales
8Studio AED 749,572 (3 sales) · 1 bed AED 658,896 (one sale) · 2 bed AED 1.58m (4 sales)

All projects under construction in Me'Aisem First

DLD project register (completion percentage as read on the date shown) and transaction register — sales of units registered 28 April 2025 to 5 October 2026, duplicates removed.

How this table is built

Completion percentage is the register’s own, read on the date shown against each project. The median is over the project’s registered sales in the window and is published only from ten sales; quarterly movement only where each quarter holds twenty or more. Hotel rooms and serviced units are left out where the register marks them.

Completion percentage and the register’s own median are the two numbers a payment plan should be read against.

Developments here

Multiple · ~2,500+ (+5,000 pipline) units · launched 2003
Dubai Production City
The developer, the launch date and the unit count are this guide’s own, as captured.

What a development here is worth today is a register question, and we will read it back to you building by building.

Deals below market here now

UnitAskingSizePer sq ft
2-BR IN SKYVIEWS
handover Q4 2028
AED 1,250,000
18.1% below o.p.
1,128 sq.ftAED 1,108

Mitchell’s deal pages, as published. Asking prices and the discount are stated on each deal’s own page with their basis; we act for the buyer on every one.

Each of these can be read against the register history of its own building before you commit.

Project briefs

Mitchell's project briefs, written from the developer's own material.

New launches

Mitchell's new-launch pages, as published.

DUBAI PRODUCTION CITY: TECOM FREE ZONE YIELD COMMUNITY

The community was established in 2003, spans approximately 43 million square feet and is focused on graphic art, printing, publishing, packaging and media production. Only about 40 per cent of the available land has been developed, and the masterplan has moved at a slow pace since inception — a characteristic that investors should factor into any long-term thesis for the community.

The residential component spans 122 building developments. Completed buildings include Lakeside, Lago Vista, The Crescent, Afnan 1 through 5, MYKA Residence, Noor 1, 2 and 4, Qasr Sabah, and Viera Residences, completed on 31 December 2025 (DLD register, as at 8 September 2026). Active off-plan supply includes Binghatti Elite, Samana Lake Views 2, Samana Resorts and the recently launched Nirvana Residence 1 by Meraki Developers in January 2026. Golf Grove by Regent is planned. Popular buildings among tenants include Midtown, Lakeside, Centrium Towers, Lago Vista and The Crescent Towers, with a mix of studio, 1, 2 and 3-bedroom apartment formats across the stock.

For investors, Dubai Production City is a Tier 2 yield play. Twelve-month aggregated data shows gross rental yields of 6.25 to 7.44 per cent — studios at 7.04 per cent, 1-beds at 7.44 per cent, 2-beds at 6.97 per cent, 3-beds at 6.25 per cent — with average annual asking rents of AED 45,000 for studios, AED 66,000 for 1-beds, AED 95,000 for 2-beds and AED 106,000 for 3-beds. These yields are among the highest documented corridors for Dubai apartments. The yield thesis is straightforward: affordable entry, recurring free-zone tenant demand and single-entity TECOM stewardship. The constraints are equally clear and permanent: no metro, modest retail, slow masterplan buildout, and a community identity that is functional rather than aspirational.

Location places Dubai Production City within the broader DubaiLand corridor. Primary vehicle access runs along Sheikh Mohammed Bin Zayed Road, with secondary routing via Al Khail Road, Hessa Street and Emirates Road connecting to Jumeirah Village Circle, Arabian Ranches, Motor City, Dubai Sports City and the wider Dubailand entertainment cluster. City Centre Me'aisem by Majid Al Futtaim is the main retail anchor. Nearby anchors include Global Village, IMG Worlds of Adventure, Miracle Garden, Dubai Autodrome and Dubai Polo & Equestrian Club. Adjacent communities including JVC, JVT, Arabian Ranches and Motor City reinforce the mid-market character of the wider Dubailand residential belt.

Classified as Tier 2 — Yield & Volume, Dubai Production City serves investors prioritising yield generation, affordable entry and recurring free-zone tenant demand. This guide covers the acquisition strategy for buy-to-let and affordable-segment yield buyers, the due diligence framework across completed secondary stock and new off-plan product, the rental yield dynamics supported by structural TECOM-sector tenant demand, and the portfolio construction role of this community as a Tier 2 yield contributor within a balanced Dubai residential portfolio. Careful building and unit-format selection is central to return optimisation given the spread between completed stock and off-plan pricing. Long-term holders with 5 to 7 year horizons will find Dubai Production City one of the highest-yielding Tier 2 apartment positions in Dubai.

DUBAI PRODUCTION CITY: MARKET ANALYSIS AND INVESTMENT DYNAMICS

INFRASTRUCTURE AND CONNECTIVITY

Dubai Production City sits in Me'aisem First, DubaiLand, with primary vehicle access along Sheikh Mohammed Bin Zayed Road. There is no metro connectivity and no credible prospect of metro extension to this location within any foreseeable planning horizon — this is a permanent valuation ceiling relative to metro-served communities elsewhere in Dubai. Bus routes serve the community. City Centre Me'aisem, a Majid Al Futtaim mall, is the main retail anchor. Community lakes and dedicated running tracks have been developed, though landscaping around the lakes has only recently matured after years of bare construction. Nearby anchors include Jumeirah Village Circle, Jumeirah Village Triangle, Arabian Ranches, Motor City, Dubai Sports City, Global Village, IMG Worlds of Adventure and Miracle Garden. The community functions as a TECOM-managed free zone centred on graphic art, printing, publishing, packaging and media production, and approximately 60 per cent of the 43 million square foot masterplan remains undeveloped.

RENTAL MARKET AND TENANT PROFILE

Twelve-month aggregated data shows gross rental yields of 7.04 per cent on studios, 7.44 per cent on 1-bedroom units, 6.97 per cent on 2-bedroom units and 6.25 per cent on 3-bedroom units — a 6.25 to 7.44 per cent band that is among the highest documented yield corridors in Dubai for apartments. Average annual asking rents are AED 45,000 for studios, AED 66,000 for 1-beds, AED 95,000 for 2-beds and AED 106,000 for 3-beds. The tenant profile is anchored by the TECOM free zone: media, printing and production professionals who work within the zone and need proximate housing, young singles and couples seeking affordable freehold options, and expatriate families in the entry-level segment. This tenant base is structurally recurring and less sensitive to luxury-market cycles. The 1-bedroom format generates the highest yield at 7.44 per cent, aligning with the dominant tenant demographic of single professionals and couples working in the free zone.

SUPPLY DYNAMICS AND PORTFOLIO POSITIONING

Recent April 2026 DLD transactions confirm active trading at the affordable end: Samana Resorts Tower A 1-bed at AED 1.17M, Afnan 3 1-bed at AED 805K, Reef 996 studio at AED 702K, Jannat 1-bed at AED 1.02M, ELM at Park Five 1-bed at AED 1.02M, and Lakeside Tower C studio at AED 400K. February 2026 off-plan trading includes Ivy at Park Five 1-bed at AED 1,508 per sqft. The secondary-market pricing spread is wide — Lakeside Tower C studio at AED 400K versus Samana Resorts 1-bed at AED 1.17M — reflecting the gap between older completed stock and new off-plan product. Only 40 per cent of the masterplan is developed, so significant supply capacity remains. Inside a Dubai portfolio, Dubai Production City sits as a pure yield allocation in the Tier 2 bucket — not a capital-appreciation play, not a lifestyle hold. Portfolio weighting should reflect the yield thesis: it generates cash flow while Tier 1 holdings in Downtown, Palm and Dubai Harbour carry the capital-preservation mandate.

DUBAI PRODUCTION CITY: INVESTMENT STRATEGY AND ENTRY POINTS

The first strategic question is whether to buy completed secondary stock or new off-plan. The yield case is strongest in completed buildings where the rental track record is already documented. Lakeside Tower C studio at AED 400K represents the floor end; Afnan 3 1-bed at AED 805K represents the mid-market core. At AED 66,000 average annual rent for a 1-bed and a purchase price of AED 805K, the gross yield is 8.2 per cent — above the 12-month aggregate of 7.44 per cent, which suggests some completed stock is still trading at a discount to the yield-weighted average. Off-plan product at Ivy at Park Five around AED 1,508 per sqft and Samana Resorts at AED 1.17 million for a 1-bed prices materially higher and carries a zero-income construction window before handover. The off-plan premium is justifiable only if the investor is specifically seeking newer finishes and amenity packages and can absorb 12 to 24 months of zero income.

The second strategic question is format selection. The 1-bedroom format at 7.44 per cent gross is the optimal yield configuration, matching the dominant tenant demographic of single professionals and couples. Studios yield 7.04 per cent but carry higher turnover and shorter average tenancies. 2-beds at 6.97 per cent serve families and command larger absolute rents at AED 95,000 but require higher capital outlay. 3-beds at 6.25 per cent should be avoided for pure yield plays — the lower return reflects lower demand density at that format level in this community. The investor should concentrate capital in 1-bed and studio formats across the completed towers (Lakeside, Lago Vista, The Crescent, Afnan, Noor, MYKA) where tenant base and rental history are already established.

The third strategic question is portfolio weighting. Dubai Production City is a yield satellite, not a portfolio anchor. Inside a diversified Dubai allocation, a sensible weight is 10 to 20 per cent — enough to meaningfully lift the blended portfolio yield without overexposing to a single community's infrastructure limitations. The rest of the portfolio should anchor in Tier 1 capital-preservation holds (Downtown Dubai, Palm Jumeirah, Dubai Harbour, Emaar Beachfront) that provide resale liquidity and appreciation. Do not hold more than three to four units in the same building to avoid concentration risk at the block level.

The risk framework is explicit. No metro means a permanent valuation ceiling — accept this upfront and do not model it away. Only 40 per cent of the masterplan is developed and the buildout pace is slow; this is both a risk (amenity immaturity) and an opportunity (future demand as more land activates). New off-plan supply from Samana, Binghatti, Meraki and others could compress yields if absorption does not keep pace — monitor occupancy rates in completed buildings before scaling into additional units. The TECOM free zone dependency means that contraction in the media and production sectors would directly impact tenant demand and rental velocity. Retail variety beyond City Centre Me'aisem is limited. Service charges in older buildings may run higher than expected due to the age of the stock; verify service-charge history before acquiring any unit. Meaningful portfolio exposure to Dubai Production City typically requires AED 1.5 million and above of committed capital across multiple units to generate a material yield contribution.

SUPPLY DYNAMICS

TECOM master developer, multi-developer phased supply, 122 buildings, ~40% masterplan developed

TENANT PROFILE

Media and production professionals, free zone workers, young couples, entry-segment expat families

KEY RISK FACTORS

No metro connectivity, slow masterplan buildout, new off-plan supply, TECOM sector dependency

KEY INFRASTRUCTURE

Dubai Production City sits in Me'aisem First, DubaiLand, along Sheikh Mohammed Bin Zayed Road (E311), with access to Al Khail Road (E44), Hessa Street (D61) and Emirates Road (E611) connecting to Jumeirah Village Circle, Arabian Ranches, Motor City, Dubai Sports City and the wider Dubailand corridor. The community is internally anchored by City Centre Me'aisem (Majid Al Futtaim), the TECOM-managed media and production free zone, community lakes, dedicated running and cycling tracks, landscaped amenity areas, schools, nurseries and retail. Nearby external anchors include Jumeirah Village Circle, Jumeirah Village Triangle, Arabian Ranches 1 and 2, Dubai Sports City, Motor City, Dubai Autodrome, Global Village, IMG Worlds of Adventure and Miracle Garden. Adjacent developer communities include JVC, JVT, Arabian Ranches and Motor City, reinforcing Dubai Production City's positioning within Dubai's mid-market yield corridor. The community is car-dependent with no direct metro connectivity.

Area fundamentals

ASSET PROFILE
TECOM free zone affordable-segment yield community
INVESTOR PROFILE
Yield-focused buy-to-let + affordable-segment allocator
TIER
Tier 2 – Yield & Volume
MARKET TYPE
Mid-market, apartments, free zone-adjacent, affordable
EST. POPULATION
~25,000–40,000
LAND SIZE
~43m sq ft

Next step

Request a briefing

You will get Dubai Production City as a brief: the buildings on this page, the register readings behind them, and our view on each.
Sent with your enquiry:Dubai Production Citypurpose not statedbudget not statedno buildings on screenasked from: the brief

We come back with specifics, not a brochure. Stephen Mitchell · RERA BRN 68593 · in Dubai since 2007.

Location

Dubai Production City, Dubai

Get Directions

Try it yourself

Investor Tools

Rental Yield Calculator

Model the gross and net return on a Dubai buy-to-let purchase. It covers service charges, void periods and acquisition costs.

All-in purchase price before transaction costs.

Total contracted rent for one year, before charges.

Community and building service charges, annualised.

5%

Your buffer for void periods. 5% is about 18 days empty a year — a month is 8%.

7%

7% is the 4% DLD transfer fee, 2% agency plus VAT, and DLD's flat registration lines. It excludes the developer NOC and any legal quote — see the Buying Costs Calculator for the full itemisation.

6% net

The net yield a deal has to clear to interest you. Sets the target line on the curve — it does not change the yield above it.

5.3%Net rental yield
Moderate yield
Gross yieldGross yield: 7.00%
Net annual incomeNet annual income: AED 84,750
Monthly net incomeMonthly net income: AED 7,063
Total cash investedTotal cash invested: AED 1,605,000

Against your 6% hurdle

Short of it
9.1%0%AED 975KAED 2.03M
Net yield (vertical) against the price you pay (horizontal), on the rent, charges and costs entered. The gold dot is your deal; the line across is your hurdle.
Price that clears it
AED 1,320,093AED 179,907 below your price — a 12.0% discount.
Rent that clears it
AED 117,158AED 12,158 a year more than you have entered, at this price.

Estimates for guidance only, assuming full-year occupancy net of the vacancy allowance above. Actual returns depend on financing, unit condition and market timing — speak to an advisor for a deal-specific model.

Email my results

We’ll send this summary — your figures and the results — to your inbox.

Next step

We'll hunt deals that meet or beat this yield hurdle

Send us this scenario and we'll go into the market against it — on-market and off — qualify what we find, and only come back with what clears your number.

Got questions?

Get Answers!
Continue reading

The closest area guides to this one, matched on subject.

Showing 4 of 101 Dubai area guides.

Browse all 101 area guides
Need help?