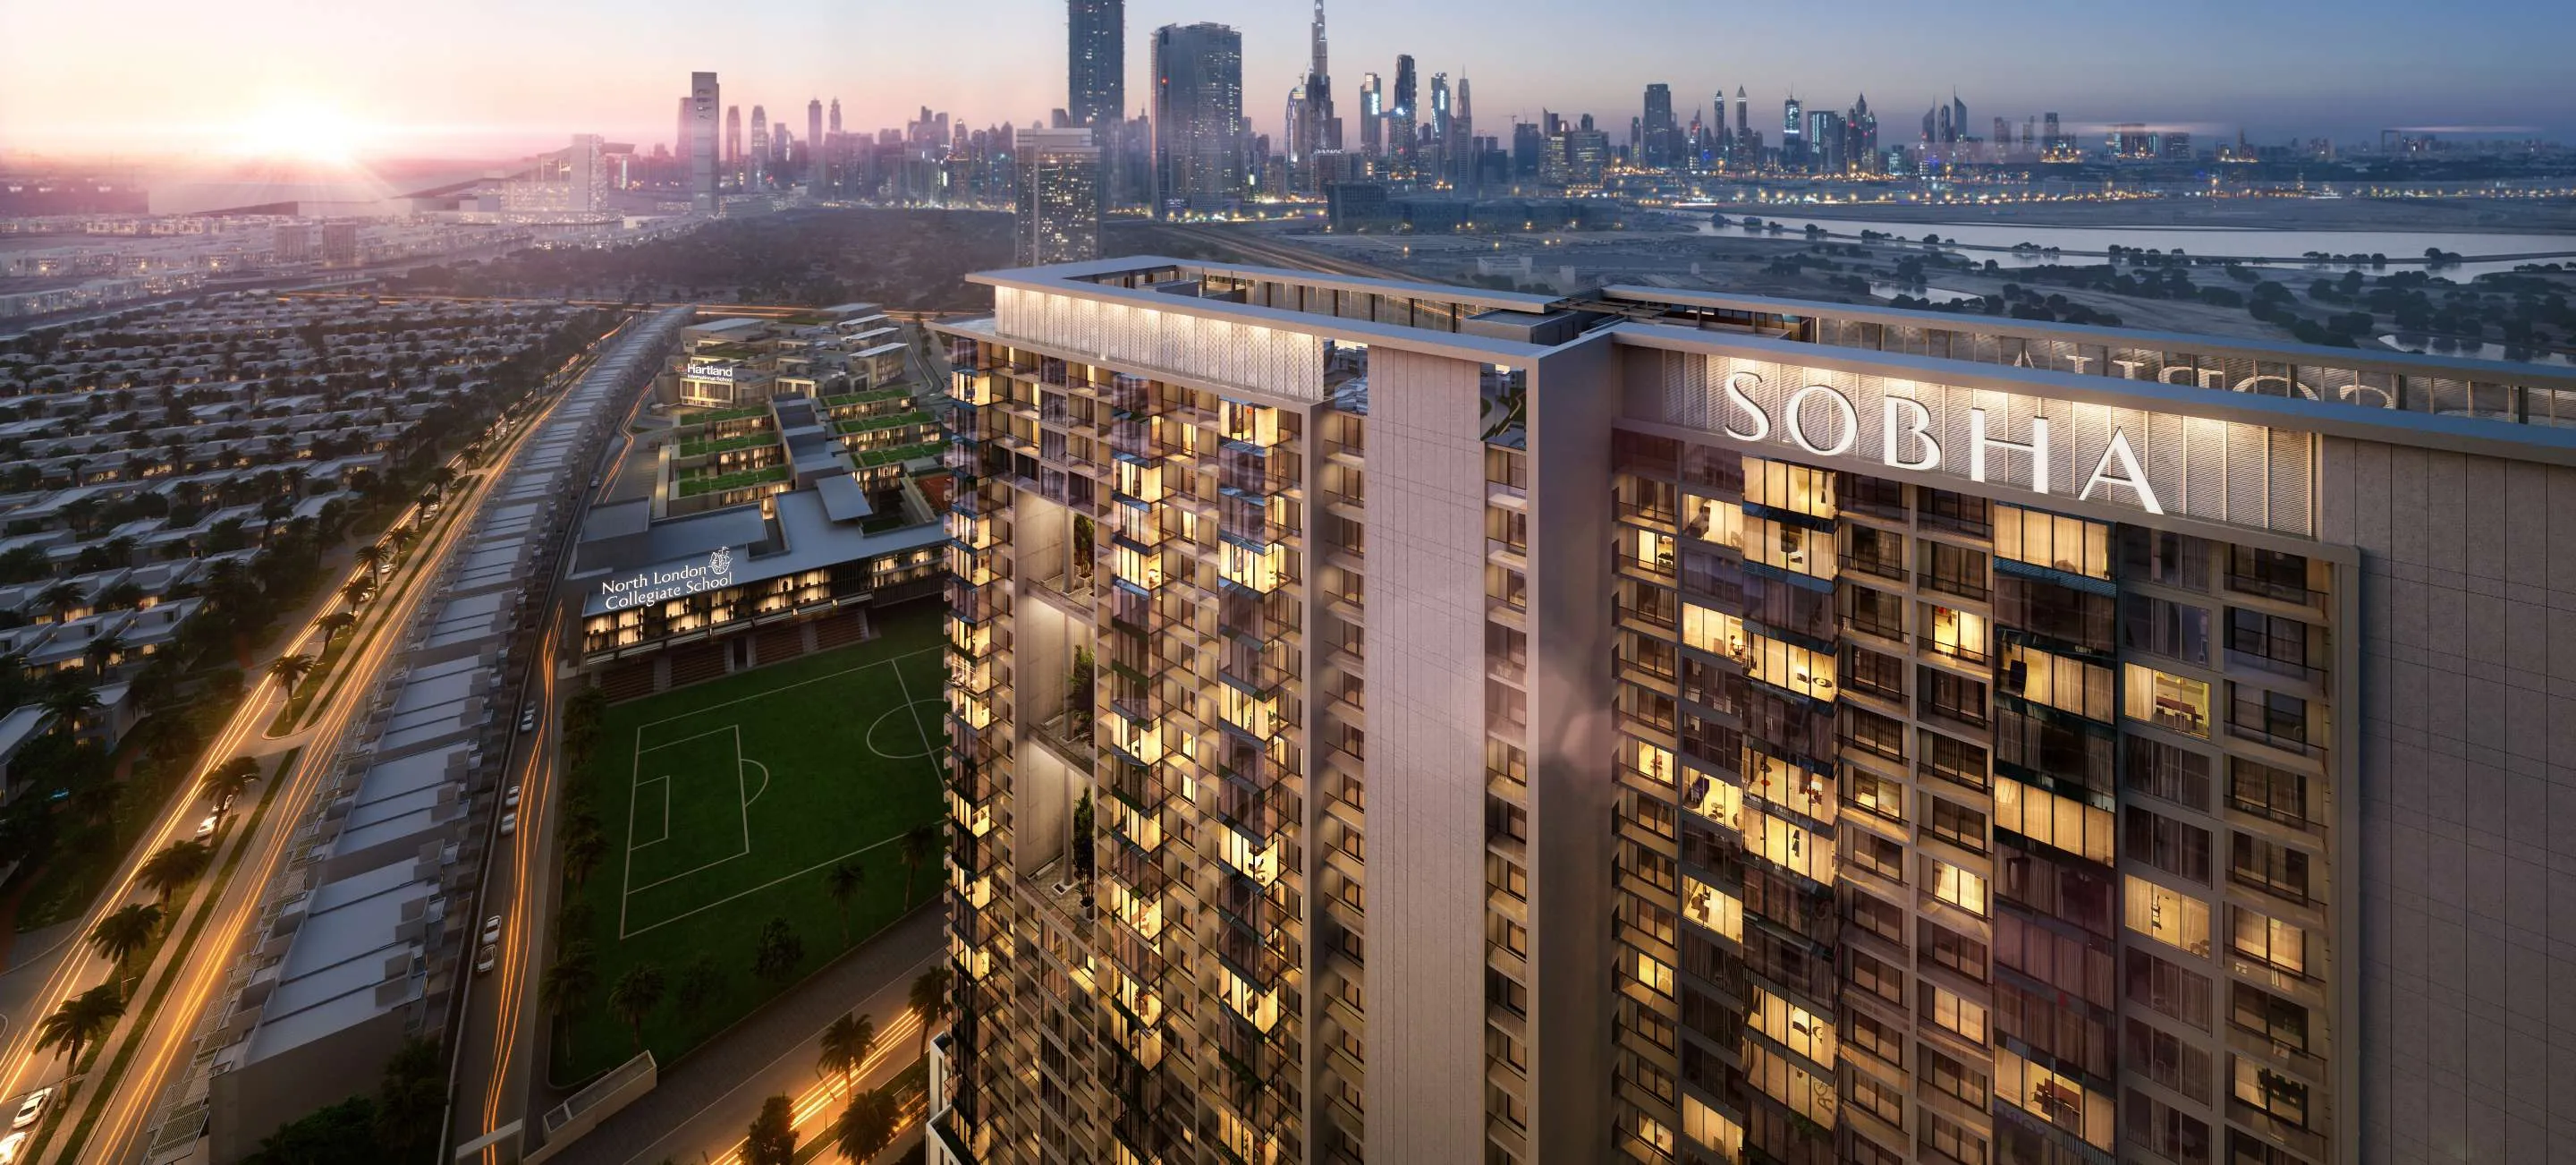
DISTRICT ONE: MEYDAN'S ULTRA-LUXURY LAGOON COMMUNITY
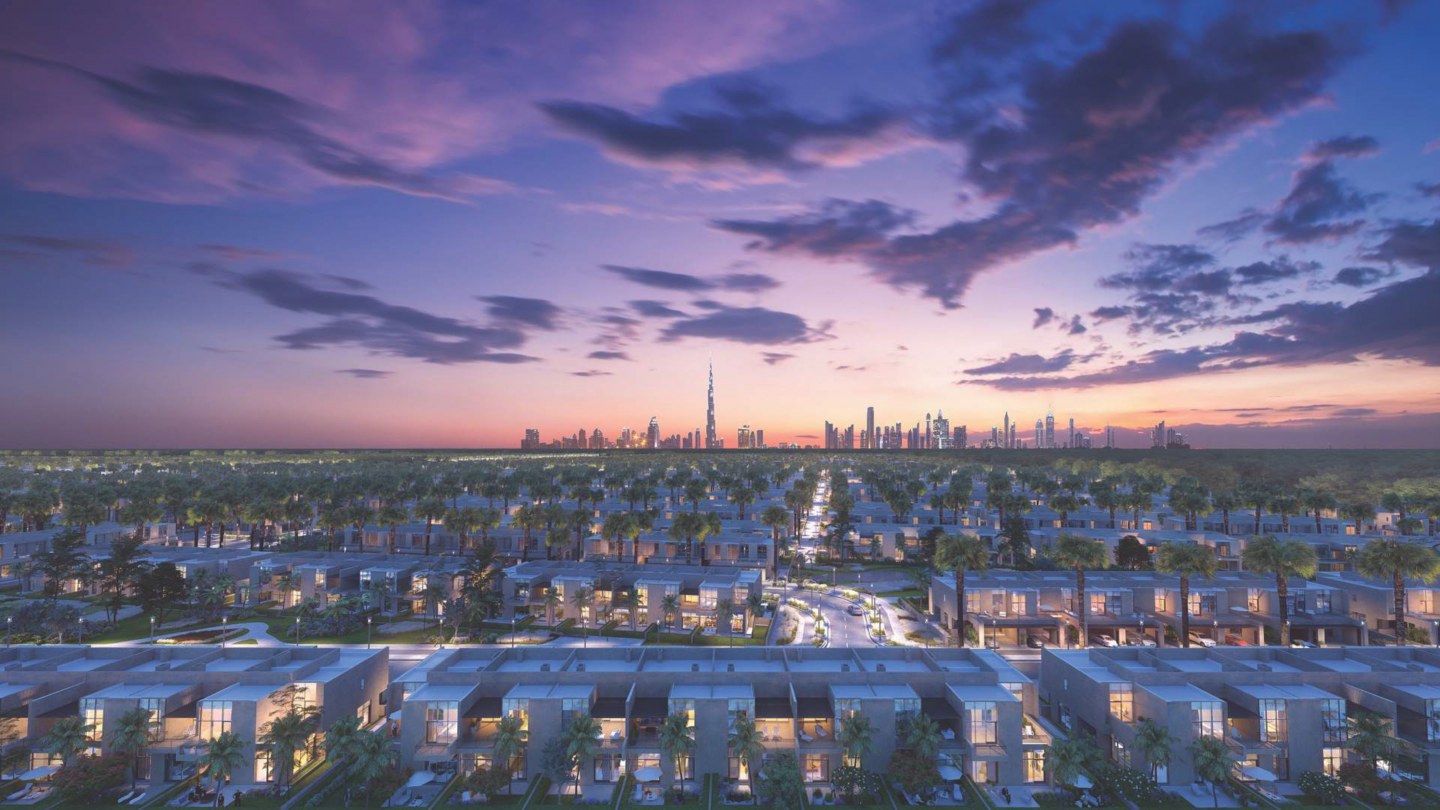
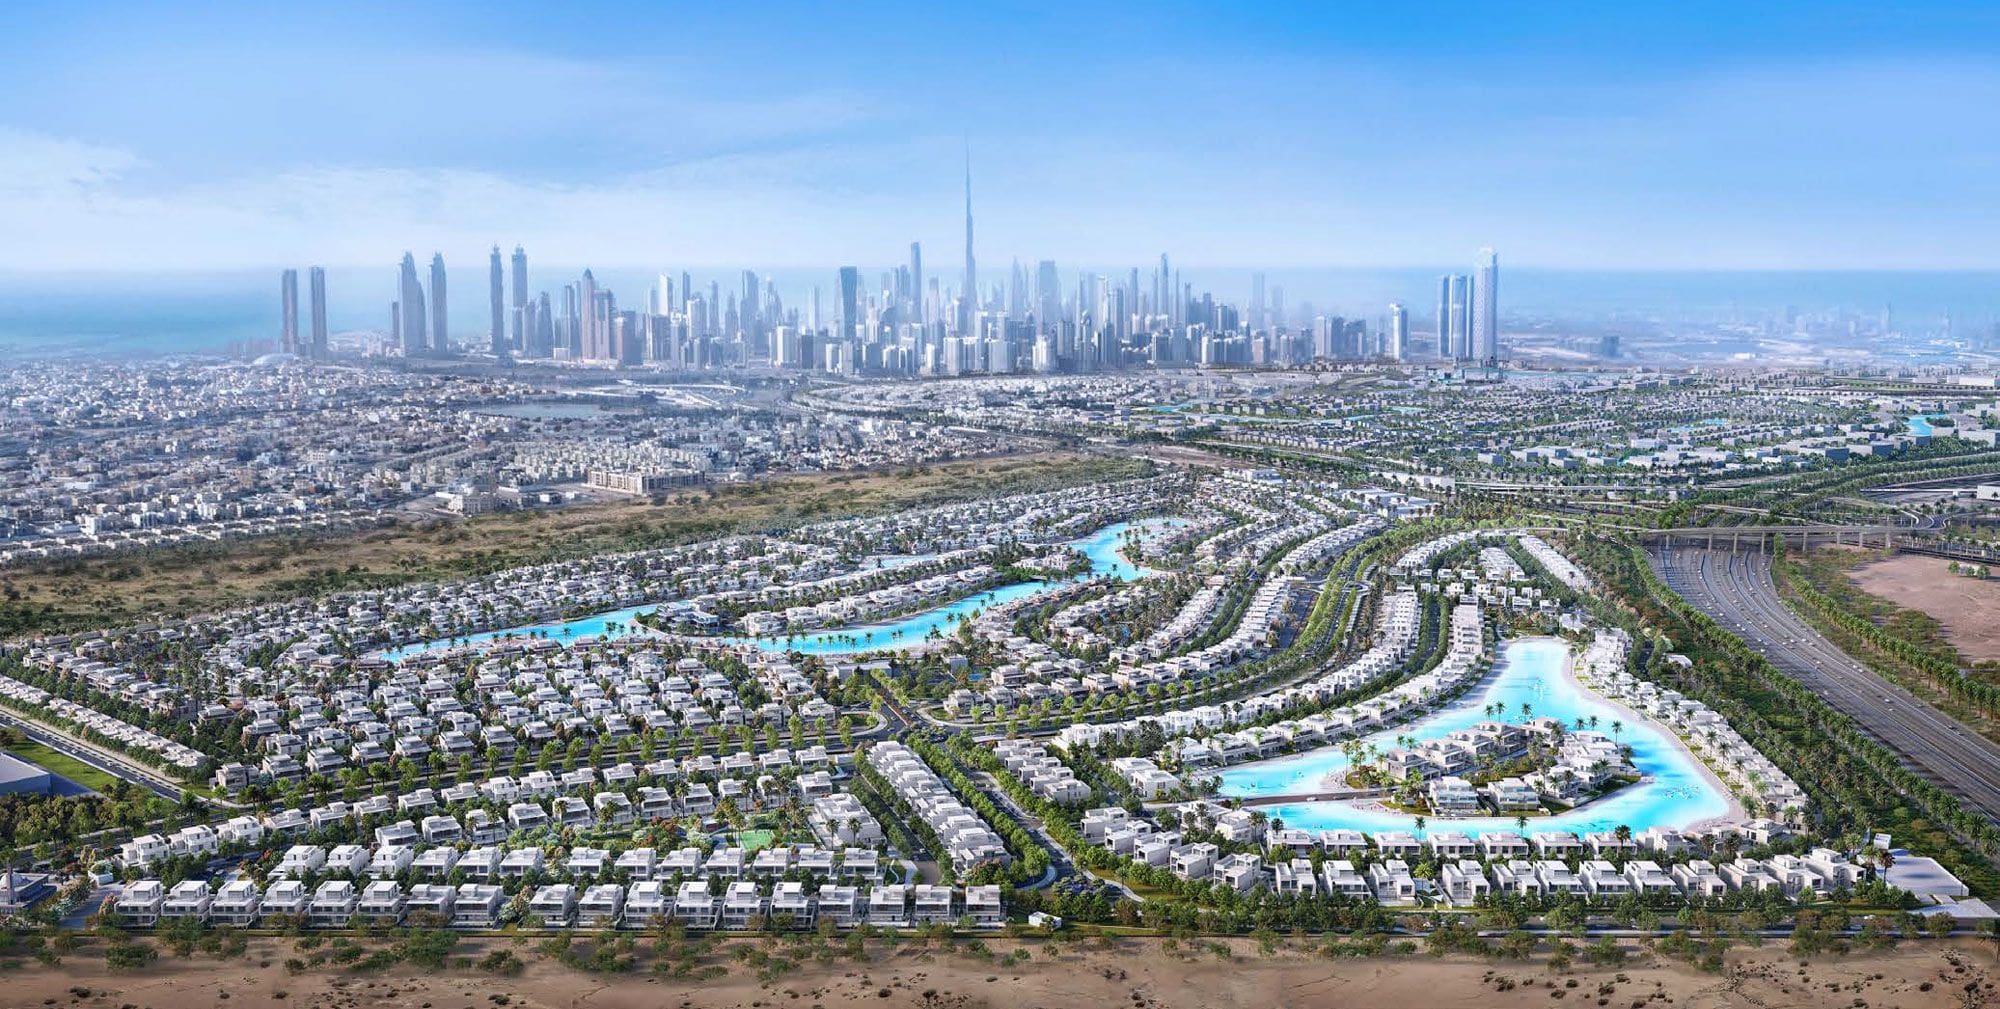
This is a freehold crystal lagoon community within Mohammed Bin Rashid City, developed by Nakheel (Nakheel, 2026), with the kind of lifestyle differentiation that defines Dubai's Tier 1 core capital segment. The community is built around a 7-kilometre crystal lagoon fringed by man-made beaches and landscaped parkland, with villas and apartment buildings arranged across seven sub-communities. No other Dubai community currently offers a comparable lagoon-fronting villa product at this scale — that structural lifestyle moat is the foundation of the District One investment thesis.
Nakheel's own website lists District One among its master developments (read September 2026). The community launched in 2015 and is delivering across a phased roadmap through 2028. The seven sub-communities are A Villas (complete), B Extension Villas (complete), B Villas (under development), C Villas (complete), Mansions (under development), Residences apartments (complete across Residences 2–25) and West Villas (under development). The community features villas in 4, 5 and 6-bedroom configurations in modern Mediterranean and Arab architectural styles, alongside the Residences apartment buildings and the newer Naya 2 and Naya 3 apartment towers.
The crystal lagoon is the defining asset. A 7-kilometre swimmable lagoon with man-made beaches and landscaped parkland runs through the community, providing a lifestyle differentiation that is structurally unique within Dubai's villa market. Road connectivity is via Al Khail Road (E44) and Al Maydan Road (D69), with direct arterial access to Downtown Dubai, DIFC and Business Bay. There is no metro access — the nearest station is Business Bay on the Green Line — but for the UHNW target demographic, metro is not a practical tenancy constraint.
For investors, District One is a Tier 1 Core Capital play. Villa gross yields of 5.5 to 6.3 per cent sit at the upper end of Dubai's ultra-luxury villa cohort, with 4-bedroom villa sales averaging AED 10.7 million, 5-bedrooms averaging AED 22.8 million and 6-bedrooms averaging AED 32.7 million. Apartment gross yields in the Residences buildings range from 5.5 to 6.8 per cent across 1 to 4-bedroom units. The community has been identified as one of Dubai's highest-ROI villa destinations — strong for ultra-luxury villa stock. The investment thesis is not yield maximisation but capital preservation combined with lifestyle premium: finite lagoon-front supply and UHNW demand.
In the sections that follow, I will examine District One's infrastructure and connectivity profile — particularly the road network that shapes commuting patterns and the lifestyle infrastructure that defines the community — the rental market dynamics and the UHNW tenant profile that drives consistent villa occupancy, and the supply considerations across completed and under-development sub-communities. I will close with a strategic framework for approaching District One across villa and apartment segments at very different capital commitment levels.
DISTRICT ONE: MARKET ANALYSIS AND INVESTMENT DYNAMICS
INFRASTRUCTURE AND CONNECTIVITY
District One has no metro access. The nearest station is Business Bay on the Green Line, not walkable. Road connectivity runs via Al Khail Road (E44) and Al Maydan Road (D69), providing arterial access to Downtown Dubai, Dubai Mall, Palm Jumeirah, Burj Al Arab, The Walk JBR, Dubai International Airport and Al Maktoum International Airport. For the UHNW target demographic, the absence of metro is not a practical constraint — these households are car-dependent by choice. The crystal lagoon is the primary lifestyle infrastructure: a 7-kilometre swimmable lagoon with man-made beaches, cycling tracks and landscaped parklands. Most villas have at least one car garage with ample visitor street parking. Schools near District One include Clarion School, Dubai International School Al Quoz and Springdales School Dubai, plus nurseries including Maple Bear Pre School, Jumeirah International Nursery and Kids Cottage Nursery. The Habtoor Polo Club sits adjacent. The broader MBR City infrastructure includes Dubai Hills Mall and the planned Meydan One Mall — the latter's delivery timeline is a watchpoint for the southern perimeter.
RENTAL MARKET AND TENANT PROFILE
District One's rental market operates at two very different ends of the Dubai spectrum. Villa rental averages run AED 789,000 on 4-bedrooms, AED 1.4 million on 5-bedrooms and AED 2.2 million on 6-bedrooms. Apartment rental averages run AED 113,000 on 1-bedrooms, AED 205,000 on 2-bedrooms and AED 285,000 on 3-bedrooms. Executed rental transactions reveal meaningful spreads within the same bedroom count: 4-bedroom villas have transacted at AED 800,000 and AED 600,000 on the same date — a 33 per cent spread that shows lagoon proximity and specification drive significant rental variation. Internal villas set back from the lagoon can discount by 30 per cent or more relative to lagoon-fronting product. Villa gross yields of 5.5 to 6.3 per cent and apartment gross yields of 5.5 to 6.8 per cent are strong for ultra-luxury stock.
SUPPLY DYNAMICS AND PORTFOLIO POSITIONING
District One's supply is partially constrained and partially expanding. Four sub-communities are complete (A Villas, B Extension Villas, C Villas, Residences) and three are under development (B Villas, Mansions, West Villas). The crystal lagoon perimeter provides a natural supply constraint for lagoon-fronting villas, but the Mansions and West Villas sub-communities will introduce new inventory over 2026–2028 that may disrupt the pricing hierarchy. Recent DLD transactions show active trading across 4-bedroom villas, Residences 1-bedrooms, Naya 2 and Naya 3 apartments. Current market inventory sits at roughly 24 units for sale and 42 for rent, dominated by 4 and 5-bedroom villas. Within a Dubai portfolio, District One occupies the Tier 1 ultra-luxury allocation, pairing with Downtown Dubai and Palm Jumeirah for prime capital preservation while Residences and Naya apartments provide lower-ticket exposure to the same address.
DISTRICT ONE: INVESTMENT STRATEGY AND ENTRY POINTS
The first strategic question is product type: villa or apartment. District One villas are the headline product — crystal lagoon lifestyle, UHNW demand, gross yields of 5.5 to 6.3 per cent, average pricing from AED 10.7 million on 4-bedrooms to AED 32.7 million on 6-bedrooms. District One Residences apartments are the accessible entry: 1-bedrooms from AED 1.18 million and 2-bedrooms from AED 2.71 million, with gross yields of 5.5 to 6.8 per cent. The Naya buildings sit between these segments at AED 1.57 to 3.96 million. For capital growth positioning with a 7 to 10-year hold, the villa segment is the primary thesis — finite lagoon supply, UHNW demand resilience and the Mohammed Bin Rashid Al Maktoum brand provide structural price support. For yield with moderate capital growth, the Residences and Naya apartments offer higher yields at materially lower entry points, though they compete with metro-connected alternatives for tenant demand.
The second strategic question is villa selection within District One. Lagoon-fronting villas with direct beach access command premium rents and prices. Internal villas set back from the lagoon trade at discounts that can exceed 30 per cent on both sale price and rent. Investors should target completed sub-communities — A Villas, B Extension, C Villas — where rental track records can be verified, rather than under-development sub-communities where pricing is off-plan and rental assumptions are modelled rather than proven. Villa condition and landscape investment matter: the community is maturing and some villas now have two to four years of occupancy history, providing data on actual maintenance costs, service charge levels and tenant retention. The Mansions sub-community under development will deliver a higher-priced tier that may re-rank the internal hierarchy when it completes.
The third strategic question is the apartment play. The Residences buildings provide exposure to the District One address and crystal lagoon amenity at 1-bedroom entry from roughly AED 1.18 million on recent DLD. Executed 1-bedroom new leases at AED 95,000 to AED 100,000 imply yields of 8.0 to 8.5 per cent at the AED 1.18 million entry price — significantly above the published average, suggesting the average uses asking prices rather than DLD transaction prices. Investors who source apartments at DLD-comparable prices can capture meaningful yield premium. The Naya buildings represent newer stock at higher price points — premium specification but lower yield at current rents.
Risk framework is explicit. The no-metro constraint is permanent — no announced plans for a station serving District One directly. Three sub-communities under development (B Villas, Mansions, West Villas) will bring new supply, with the Mansions project in particular potentially disrupting the current pricing hierarchy. Villa liquidity is inherently limited: AED 10 to 33 million ticket sizes narrow the exit buyer pool, and transaction timelines in ultra-luxury are measured in months not weeks. The crystal lagoon is District One's structural moat, but its uniqueness premium depends on no comparable lagoon development emerging elsewhere in Dubai — a watchpoint for the next five years. District One suits portfolios at the AED 1,000,000–30,000,000 capital commitment level depending on whether the allocation is apartment or villa, typically sized at one to two assets maximum given villa ticket scale.
SUPPLY DYNAMICS
Nakheel master development, 4 sub-communities complete, 3 under development, lagoon-front constrained
TENANT PROFILE
UHNW families, GCC family office buyers, premium lifestyle renters seeking lagoon-front villa living
KEY RISK FACTORS
No metro, Mansions and West Villas supply, villa liquidity at large ticket sizes, lagoon premium
KEY INFRASTRUCTURE
District One sits along Al Khail Road (E44) and Al Maydan Road (D69) in Mohammed Bin Rashid City, with arterial access to Downtown Dubai, DIFC, Business Bay and Dubai Hills Estate. The community is internally anchored by a 7 km crystal lagoon with man-made beaches, landscaped parklands, cycling tracks, a community clubhouse, swimming pools, tennis and basketball courts, retail promenade and the Habtoor Polo Club alongside villas, townhouses and the Residences and Naya apartment buildings across seven sub-communities. Nearby external anchors include Meydan Racecourse, The Track Meydan Golf, Nad Al Sheba Cycle Park, Dubai Hills Mall, Dubai Hills Golf Club, Dubai Mall and Downtown Dubai. Adjacent communities include Meydan, Dubai Hills Estate, Al Barari and the wider MBR City district, reinforcing District One's positioning as Dubai's flagship crystal lagoon UHNW villa enclave. No direct metro; nearest station Business Bay on the Green Line.
Area fundamentals
- ASSET PROFILE
- Meydan ultra-luxury lagoon villa enclave in MBR City
- INVESTOR PROFILE
- UHNW lifestyle buyer + capital preservation investor
- TIER
- Tier 1 – Core Capital
- MARKET TYPE
- Ultra-luxury, villas and apartments, lagoon-front
- EST. POPULATION
- ~10,000
- LAND SIZE
- ~45m sq ft
Next step
Request a briefing
You will get District One as a brief: the buildings on this page, the register readings behind them, and our view on each.