CITY WALK: MERAAS BRANDED URBAN LIFESTYLE DISTRICT
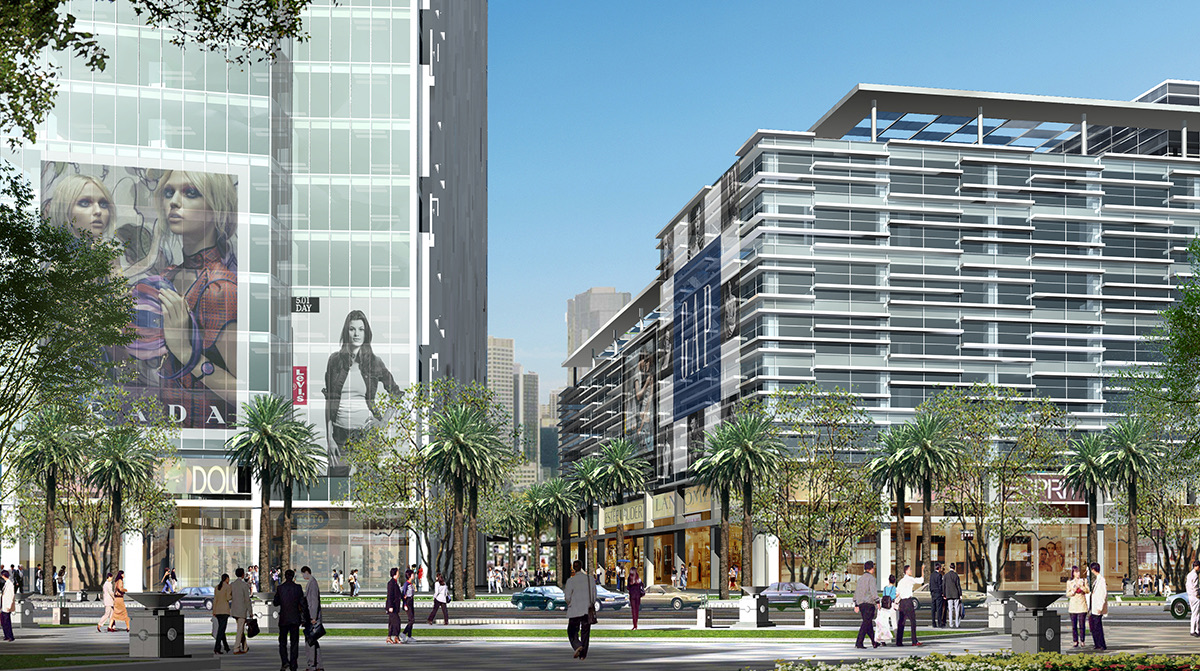
The three-phase masterplan combines boulevard retail with more than 170 units launched from Cityscape 2011, the 230,000 square metre Central Park launched in 2019, branded residential buildings and lifestyle amenities including the Green Planet bio-dome, the Coca-Cola Arena with a 20,000-person capacity, and the Valiant Clinic — a AED 300 million healthcare facility managed by Houston Methodist Global Health Care Services. The district comprises 50 building developments in total, with Merex Investment Group managing the retail and commercial operations.
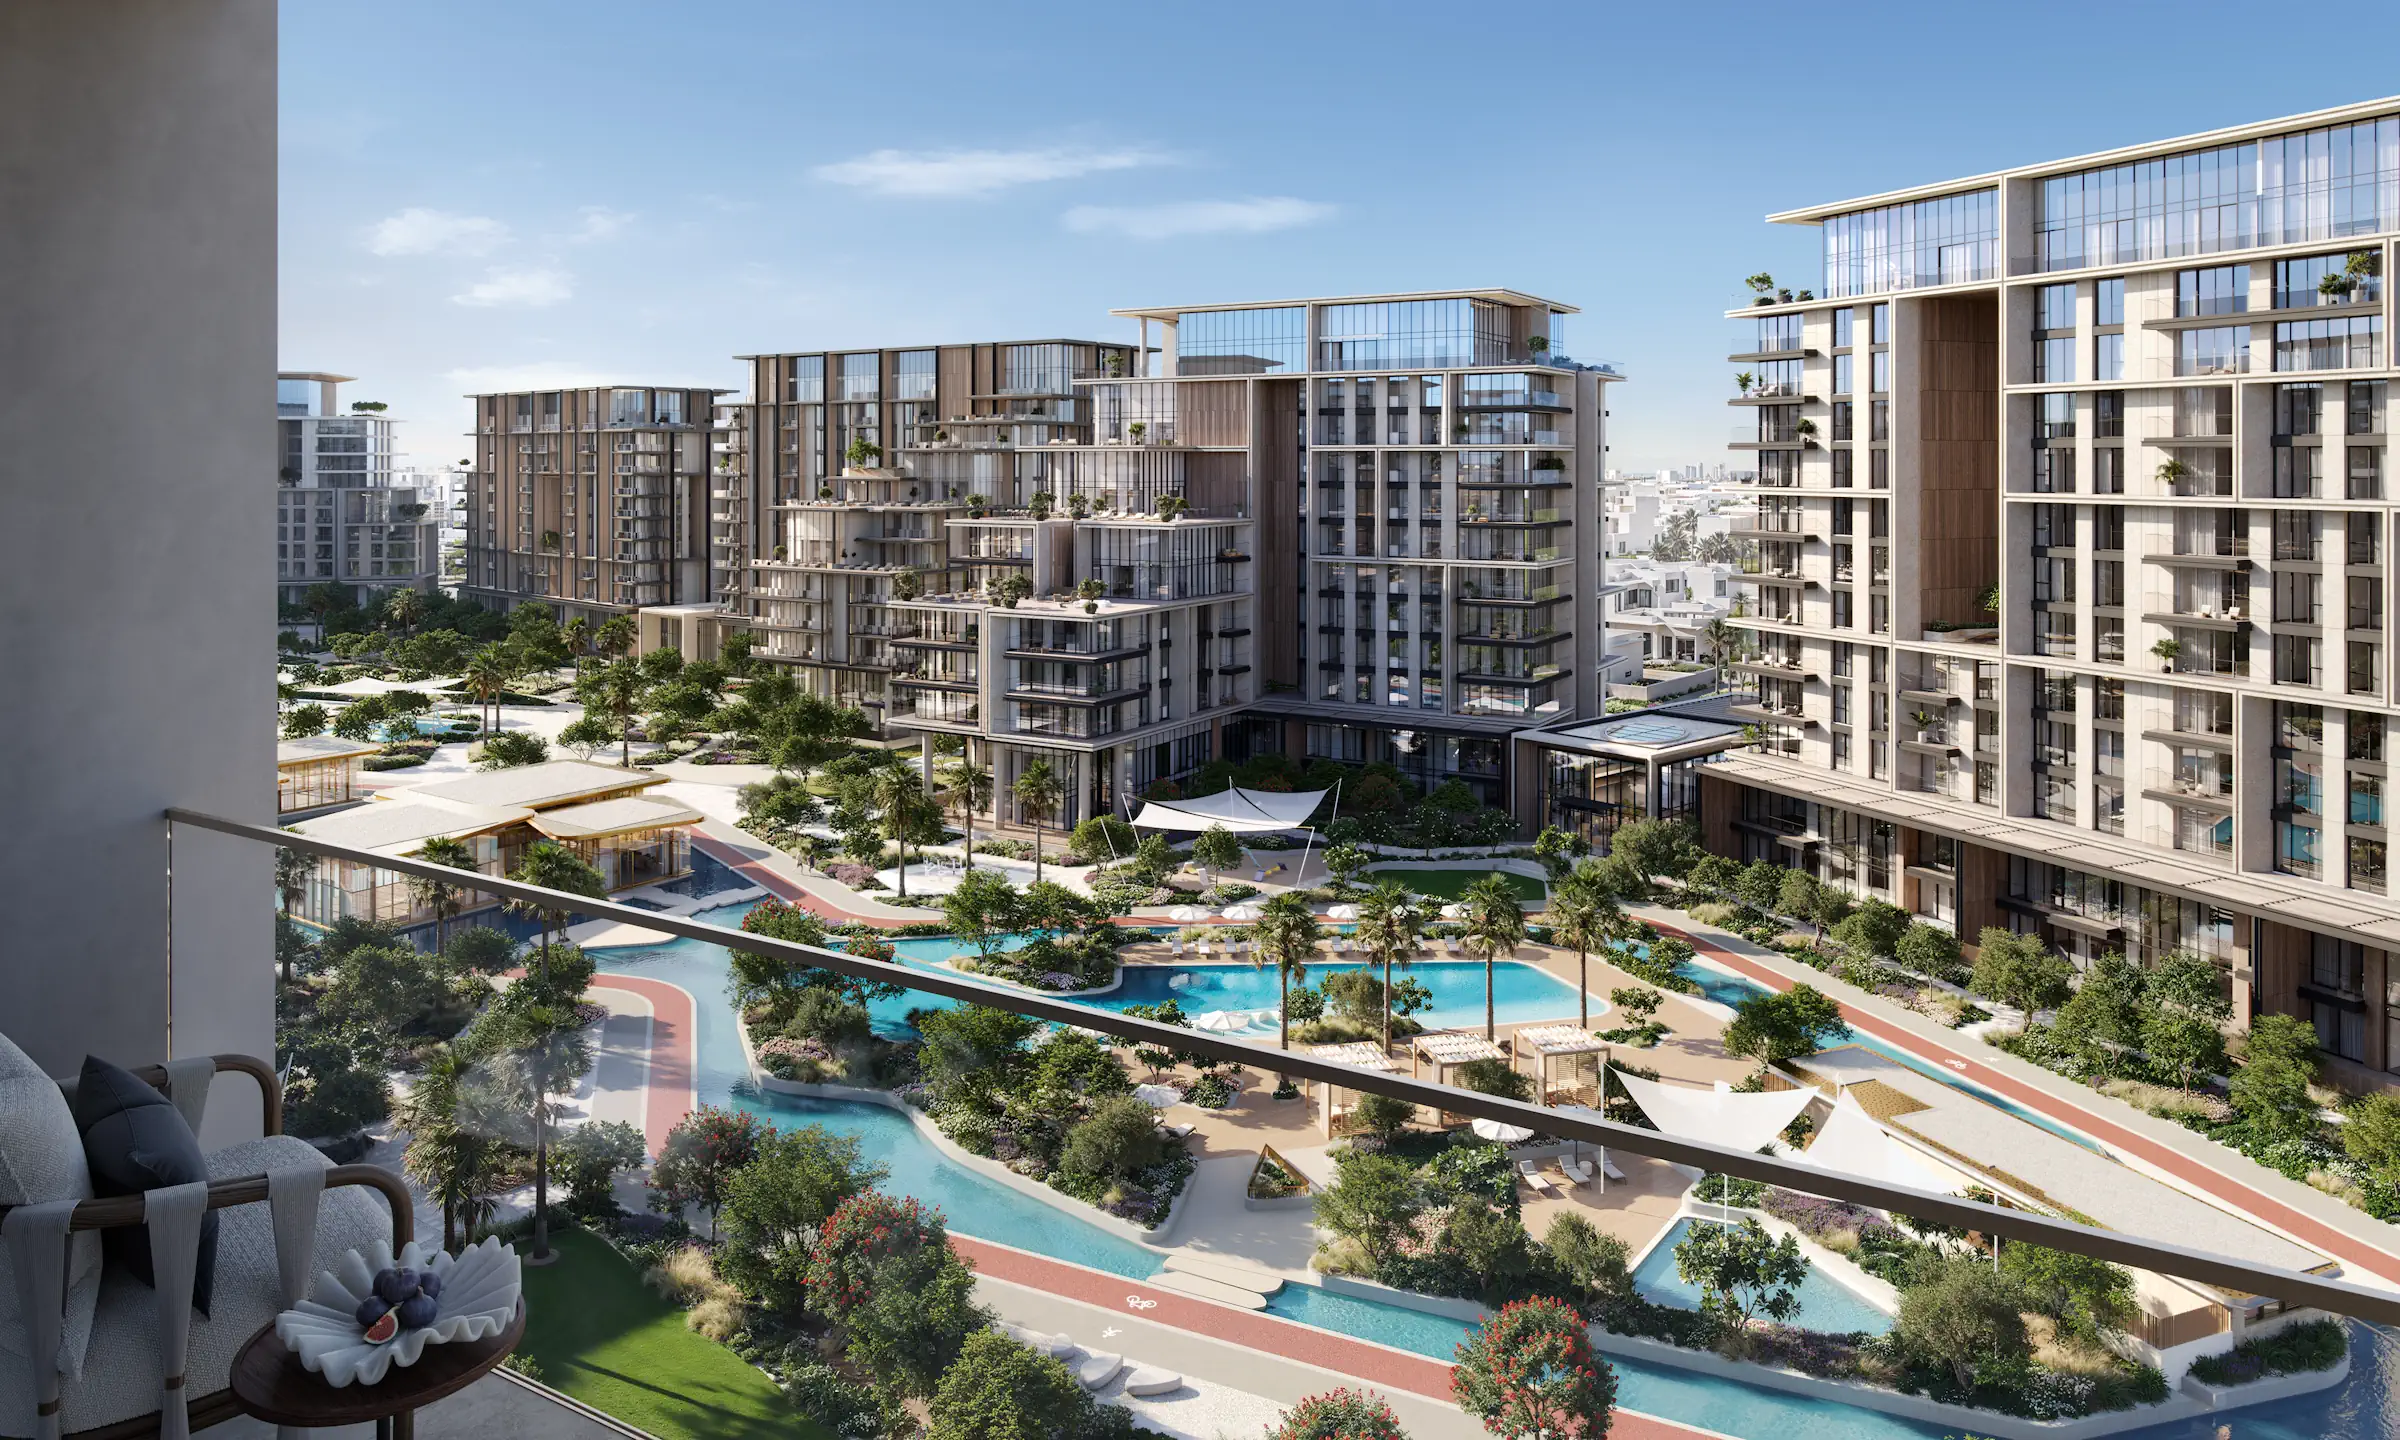
The residential component spans multiple branded clusters. Completed buildings include Myrtle at Central Park, Viridian at Central Park and Celadon at Central Park, plus numbered buildings throughout the district. Active delivery includes Fern at Central Park, 91 per cent complete at its last DLD inspection on 13 May 2026, Crestlane 1 from AED 2.6 million with Q2-Q3 2029 handover, Crestlane 4 and 5 from AED 2.7 to 2.8 million with Q2 2030 handover, and the Northline phases which commenced under a AED 120 million contract awarded in November 2025. Apartments range from 1-bed at 912 square feet to 4-bed at 5,906 square feet, plus duplexes with up to two terraces, two living areas and private pools. Hotels within the district include La Ville Hotel and Suites (5-star, Autograph Collection) and Rove City Walk.
For investors, City Walk is a Tier 1 core capital play. Published rental trends show 1-beds at approximately AED 160,000 per year, 2-beds at AED 252,000, 3-beds at AED 395,000 and 4-beds at AED 932,000. Gross yields range from 3.8 to 5.9 per cent depending on unit type, with the 1-bed segment delivering the strongest published yield at 5.91 per cent. Average sales sit at AED 729,000 for studios, AED 2,508,000 for 1-beds, AED 4,460,000 for 2-beds and AED 8,012,000 for 3-beds. The investment thesis rests on Meraas-controlled supply preventing developer fragmentation, Central Park lifestyle differentiation providing 230,000 square metres of parkland in central Dubai, and a repositioned commercial ecosystem that has transformed City Walk from retail-only destination into a functioning urban district with education, employment, healthcare and entertainment anchors.
Location anchors City Walk within central Dubai's most valuable residential corridor. The district sits between Downtown Dubai and the Jumeirah Beach Road leisure corridor, with Sheikh Zayed Road access providing rapid connectivity to DIFC, Business Bay and Dubai Marina. Business Bay Metro is within walkable range, positioning City Walk ahead of peer branded communities like Palm Jumeirah, Bluewaters Island and District One which lack metro proximity. Adjacent communities include Al Wasl, Jumeirah 1, Al Safa, Business Bay and Downtown Dubai, reinforcing the district's integration with Dubai's core central corridor. The retail, leisure, education and employment density within City Walk itself is difficult to replicate anywhere else in the city — Talabat regional headquarters brings approximately 2,000 staff daily, Canadian University Dubai provides on-site higher education, and the automotive luxury cluster includes Rolls-Royce, Mercedes-AMG, Cadillac, Alfa Romeo and Porsche TechArt showrooms.
Classified as Tier 1 — Core Capital, City Walk serves investors prioritising branded central urban positioning, lifestyle amenity depth and Meraas institutional management. This guide covers the acquisition strategy for HNW branded-apartment and central-Dubai yield buyers, the due diligence framework across completed Central Park clusters and off-plan Crestlane and Northline phases, the rental yield dynamics supported by central-Dubai professional tenant demand, and the portfolio construction role of this community as a Tier 1 branded urban anchor within a balanced Dubai residential portfolio. Careful phase and building selection is central to return optimisation given the observed PSF spread from AED 1,813 in ready Celadon stock to AED 3,506 in off-plan Central Park product. Long-term holders with 5 to 10 year horizons will find City Walk one of the most structurally defensible branded central apartment positions in Dubai.
CITY WALK: MARKET ANALYSIS AND INVESTMENT DYNAMICS
INFRASTRUCTURE AND CONNECTIVITY
City Walk sits at the junction of Al Safa Street (D71) and Al Wasl Road (D92) with direct Sheikh Zayed Road access. Business Bay Metro Station is within walkable range, providing Red Line connectivity and positioning City Walk ahead of peer branded communities like Palm Jumeirah, Bluewaters Island and District One which lack any metro proximity. The district is internally anchored by the 230,000 square metre Central Park, the Coca-Cola Arena — a 46,000 square metre multipurpose venue with 20,000 capacity completed in 2019 — the Green Planet bio-dome housing over 3,000 plants and animals, Valiant Clinic as a AED 300 million Houston Methodist-managed healthcare facility, Canadian University Dubai, Talabat regional headquarters with approximately 2,000 daily staff, and a boulevard retail cluster of 170-plus units including high-end automotive showrooms. Nearby anchors include Downtown Dubai, Dubai Mall, DIFC, Business Bay, Jumeirah Beach, La Mer and Al Safa Park. For a central Dubai apartment district, the combined retail, leisure, education, healthcare and employment density is difficult to replicate anywhere else in the city.
RENTAL MARKET AND TENANT PROFILE
Published rental trends show 1-beds at AED 160,000 per year, 2-beds at AED 252,000, 3-beds at AED 395,000 and 4-beds at AED 932,000. Gross yields run 5.91 per cent for 1-beds, 5.13 per cent for 2-beds, 4.99 per cent for 3-beds and 3.80 per cent for 4-beds, with the 1-bed yield competitive for a Tier 1 branded location. Executed rental transactions provide ground-truth data: three-bed renewals in the April to June 2026 period ranged from AED 215,000 to AED 273,000, a 27 per cent spread within the same months confirming that floor level, view orientation and unit condition drive significant variation even within the same community. The tenant profile is central Dubai professionals working in Downtown Dubai, DIFC and Business Bay who prioritise commute proximity combined with lifestyle amenity. HNW families are attracted by the Central Park green space and school proximity. A growing on-site employment tenant segment comes from Canadian University Dubai, Talabat and the boulevard retail cluster.
SUPPLY DYNAMICS AND PORTFOLIO POSITIONING
City Walk supply is controlled by Meraas through a multi-phase delivery programme to 2030. The district comprises 50 building developments, with Phase 3 adding 34 apartment buildings. Active delivery includes Crestlane 1 from AED 2.6 million (Q2-Q3 2029), Crestlane 4 and 5 from AED 2.7 to 2.8 million (Q2 2030), and Northline phases. Secondary market trading is active: Celadon 1 1-bed at AED 1,400,000 (AED 1,813 per sqft, ready), Erin at Central Park 3-bed at AED 8,000,000 (AED 3,506 per sqft, off-plan), Crestlane 5 Building A 1-bed at AED 2,880,000. The PSF spread from AED 1,813 to AED 3,506 means investors must underwrite at building level, not community level. Within a Dubai portfolio, City Walk occupies the Tier 1 branded urban allocation alongside Downtown Dubai. It offers superior green space integration and a more diversified employment ecosystem than Downtown, with lower global brand recognition. Position size one to three units.
CITY WALK: INVESTMENT STRATEGY AND ENTRY POINTS
The first strategic question is phase selection: completed Central Park clusters or Crestlane and Northline off-plan. Completed buildings including Myrtle, Viridian and Celadon offer proven rental track records and no construction risk. Celadon 1 1-bed transactions at AED 1,400,000 (AED 1,813 per sqft) trade at a materially lower PSF than off-plan Northline 2 at AED 2,909 per sqft and Crestlane at AED 2.7 to 2.9 million for 1-beds. The ready-market discount in older Central Park buildings creates an entry point for yield-focused investors — a 1-bed at AED 1,400,000 renting at AED 160,000 implies a strong gross yield, though actual executed rents may sit below the average for older buildings. The Crestlane and Northline phases offer newer specification, proximity to the latest Central Park amenity build-out and capital growth potential through to 2030 handover, but carry construction risk and no immediate rental income.
The second strategic question is unit size. The 1-bed segment delivers the strongest published yield at 5.91 per cent and trades at the most liquid price point around AED 2.5 to 2.9 million depending on building. The 2-bed segment at 5.13 per cent yield and approximately AED 4.46 million average is the family-professional sweet spot, with executed rental transactions showing upside to the average for well-positioned units. The 3-bed and 4-bed tiers offer capital preservation rather than yield: 3-bed at 4.99 per cent and 4-bed at 3.80 per cent, with AED 8 million and higher entry points. These are HNW family products rather than yield investments. Investors should match unit size to strategy: 1-bed for yield, 2-bed for balanced yield and family demand, 3-bed-plus for capital preservation and long-hold family occupation.
The third strategic question is portfolio positioning relative to Downtown Dubai. Both are Tier 1 central Dubai allocations. City Walk offers the 230,000 square metre Central Park with no equivalent in Downtown, integrated retail at boulevard level versus mall-dependent retail in Downtown, on-site employment anchors including Talabat and Canadian University Dubai, and Meraas-controlled quality consistency across the district. Downtown offers Burj Khalifa and Dubai Mall as globally recognised brand anchors, deeper secondary market liquidity, higher tourist footfall and established price floors supported by decades of transaction history. For a diversified Tier 1 allocation, holding both City Walk and Downtown positions provides exposure to the two distinct central Dubai lifestyle propositions.
The risk framework is explicit. Multi-phase delivery extending to 2030 means years of construction activity across the district — residents in completed buildings adjacent to Crestlane and Northline sites will experience noise, dust and visual disruption, which can suppress rents and should be factored into yield projections. The PSF spread from AED 1,813 to AED 3,506 means investors must underwrite at building level, not community level. The 4-bed tier at 3.80 per cent yield is compressed and suitable only for capital preservation or personal occupation. Meraas single-developer dependency means any strategic shift, financial difficulty or quality decline would affect the entire district — diversify across developers elsewhere in the portfolio. Business Bay Metro at walking distance is convenient but not as tight as metro-adjacent buildings in Downtown or Business Bay. Meaningful portfolio exposure to City Walk typically requires AED 3 million and above of committed capital.
SUPPLY DYNAMICS
Meraas single developer, multi-phase supply to 2030, Crestlane and Northline active, 50 buildings
TENANT PROFILE
HNW central-Dubai professionals, Downtown and DIFC executives, lifestyle tenants, families
KEY RISK FACTORS
Multi-phase construction disruption to 2030, yield compression at 4-bed tier, PSF spread, metro walk
KEY INFRASTRUCTURE
City Walk sits at the junction of Al Safa Street (D71) and Al Wasl Road (D92), with direct access to Sheikh Zayed Road (E11) and Al Khail Road (E44) connecting to Downtown Dubai, DIFC, Business Bay, Jumeirah Beach and La Mer. The district is internally anchored by the 230,000 sqm Central Park, the Coca-Cola Arena, Green Planet bio-dome, Valiant Clinic, Canadian University Dubai, Talabat regional headquarters, the boulevard retail cluster of 170+ units, La Ville Hotel and Suites and Rove City Walk. Nearby external anchors include Downtown Dubai, Dubai Mall, DIFC, Business Bay, Jumeirah Beach, La Mer and Al Safa Park. Adjacent communities include Al Wasl, Jumeirah 1, Al Safa, Business Bay and Downtown Dubai, reinforcing City Walk's positioning as Dubai's most integrated branded urban mixed-use district. Business Bay Metro is within walkable range.
Area fundamentals
- ASSET PROFILE
- Meraas branded central urban mixed-use community
- INVESTOR PROFILE
- HNW branded apartment + central urban yield investor
- TIER
- Tier 1 – Core Capital
- MARKET TYPE
- HNW-led, branded urban apartments, Meraas-controlled
- EST. POPULATION
- ~8,000–12,000 (projected)
- LAND SIZE
- ~9.7m sq ft
Next step
Request a briefing
You will get City Walk as a brief: the buildings on this page, the register readings behind them, and our view on each.