Palm Jumeirah AED 3,559/sqftDubai Maritime City AED 3,152/sqftDowntown Dubai AED 2,883/sqftDubai Islands AED 2,774/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,500/sqftDubai Marina AED 2,481/sqftDubai Hills Estate AED 2,459/sqftJumeirah Lakes Towers AED 2,321/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,051/sqftJumeirah Village Triangle AED 1,658/sqftDubai South AED 1,652/sqftArjan AED 1,584/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTINGPalm Jumeirah AED 3,559/sqftDubai Maritime City AED 3,152/sqftDowntown Dubai AED 2,883/sqftDubai Islands AED 2,774/sqftDubai Creek Harbour AED 2,563/sqftBusiness Bay AED 2,500/sqftDubai Marina AED 2,481/sqftDubai Hills Estate AED 2,459/sqftJumeirah Lakes Towers AED 2,321/sqftMohammed Bin Rashid City AED 2,098/sqftAl Jaddaf AED 2,051/sqftJumeirah Village Triangle AED 1,658/sqftDubai South AED 1,652/sqftArjan AED 1,584/sqftJumeirah Village Circle AED 1,487/sqftDubai Sports City AED 1,328/sqftALL DLD SALES · OFF-PLAN + EXISTING
DLD · MEDIAN 12M TO OCT 2026
Dubai Harbour, Dubai — area guide

Area guide · Dubai

Dubai Harbour Investment Guide

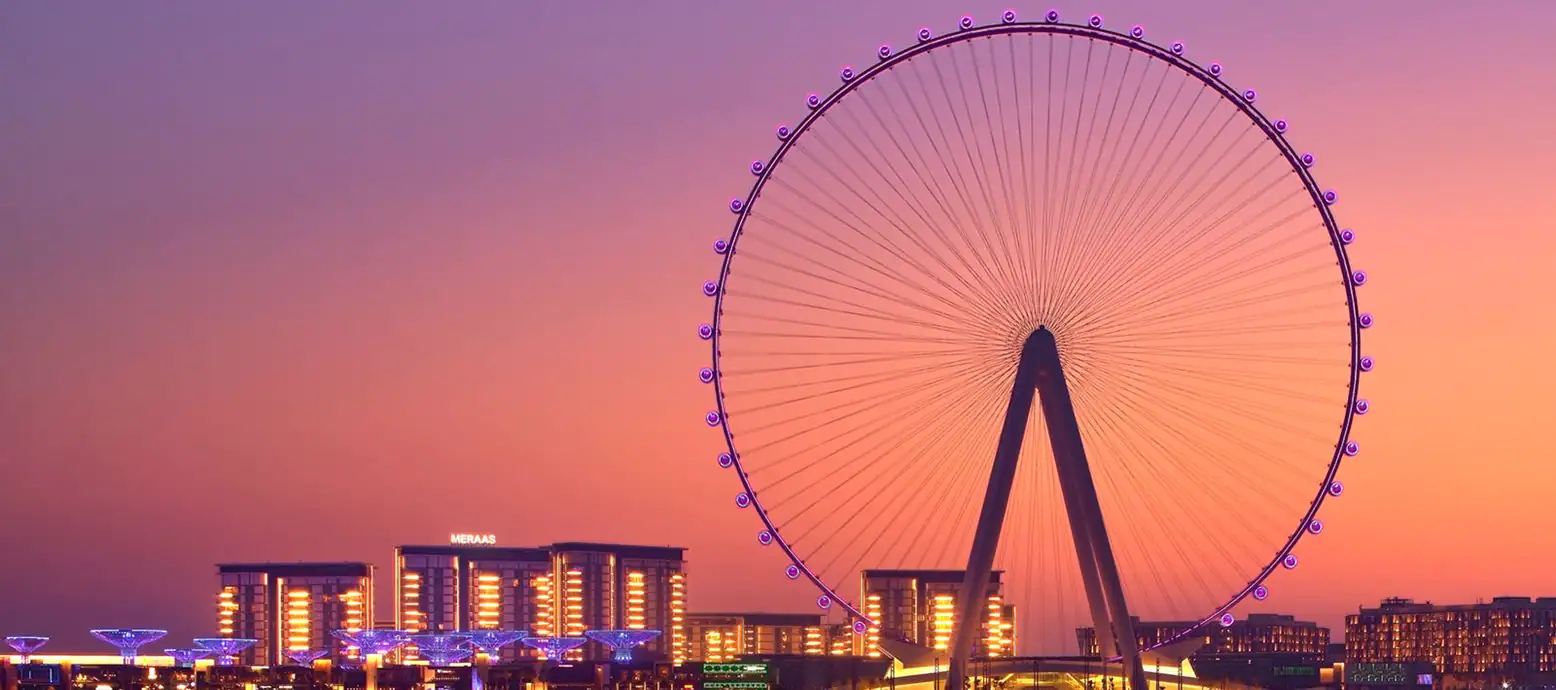
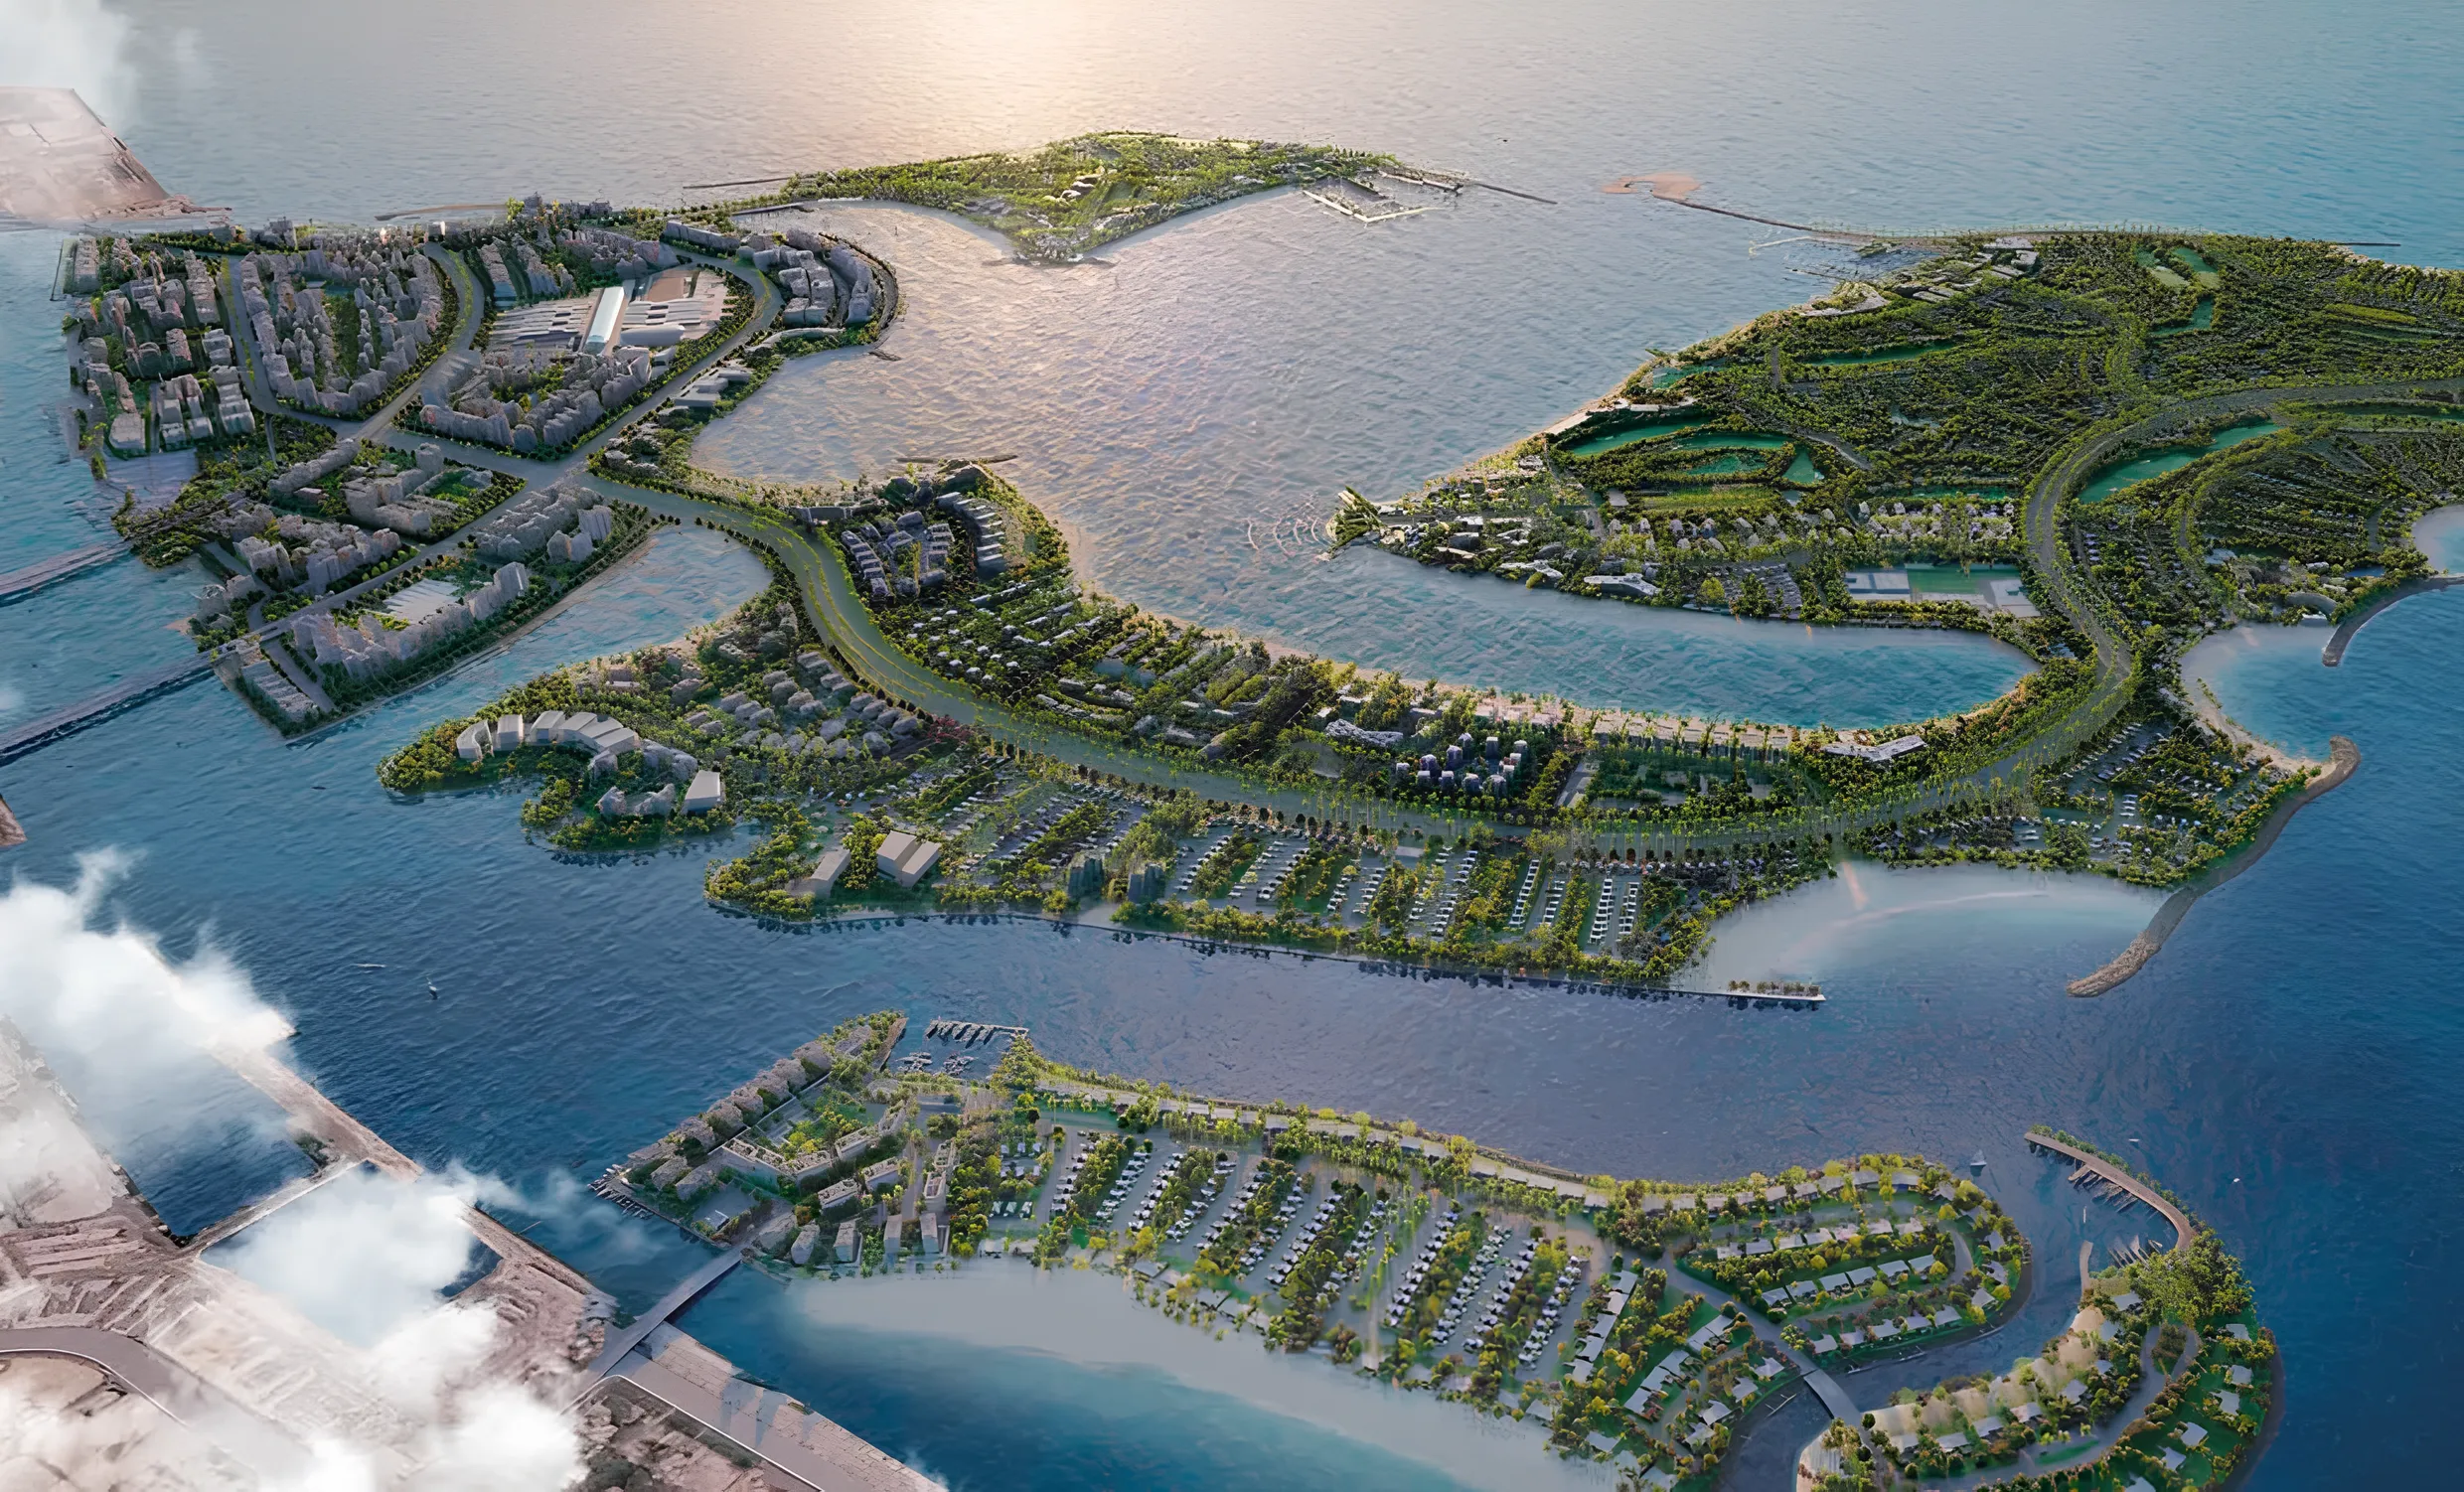
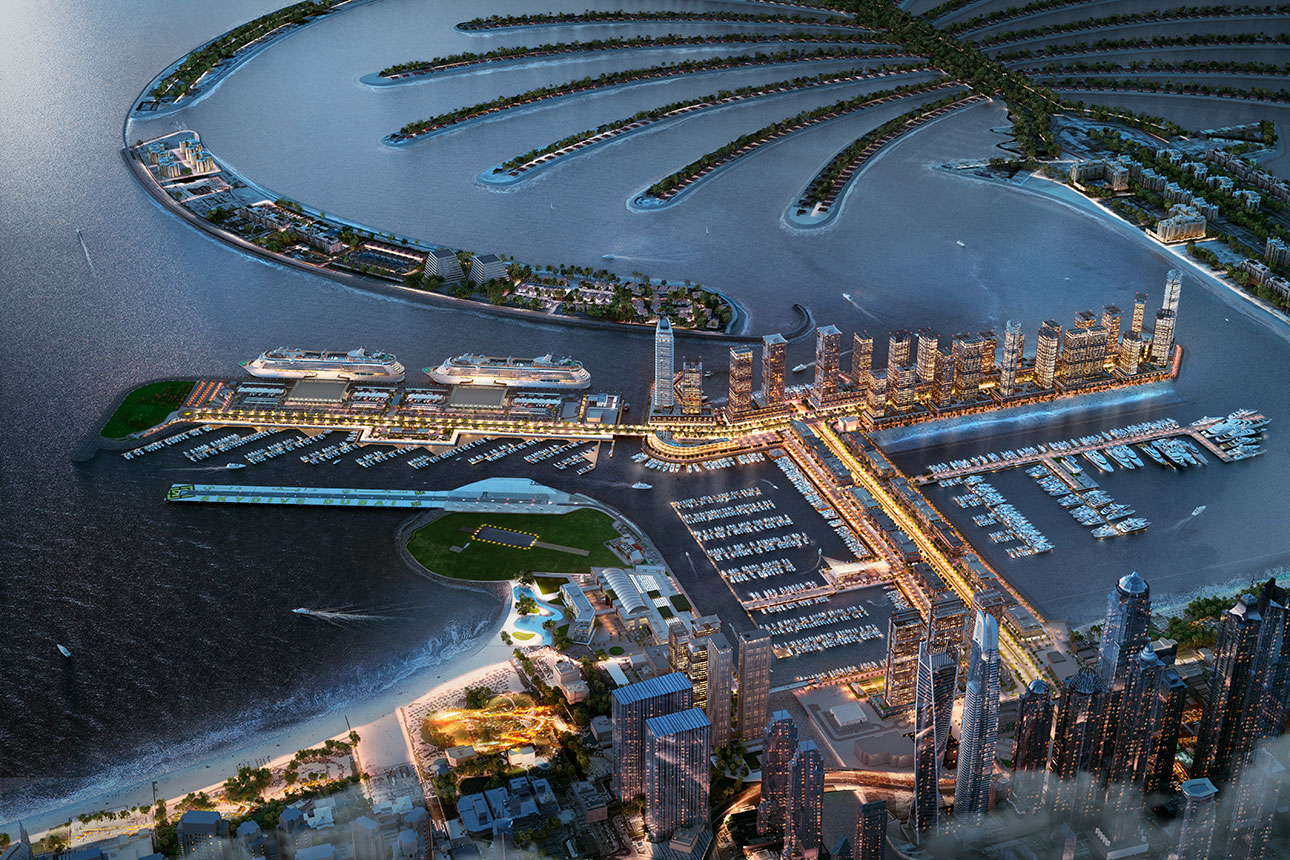
Dubai Harbour is a 20 million square foot waterfront masterplan by Meraas Holding, built at Mina Al Seyahi between Palm Jumeirah and Bluewaters Island with direct frontage onto the Arabian Gulf.

I want to
Budget

Answer the two questions and this page reorders itself around them. Nothing is sent until you ask for something.

Sales prices

2,000–3,500AED/sqft, 2017
Launch price
Developer launch pricing when the community came to market, from this guide. Historic — not a current valuation.

A building can sit well under the area figure. Tell us which one you have in mind and we will read its own register history back to you.

Rental rates

AED 122,668a year
Median annual rent
Ejari — 33,176 registered contracts in the 24 months to 16 October 2026. Marsa Dubai sector — Dubai Marina, Dubai Harbour, Jumeirah Beach Residence, Bluewaters and Tecom Site D together.
AED 107.5per sq ft a year
Median rent per sq ft
Same contracts, same window.
~4–6%
Gross yield band
Mitchell’s own range for Dubai Harbour, from this guide — an assessment, not a register figure.

The register gives one rent figure for the area. What a specific building lets for, and how quickly, is the question worth asking before you buy for income.

Ready buildings with recent sales

Median registered price per bedroom type. Hotel rooms and serviced units are left out where the register marks them.

BuildingUnitMedian priceMedian sq ftAED/sqftSales
Grand Bleu Tower interiors by Elie Saab
Emaar Development P.J.S.C. · completed 2023 · 90 registered sales
1 bedAED 2.7m7953,37935
2 bedAED 5.4m1,4183,80438
3 bedAED 10.12m2,0894,51614
4 bedAED 16.6m2,7265,6313
Palace Beach Residence
Emaar Development P.J.S.C. · completed 2025 · 75 registered sales
1 bedAED 2.65m8513,26841
2 bedAED 5m1,2183,85617
3 bedAED 6.95m1,9183,71115
4 bedAED 23.15m5,6324,2852
Beach Mansion
Emaar Development P.J.S.C. · completed 2025 · 47 registered sales
1 bedAED 2.45m7903,10519
2 bedAED 4.2m1,2343,29325
3 bedAED 6.4m1,6903,40023
4 bedAED 8.6m2,4483,5383
MARINA VISTA
Emaar Development P.J.S.C. · completed 2023 · 42 registered sales
1 bedAED 2.35m8272,95722
2 bedAED 4.25m1,1493,69718
3 bedAED 6.43m1,7553,6612
SUNRISE BAY
Emaar Development P.J.S.C. · completed 2021 · 37 registered sales
1 bedAED 2.25m8002,83813
2 bedAED 3.8m1,2782,98318
3 bedAED 5.85m1,9263,0646
BEACH VISTA
Emaar Development P.J.S.C. · completed 2022 · 30 registered sales
1 bedAED 2.53m7123,47912
2 bedAED 4.25m1,1643,7187
3 bedAED 7m2,1313,58211
BEACH ISLE
Emaar Development P.J.S.C. · completed 2023 · 27 registered sales
1 bedAED 2.42m7653,1296
2 bedAED 4.2m1,1983,40013
3 bedAED 8.1m1,9004,4118

DLD register — sales of units registered 28 April 2025 to 24 October 2026, duplicates removed. The sale count is the building’s registered sales of completed property.

How this table is built

Buildings with ten or more registered sales of completed property in the window are listed by default; the rest are behind “Show all buildings”. Hotel rooms and serviced units are left out where the register marks them. “Completed property” is the register’s own registration type, which does not separate an owner’s resale from a developer’s first sale of a finished unit, so neither do we. Bedroom medians are over the building’s registered sales in the window and are shown only where at least five sales of that type. AED/sqft on a row is the register’s median rate for that type, or median price over median size where it publishes none.

Two towers in the same block can sit points apart on net yield once service charges and occupancy are counted. Name the buildings and we will tell you which side of that line each one sits.

Under construction now

Projects the register records as under construction here, with the registered sales behind each figure; a project with fewer than ten is marked as a small sample. Hotel rooms and serviced units are left out where the register marks them.

ProjectCompleteMedian AED/sqftSalesMedian price by unit
W Residences at Dubai Harbour
Arada Developments L.L.C S.O.C · register end date Dec 2028
4%
at 13 Oct 2026
4,7371411 bed AED 5.05m · 2 bed AED 7.75m · 3 bed AED 13.07m · 4 bed AED 20.51m · 5 bed AED 36.66m (3 sales)
+8.7% Q2 2025 → Q1 2026
DAMAC BAY
DAMAC J R Two Investment L.L.C · register end date Jan 2027
33.8%
at 18 Aug 2026
3,488721 bed AED 3.87m · 2 bed AED 5.45m · 3 bed AED 9.18m (3 sales)
DAMAC BAY 2
DAMAC MDN Investment L.L.C
30.3%
at 15 Jul 2026
4,448
7 sales
681 bed AED 3.46m · 2 bed AED 4.16m · 3 bed AED 7.94m · 5 bed AED 37.67m (one sale)
Dubai Harbour Residences (Area 3)
Harbour One Investment L.L.C · register end date Jan 2028
34.8%
at 11 Aug 2026
3,520
8 sales
591 bed AED 4.78m · 2 bed AED 9.7m · 3 bed AED 9.68m · 4 bed AED 21.92m (3 sales)
Sobha Seahaven Tower B & C
Sobha L.L.C · register end date Oct 2028
40.2%
at 18 Sep 2026
4,200
5 sales
591 bed AED 3.6m · 2 bed AED 7.25m · 3 bed AED 15.94m · 4 bed AED 23.5m (one sale)
Dubai Harbour Residences (Area 1)
Harbour One Investment L.L.C · register end date Jan 2028
30.3%
at 11 Aug 2026
4,040
2 sales
551 bed AED 4.26m · 2 bed AED 9.02m · 3 bed AED 8.84m · 4 bed AED 23.49m
SEAPOINT
Emaar Development P.J.S.C. · register end date Mar 2028
Project brief
36.8%
at 24 Jun 2026
4,362411 bed AED 3.04m · 2 bed AED 5.32m · 3 bed AED 8.99m · 4 bed AED 26.24m
Address The Bay
Emaar Development P.J.S.C. · register end date Dec 2026
70.1%
at 15 Jul 2026
3,864371 bed AED 3m · 2 bed AED 7m · 3 bed AED 9.75m · 4 bed AED 22.23m (2 sales)
BAYVIEW
Emaar Development P.J.S.C. · register end date Jul 2028
63%
at 14 Sep 2026
5,145361 bed AED 3.74m · 2 bed AED 6.44m · 3 bed AED 10.47m · 4 bed AED 21m
Sobha Seahaven Tower A
Sobha L.L.C · register end date Apr 2028
37%
at 6 Aug 2026
4,707
5 sales
241 bed AED 4.52m · 2 bed AED 5.7m · 3 bed AED 22.42m (3 sales) · 4 bed AED 28.16m (4 sales) · 5 bed AED 52.53m (2 sales)
THE BRISTOL Emaar Beachfront
Emaar Development P.J.S.C. · register end date Sep 2029
5.8%
at 23 Jun 2026
191 bed AED 4.5m · 2 bed AED 7.45m · 4 bed AED 14.56m (2 sales) · 5 bed AED 34m (one sale)

All projects under construction in Marsa Dubai

DLD project register (completion percentage as read on the date shown) and transaction register — sales of units registered 28 April 2025 to 24 October 2026, duplicates removed.

How this table is built

Completion percentage is the register’s own, read on the date shown against each project. The median is over the project’s registered sales in the window and is published only from ten sales; quarterly movement only where each quarter holds twenty or more. Hotel rooms and serviced units are left out where the register marks them.

Completion percentage and the register’s own median are the two numbers a payment plan should be read against.

Developments here

Multiple · ~2,000+ (+3,000 pipeline) units · launched 2017
Dubai Harbour
The developer, the launch date and the unit count are this guide’s own, as captured.

What a development here is worth today is a register question, and we will read it back to you building by building.

Deals below market here now

UnitAskingSizePer sq ft
1-BR IN PALACE BEACH RESIDENCE - TOWER 2AED 1,950,000796 sq.ftAED 2,450
3-BR IN SOBHA SEAHAVENAED 7,700,000
20.6% below o.p.
AED 3,222
2-BR IN W RESIDENCES
handover Q4 2028
AED 6,870,000
15.3% below o.p.
1,795 sq.ftAED 3,827

Mitchell’s deal pages, as published. Asking prices and the discount are stated on each deal’s own page with their basis; we act for the buyer on every one.

Each of these can be read against the register history of its own building before you commit.

DUBAI HARBOUR: MERAAS PREMIUM WATERFRONT CAPITAL MASTERPLAN

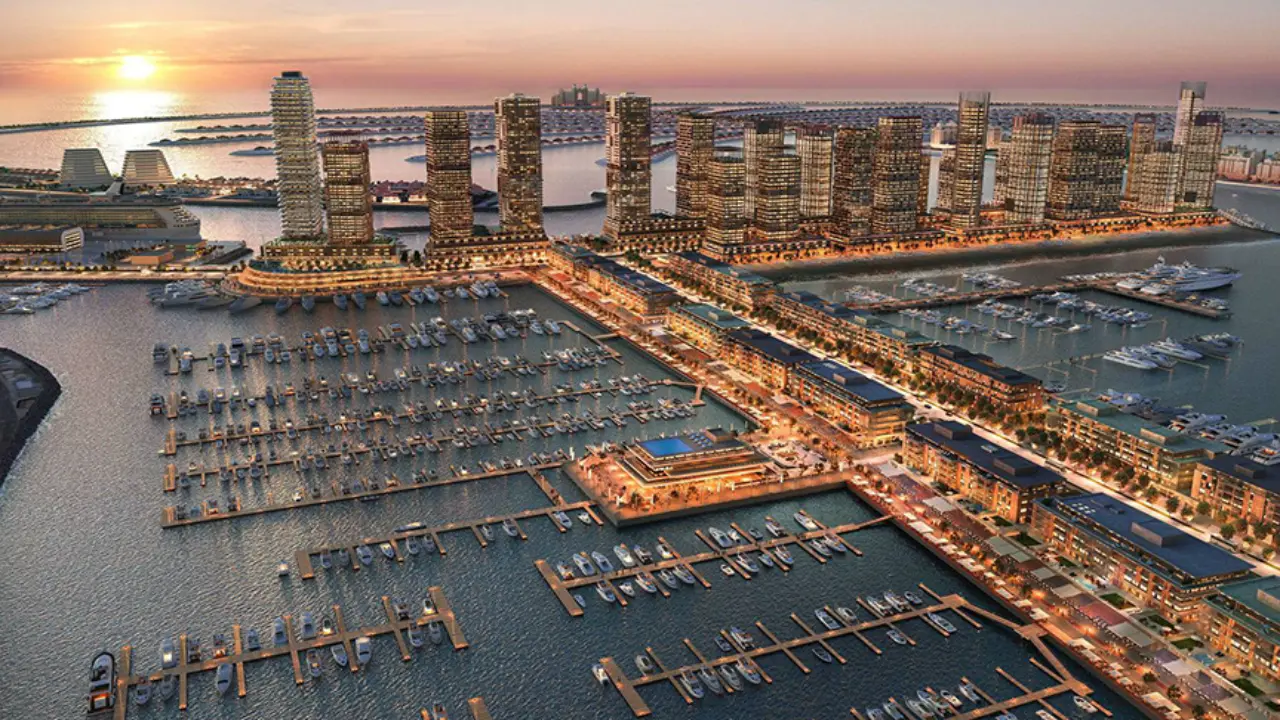
Construction began in 2017 with the initial phase completing in February 2021, with Aecom serving as architectural consultant and Kier together with Al Shafar General Contractors delivering the main build. The masterplan anchors the largest marina in the MENA region, accommodating close to 700 yachts including vessels up to 160 metres, alongside two cruise terminals and an integrated retail, hospitality and leisure cluster.

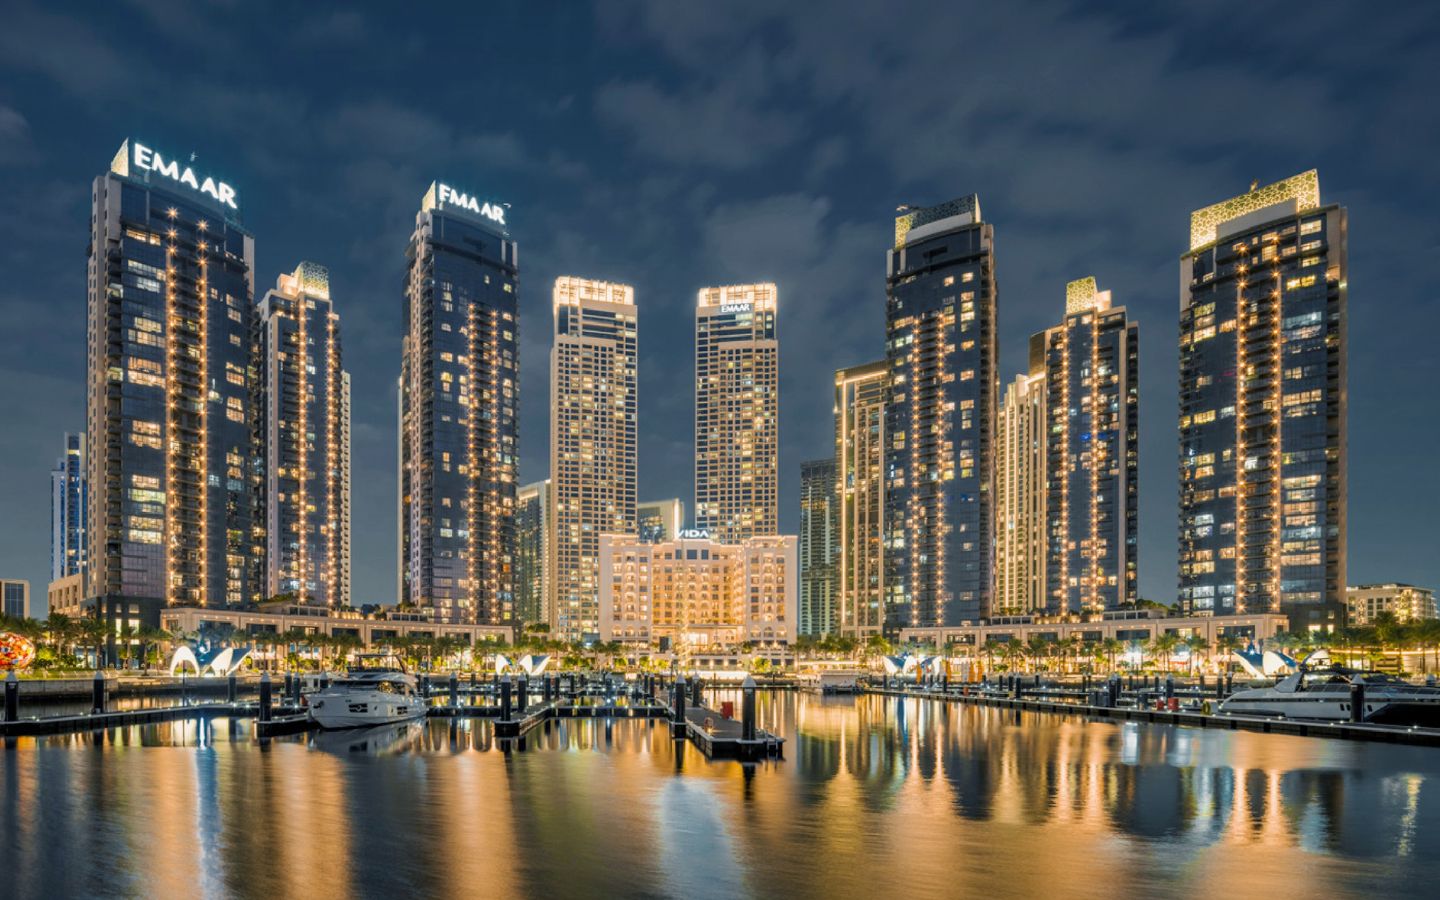
The masterplan comprises 22 building developments. Seven residential towers are complete and occupied, all within the Emaar Beachfront sub-community: Marina Vista, Sunrise Bay, Grand Bleu Tower, Palace Beach Residence, Beach Vista, Beach Isle and Beach Mansion, which the DLD register records as completed on 30 December 2025 (DLD register, as at 8 September 2026). Fifteen further projects are under construction or planned, spanning Sobha Seahaven, Address Residences The Bay, Address Bayview, Seapoint, DAMAC Bay by Cavalli, DAMAC Bay 2 by Cavalli, Beachgate by Address, The Bristol Luxury Hotels & Resorts, The Residences at Dubai Beach EDITION (Shamal Holding and Marriott), and W Residences at Dubai Harbour (Arada, AED 1.55 billion contract awarded 23 February 2026). The multi-developer delivery structure creates diversified brand exposure across the masterplan.

For investors, the honest framing is that Dubai Harbour is a Tier 1 capital-preservation waterfront play, not a yield vehicle. The residential rental dataset currently exists only for the Emaar Beachfront sub-community, where 12-month aggregated data shows gross yields of 4.81 to 5.24 per cent across the 1, 2 and 3-bedroom formats. Average annual asking rents run AED 158,000 for 1-beds, AED 259,000 for 2-beds and AED 455,000 for 3-beds. Non-Emaar towers are predominantly off-plan and have no stabilised rental track record. The investment thesis rests on scarce Gulf-facing land, infrastructure already operational in the marina and cruise terminals, and a long-duration pipeline controlled by institutional-grade developers, rather than short-cycle yield compression.

Location positions Dubai Harbour within Dubai's most valuable luxury residential corridor. Primary vehicle access runs via King Salman bin Abdulaziz Al Saud Street, with an RTA-built bridge linking directly to Sheikh Zayed Road reported at 65 per cent completion in January 2026 — this bridge is expected to compress travel time materially once commissioned. A pedestrian bridge connects to the west crescent of Palm Jumeirah. Nearby anchors include Palm Jumeirah, Bluewaters Island, JBR, The Walk, Marina Walk, Dubai Marina, JLT and Mall of the Emirates. Adjacent hospitality includes Dubai Marriott Harbour Hotel & Suites, Habtoor Grand Resort and Grosvenor House. For a waterfront masterplan, the combination of marina, cruise terminal, adjacent branded hospitality and Palm Jumeirah pedestrian connectivity is unmatched elsewhere in Dubai.

Classified as Tier 1 — Core Capital, Dubai Harbour serves investors prioritising scarce Gulf-facing waterfront positioning, institutional-grade developer diversification and long-duration infrastructure tailwinds. This guide covers the acquisition strategy for HNW capital preservation and GCC family office buyers, the due diligence framework across stabilised Emaar Beachfront stock and off-plan Sobha, Address, DAMAC, Arada and Shamal towers, the rental yield dynamics supported by HNW maritime-lifestyle tenant demand, and the portfolio construction role of this community as a Tier 1 waterfront anchor within a balanced Dubai residential portfolio. Careful tower and phase selection is central to return optimisation given the PSF spread from AED 3,544 in ready Emaar stock to AED 4,371 in off-plan DAMAC product. Long-term holders with 5 to 10 year horizons will find Dubai Harbour one of the most structurally defensible premium waterfront positions in Dubai.

DUBAI HARBOUR: MARKET ANALYSIS AND INVESTMENT DYNAMICS

INFRASTRUCTURE AND CONNECTIVITY

Primary vehicle access to Dubai Harbour runs via King Salman bin Abdulaziz Al Saud Street. An RTA-built bridge linking the masterplan directly to Sheikh Zayed Road was reported at 65 per cent completion in January 2026 and upon delivery is expected to compress travel time to around three minutes — a material shift for a location that has historically leaned on marina-side approach roads. A pedestrian bridge connects the masterplan to the west crescent of Palm Jumeirah. The marina accommodates around 700 yachts with capacity for vessels up to 160 metres and includes a fuelling station for vessels up to 50 metres. Two cruise terminals serve the maritime tourism economy. Sustainability infrastructure includes the UAE's first floating waste collector PixieDrone and the Seaguardians sustainability committee. Skydive Dubai sits roughly half a kilometre away; Marina Walk, The Walk, JBR Beach and Marina Beach are all within short access. Adjacent hospitality includes Dubai Marriott Harbour Hotel & Suites, Habtoor Grand Resort (Autograph Collection) and Grosvenor House.

RENTAL MARKET AND TENANT PROFILE

The only stabilised rental dataset inside Dubai Harbour is Emaar Beachfront. Twelve-month aggregated data shows gross rental yields of 5.24 per cent on 1-bedroom units, 4.81 per cent on 2-bedroom units and 5.07 per cent on 3-bedroom units — a 4.81 to 5.24 per cent envelope across core formats. Average annual asking rents over the same window run AED 158,000 for 1-beds, AED 259,000 for 2-beds and AED 455,000 for 3-beds. The tenant cohort is populated by HNW professionals in finance, energy and hospitality, GCC family office secondees holding Dubai as a regional base, and premium lifestyle renters seeking Palm Jumeirah sight lines without committing to Palm pricing or Palm commute friction. Non-Emaar Beachfront towers — Sobha Seahaven, DAMAC Bay, the two Address Residences projects, Beachgate, Seapoint and the new Shamal and Arada launches — remain predominantly off-plan or newly handed-over and do not yet have consolidated 12-month ROI datasets. Investors underwriting these towers must stress-test against the Emaar Beachfront precedent rather than a tower-specific stabilised yield.

SUPPLY DYNAMICS AND PORTFOLIO POSITIONING

Recent DLD transactions give a live pricing read. April 2026 sales include Beach Mansion Tower 1 2-bed at AED 4.30M, two Beachgate 3-bed sales at AED 6.48M and AED 6.57M, Address Bayview Tower 2 1-bed at AED 3.85M, Palace Beach Residence Tower 2 4-bed at AED 23.65M, and Address Bayview Tower 1 2-bed at AED 7.01M. February 2026 off-plan pre-registrations include DAMAC Bay Tower B 2-bed at AED 4,371 per sqft and DAMAC Bay 2 Tower B 2-bed at AED 4,331 per sqft, alongside a secondary Sunrise Bay 1-bed at AED 3,544 per sqft. Supply is tightly phased and developer-controlled with no evidence of disorderly inventory release. Within a Dubai portfolio, Dubai Harbour fits the Tier 1 core-capital bucket alongside Downtown Dubai and Palm Jumeirah — a long-duration hold chosen for waterfront scarcity and institutional infrastructure, not yield compression.

DUBAI HARBOUR: INVESTMENT STRATEGY AND ENTRY POINTS

The first strategic question is which cohort of the masterplan you are buying into. The stabilised-rental thesis only holds inside Emaar Beachfront today — six delivered towers with a documented 4.81 to 5.24 per cent gross yield band. If an investor needs underwriting certainty and existing tenants from day one, capital should concentrate there via secondary market acquisition rather than off-plan. A ready Sunrise Bay 1-bedroom at AED 3,544 per square foot sits materially below the off-plan DAMAC Bay pricing of AED 4,300-plus per square foot and starts paying rent immediately. For investors comfortable with handover risk and interested in higher appreciation beta, off-plan Sobha Seahaven, Address Bayview, Address Residences The Bay, DAMAC Bay, DAMAC Bay 2 or the newly launched Arada W Residences offer exposure to the next construction wave. These must be stress-tested against the Emaar Beachfront rental precedent and underwritten with explicit allowance for the 12 to 24 month construction window before first tenancy.

The second strategic question is the infrastructure inflection timing. The new Sheikh Zayed Road bridge was reported at 65 per cent completion in January 2026. Full commissioning will materially improve ground access and should feed through into pricing and liquidity. A thesis-driven investor can reasonably position ahead of that inflection either through secondary Emaar Beachfront buying or through disciplined off-plan allocation, but should confirm handover status directly rather than assume the bridge lands on any public schedule. The marina and cruise terminal infrastructure is already operational, so the incremental upside from those anchors is already partially priced in; the remaining beta is in retail, F&B and hospitality completion across the later phases.

The third strategic question is portfolio weighting. Dubai Harbour should anchor the waterfront line in a diversified Dubai portfolio alongside Palm Jumeirah exposure and a Downtown Dubai core holding. Concentrating a portfolio in Dubai Harbour alone means concentrating execution risk across multiple developers (Meraas, Emaar, Sobha, Address, DAMAC, Shamal, Arada) and phase-delivery dependencies. A sensible cap is 30 to 40 per cent of the Dubai allocation in the masterplan, split between one delivered Emaar Beachfront hold for stabilised cash flow and one off-plan allocation in a later-phase tower for appreciation exposure. Unit format preference should favour 2 and 3-bedroom apartments — these match the HNW tenant profile evidenced by the AED 259,000 and AED 455,000 average rents, lease faster than 1-beds in premium stock, and carry deeper resale demand than 4-bed penthouses or ultra-large units.

The risk framework is non-negotiable. Non-Emaar Beachfront towers carry unproven rental performance and underwriting them at Emaar Beachfront yields is an assumption, not a fact. Construction noise will persist across the masterplan into 2027 and 2028. Premium waterfront is highly correlated to GCC capital sentiment; stress-test holding periods and occupancy assumptions against a scenario where luxury rental demand softens by 15 to 20 per cent. Keep liquidity reserves as waterfront premium assets conventionally take 60 to 90 days to transact. Maintain a documented exit thesis aligned to the bridge handover, the cruise-terminal passenger growth trajectory and Year 5 retail and F&B maturation. Meaningful portfolio exposure to Dubai Harbour typically requires AED 5 million and above of committed capital.

SUPPLY DYNAMICS

Meraas master developer, multi-developer phased supply, 22 towers, institutional-grade brands

TENANT PROFILE

HNW finance professionals, GCC family office secondees, premium waterfront lifestyle renters

KEY RISK FACTORS

Multi-phase construction to 2028, access bottleneck pending bridge, non-Emaar yield unproven

KEY INFRASTRUCTURE

Dubai Harbour sits at Mina Al Seyahi in the broader Dubai Marina corridor, with vehicle access via King Salman bin Abdulaziz Al Saud Street and an RTA-built bridge to Sheikh Zayed Road (E11) at 65 per cent completion in January 2026 expected to compress travel time materially. A pedestrian bridge connects to the west crescent of Palm Jumeirah. The masterplan is internally anchored by the largest marina in MENA accommodating ~700 yachts up to 160 metres, two cruise terminals, Skydive Dubai, marina retail and dining, and 22 tower developments across Emaar Beachfront, Sobha, Address, DAMAC, Arada and Shamal clusters. Nearby external anchors include Palm Jumeirah, Bluewaters Island, JBR, The Walk, Marina Walk, JBR Beach, Marina Beach, Dubai Marina, JLT and Mall of the Emirates. Adjacent communities include Palm Jumeirah, JBR, Dubai Marina and Bluewaters Island, reinforcing Dubai Harbour's positioning as Dubai's premier Gulf-facing multi-developer waterfront capital masterplan.

Area fundamentals

ASSET PROFILE
Meraas premium waterfront capital masterplan
INVESTOR PROFILE
HNW capital preservation + GCC family office buyer
TIER
Tier 1 – Core Capital
MARKET TYPE
HNW-led, waterfront apartments, multi-developer
EST. POPULATION
~5,000–10,000 (projected)
LAND SIZE
~20m sq ft

Next step

Request a briefing

You will get Dubai Harbour as a brief: the buildings on this page, the register readings behind them, and our view on each.
Sent with your enquiry:Dubai Harbourpurpose not statedbudget not statedno buildings on screenasked from: the brief

We come back with specifics, not a brochure. Stephen Mitchell · RERA BRN 68593 · in Dubai since 2007.

Location

Dubai Harbour, Dubai

Get Directions

Try it yourself

Investor Tools

Rental Yield Calculator

Model the gross and net return on a Dubai buy-to-let purchase. It covers service charges, void periods and acquisition costs.

All-in purchase price before transaction costs.

Total contracted rent for one year, before charges.

Community and building service charges, annualised.

5%

Your buffer for void periods. 5% is about 18 days empty a year — a month is 8%.

7%

7% is the 4% DLD transfer fee, 2% agency plus VAT, and DLD's flat registration lines. It excludes the developer NOC and any legal quote — see the Buying Costs Calculator for the full itemisation.

6% net

The net yield a deal has to clear to interest you. Sets the target line on the curve — it does not change the yield above it.

5.3%Net rental yield
Moderate yield
Gross yieldGross yield: 7.00%
Net annual incomeNet annual income: AED 84,750
Monthly net incomeMonthly net income: AED 7,063
Total cash investedTotal cash invested: AED 1,605,000

Against your 6% hurdle

Short of it
9.1%0%AED 975KAED 2.03M
Net yield (vertical) against the price you pay (horizontal), on the rent, charges and costs entered. The gold dot is your deal; the line across is your hurdle.
Price that clears it
AED 1,320,093AED 179,907 below your price — a 12.0% discount.
Rent that clears it
AED 117,158AED 12,158 a year more than you have entered, at this price.

Estimates for guidance only, assuming full-year occupancy net of the vacancy allowance above. Actual returns depend on financing, unit condition and market timing — speak to an advisor for a deal-specific model.

Email my results

We’ll send this summary — your figures and the results — to your inbox.

Next step

We'll hunt deals that meet or beat this yield hurdle

Send us this scenario and we'll go into the market against it — on-market and off — qualify what we find, and only come back with what clears your number.

Got questions?

Get Answers!
Continue reading

The closest area guides to this one, matched on subject.

Showing 4 of 101 Dubai area guides.

Browse all 101 area guides
Need help?